
UK biotech financing 2024
April – June 2024
 Overall figures
Venture capital
Public markets
Finance Report 2022
Finance Report 2024 Q1
Finance Report 2024 Q3
Finance Report 2023
Finance Report 2024

 Overview
Investment in the UK innovative life science and biotech industry showed strong growth between April and June in the face of continuing domestic and global economic uncertainty.
Increased investor interest and confidence in the industry was demonstrated by significant public financing and a step-up in venture capital funding driven by a handful of large deals.
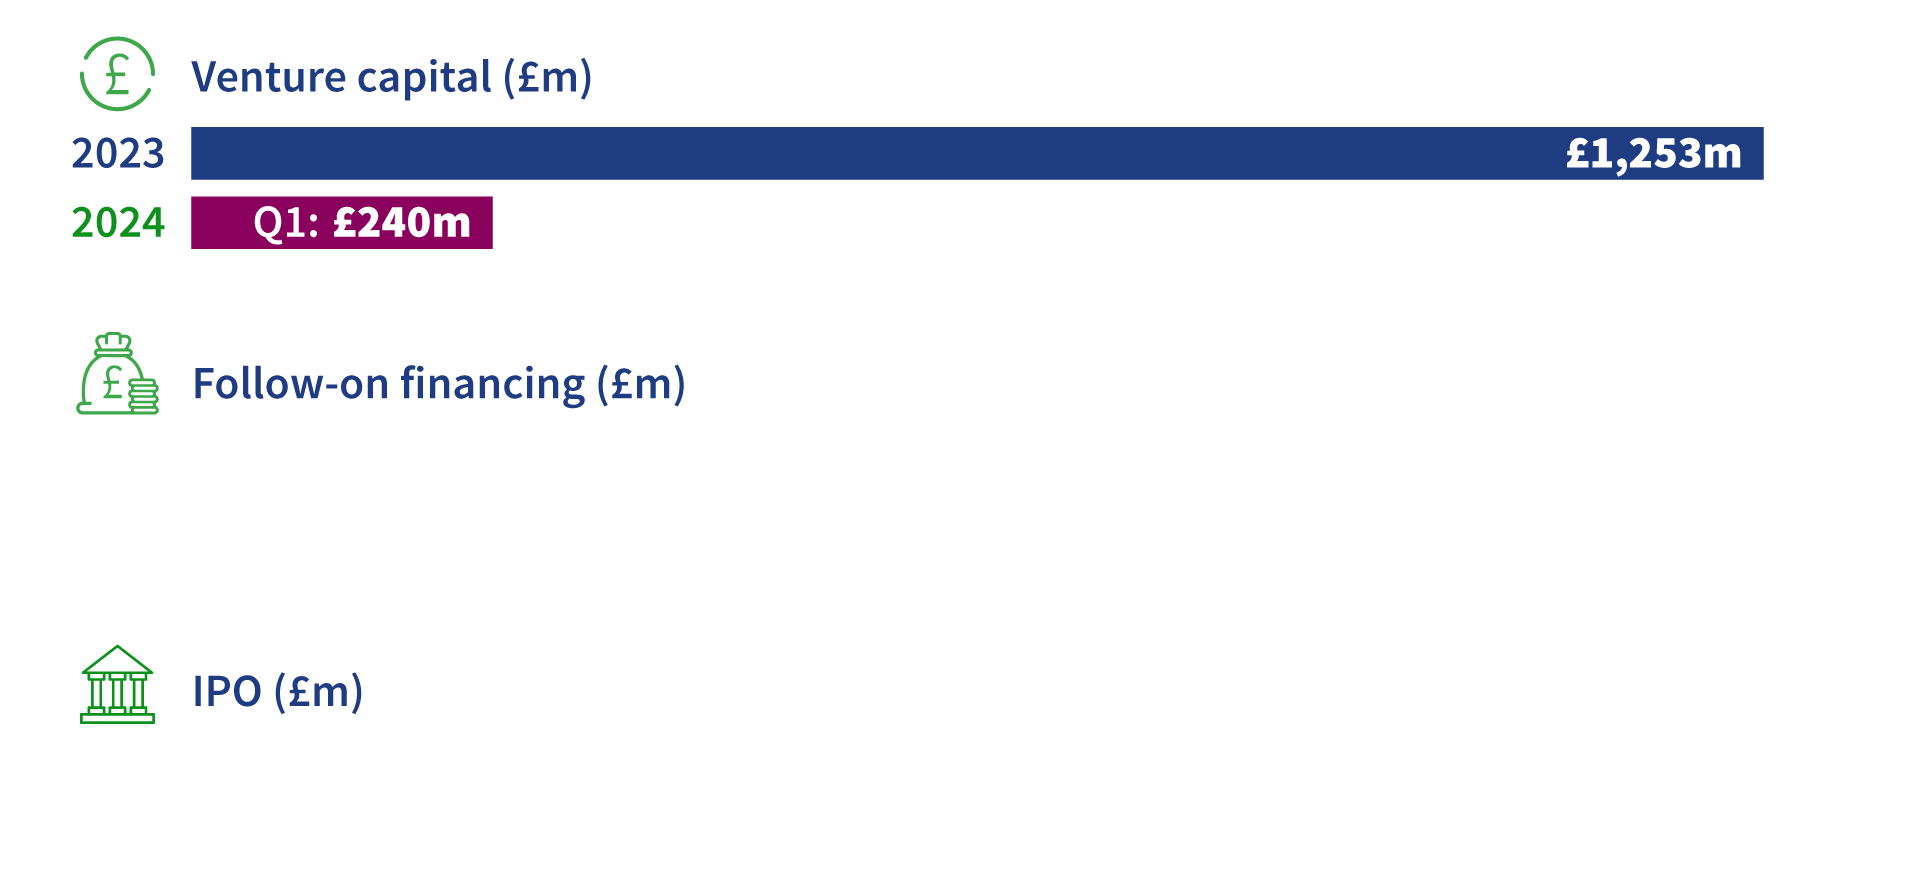
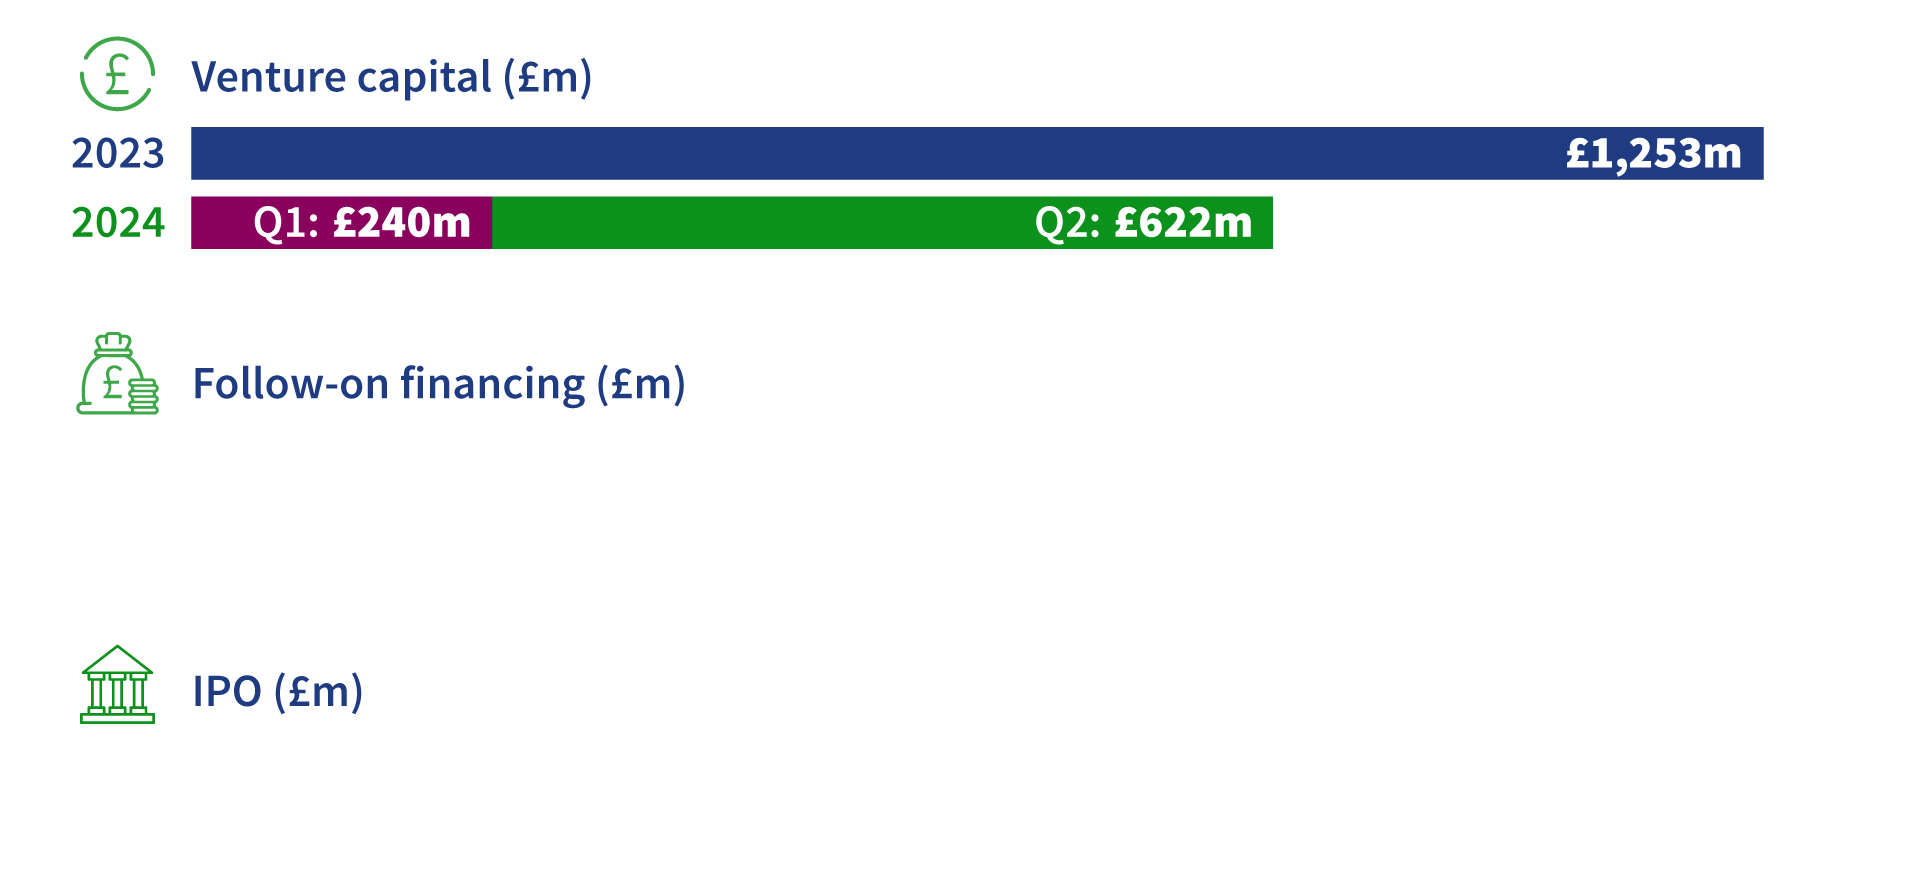
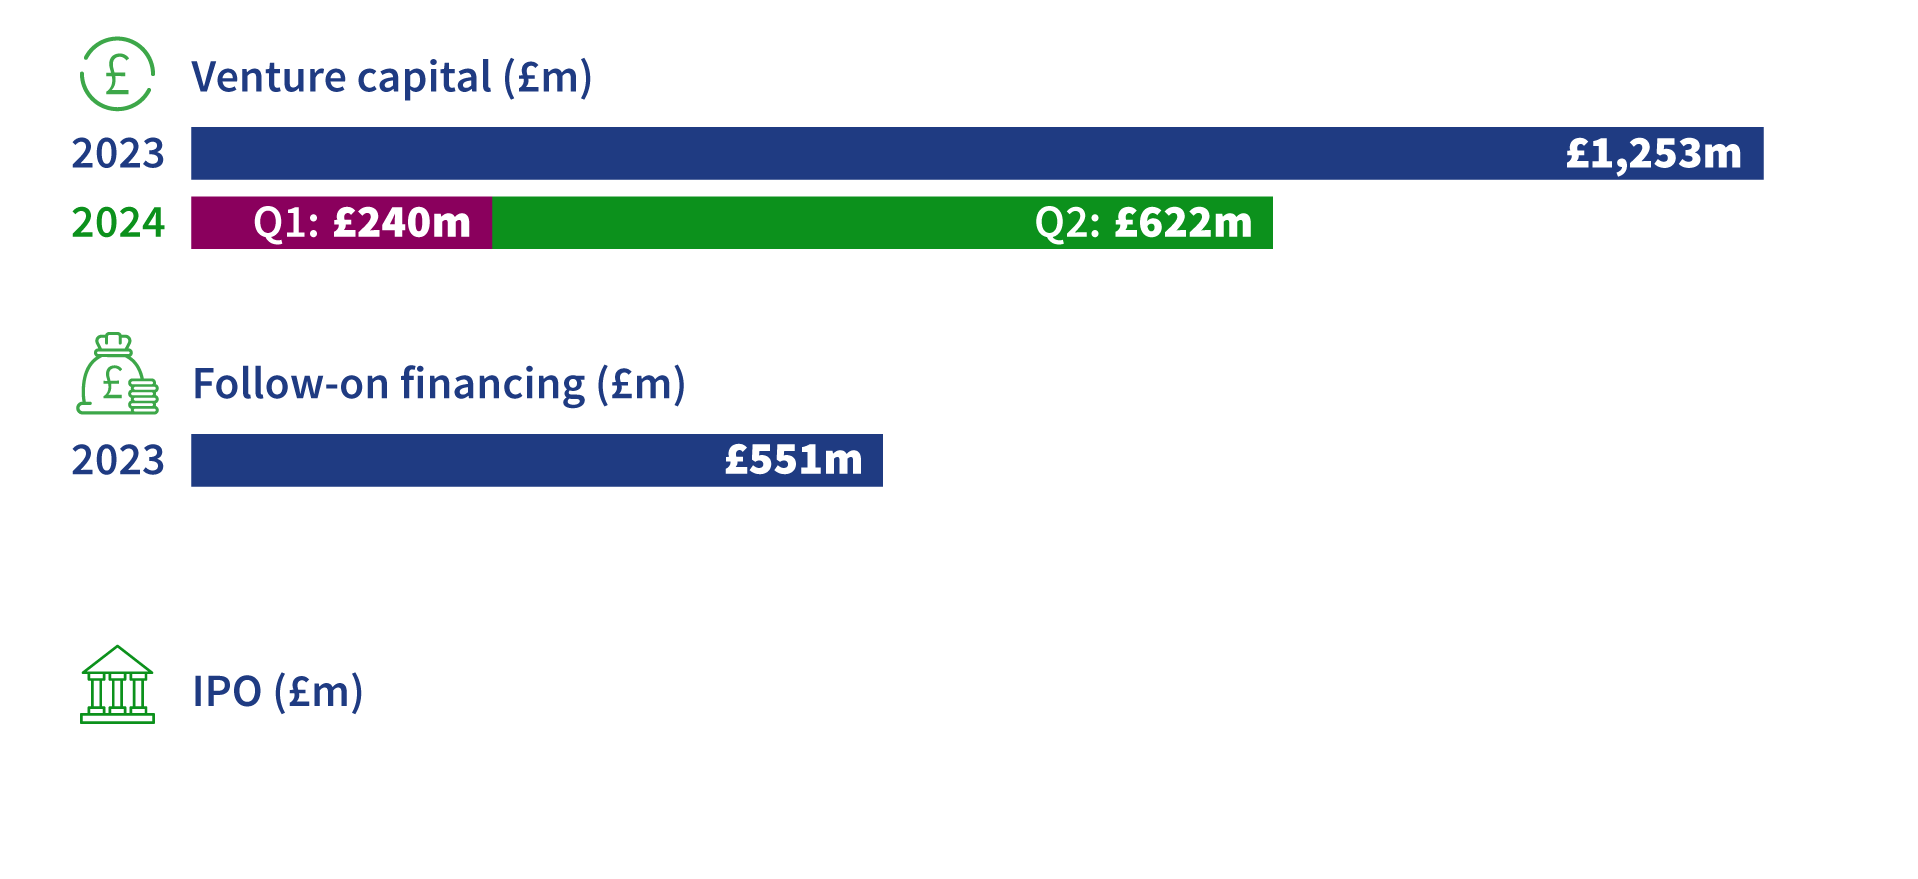
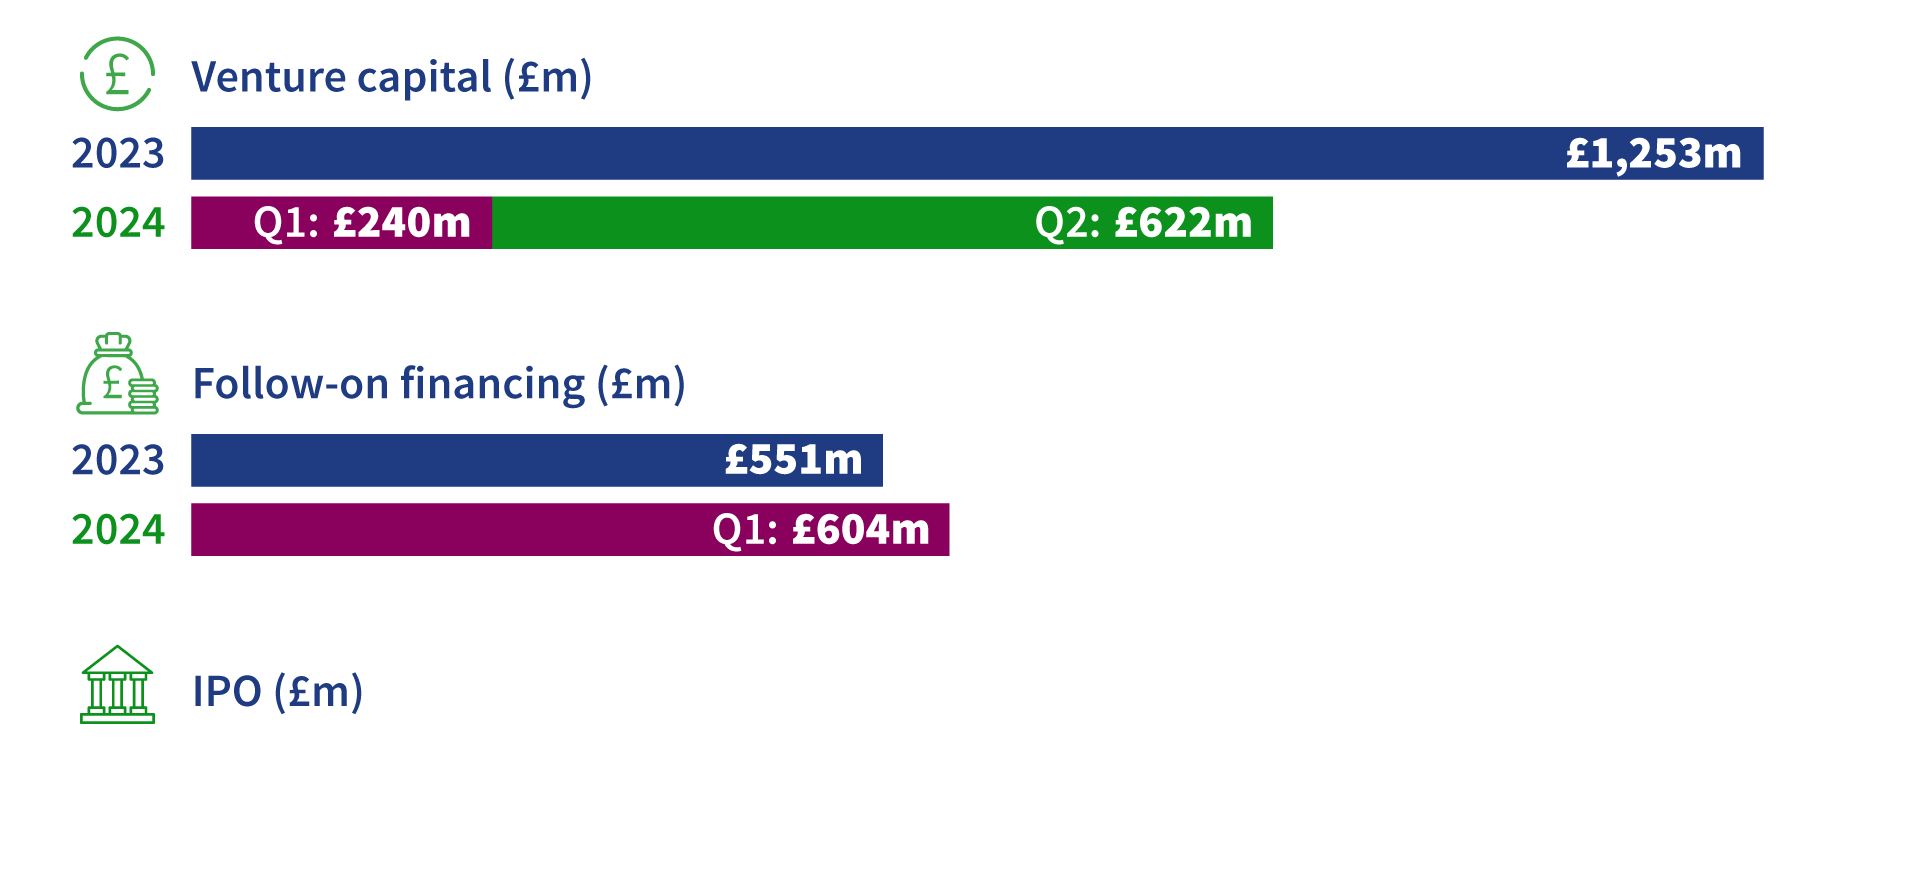
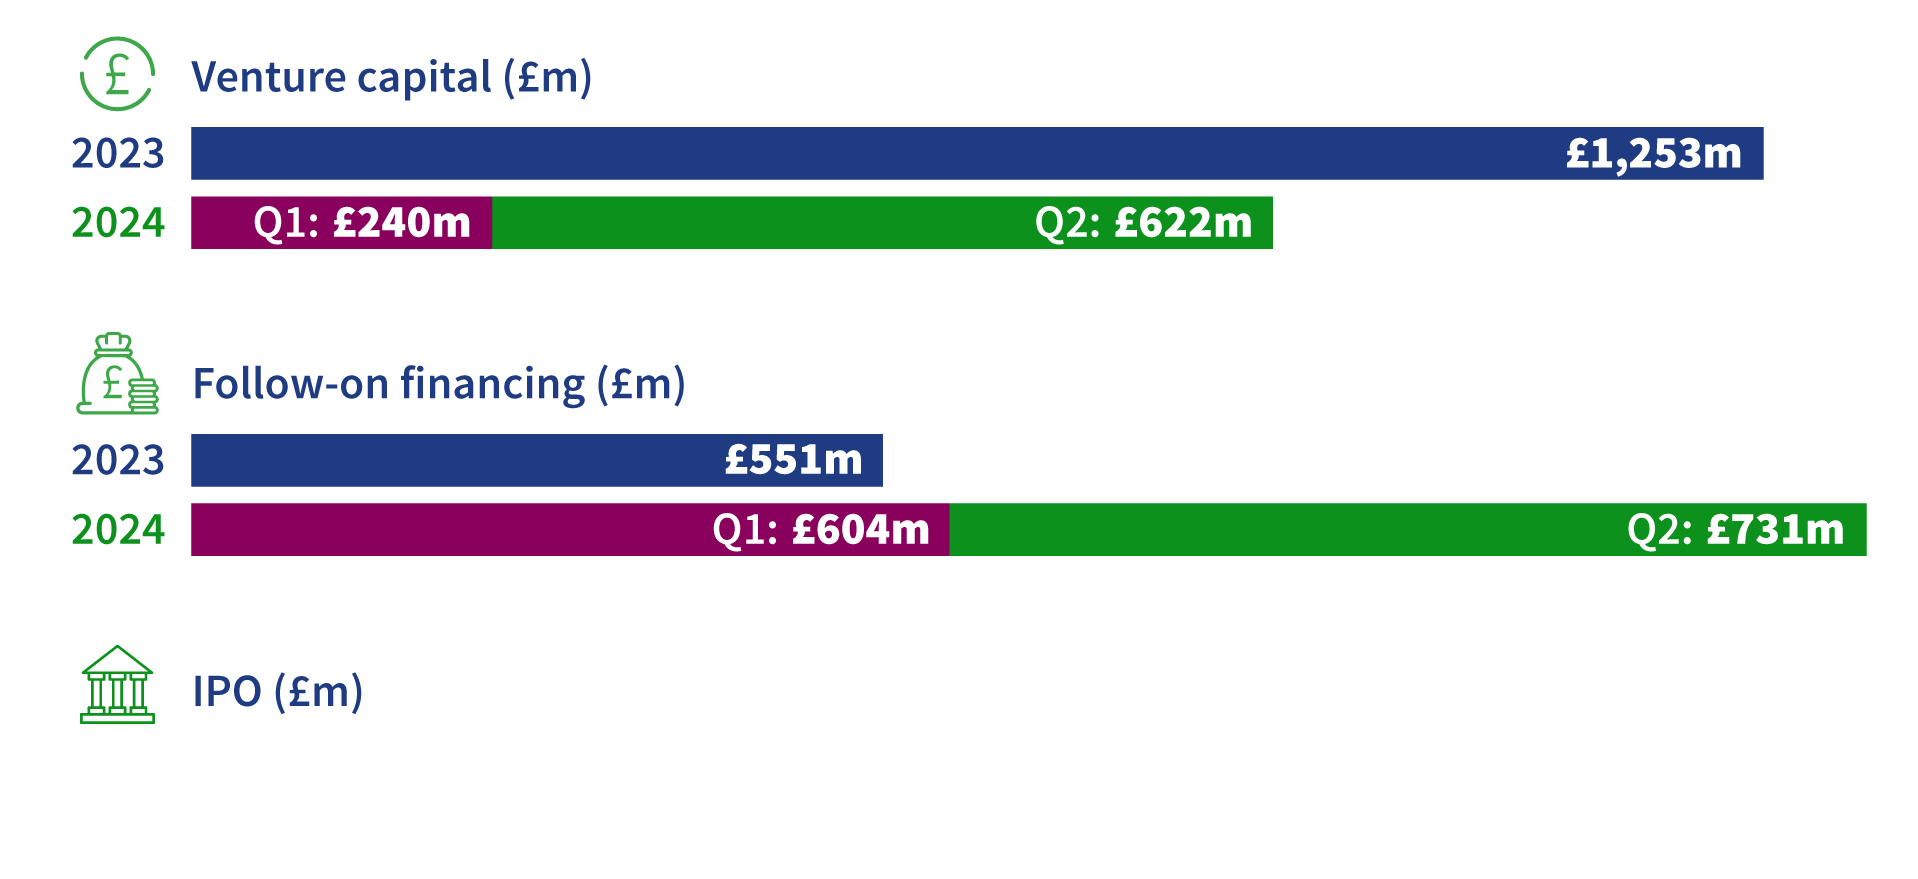
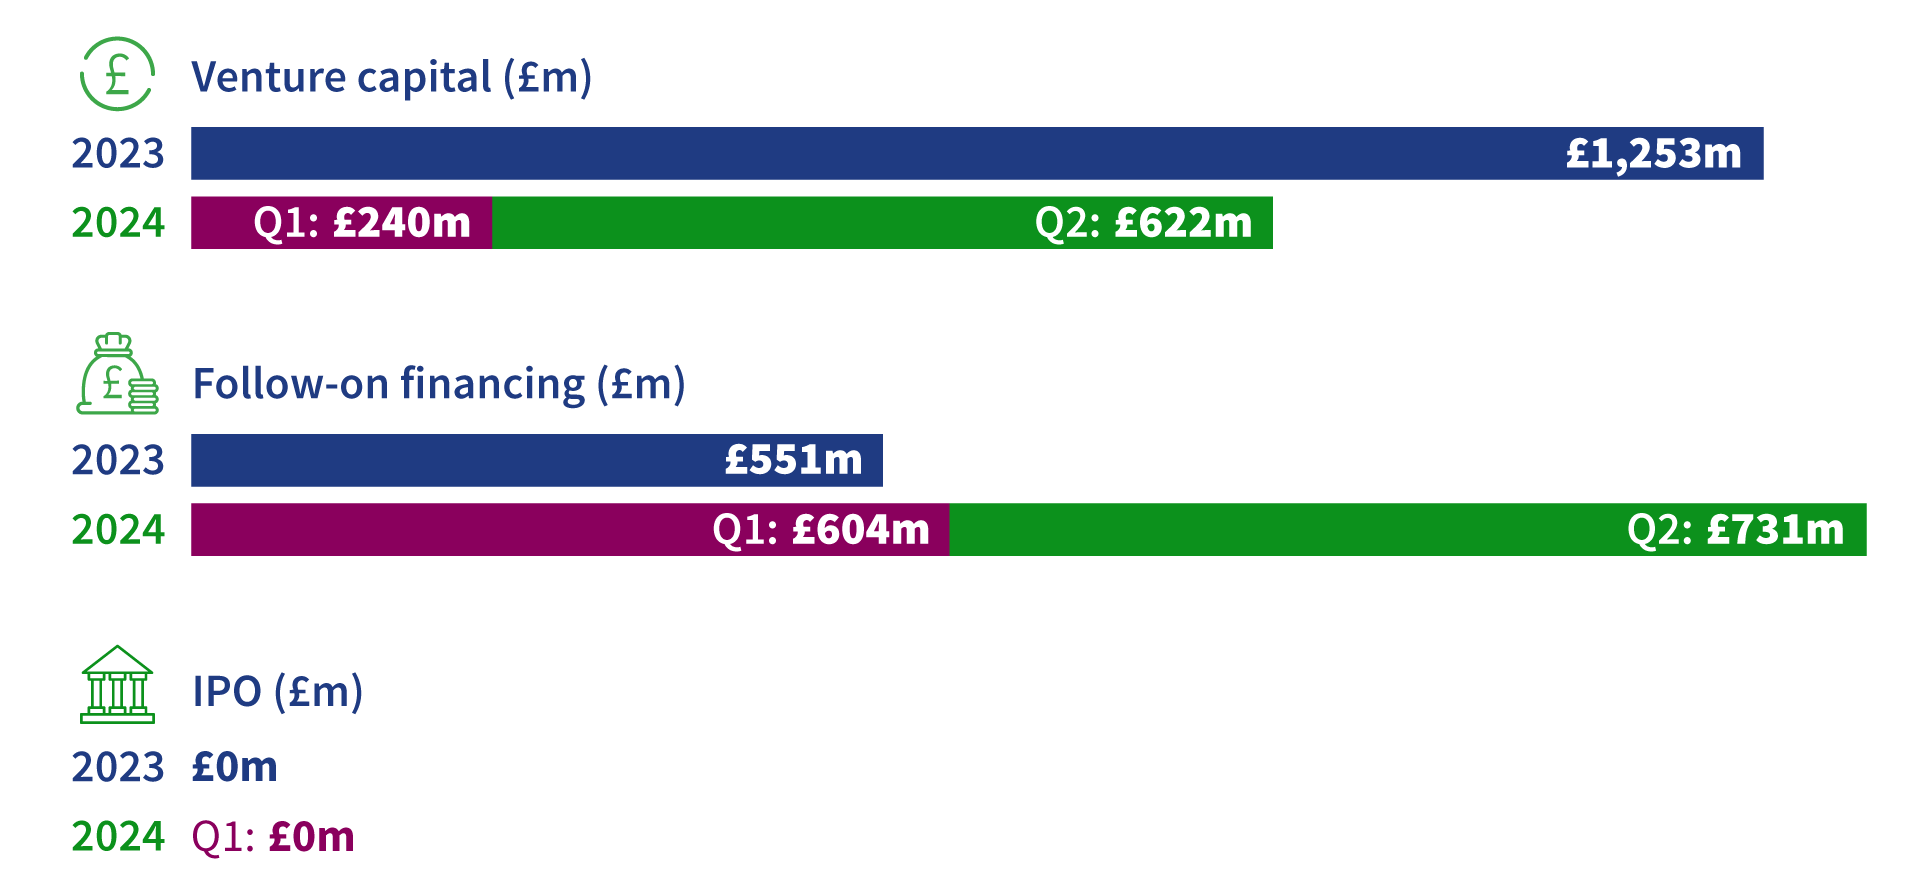
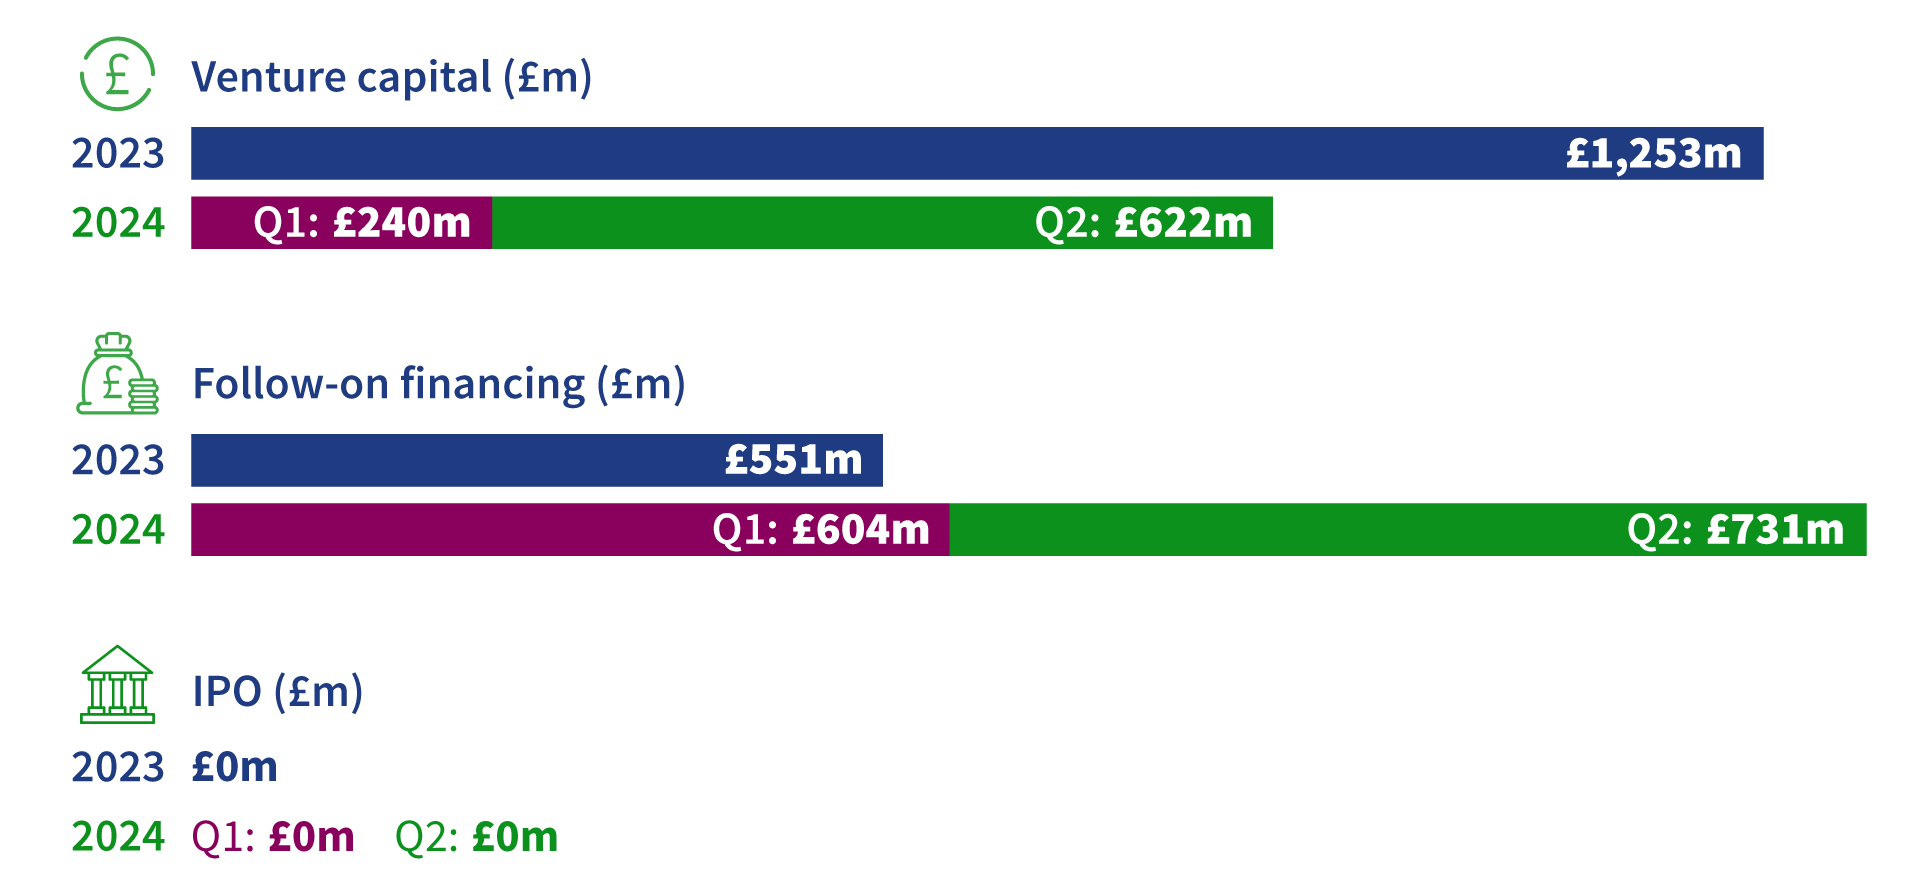
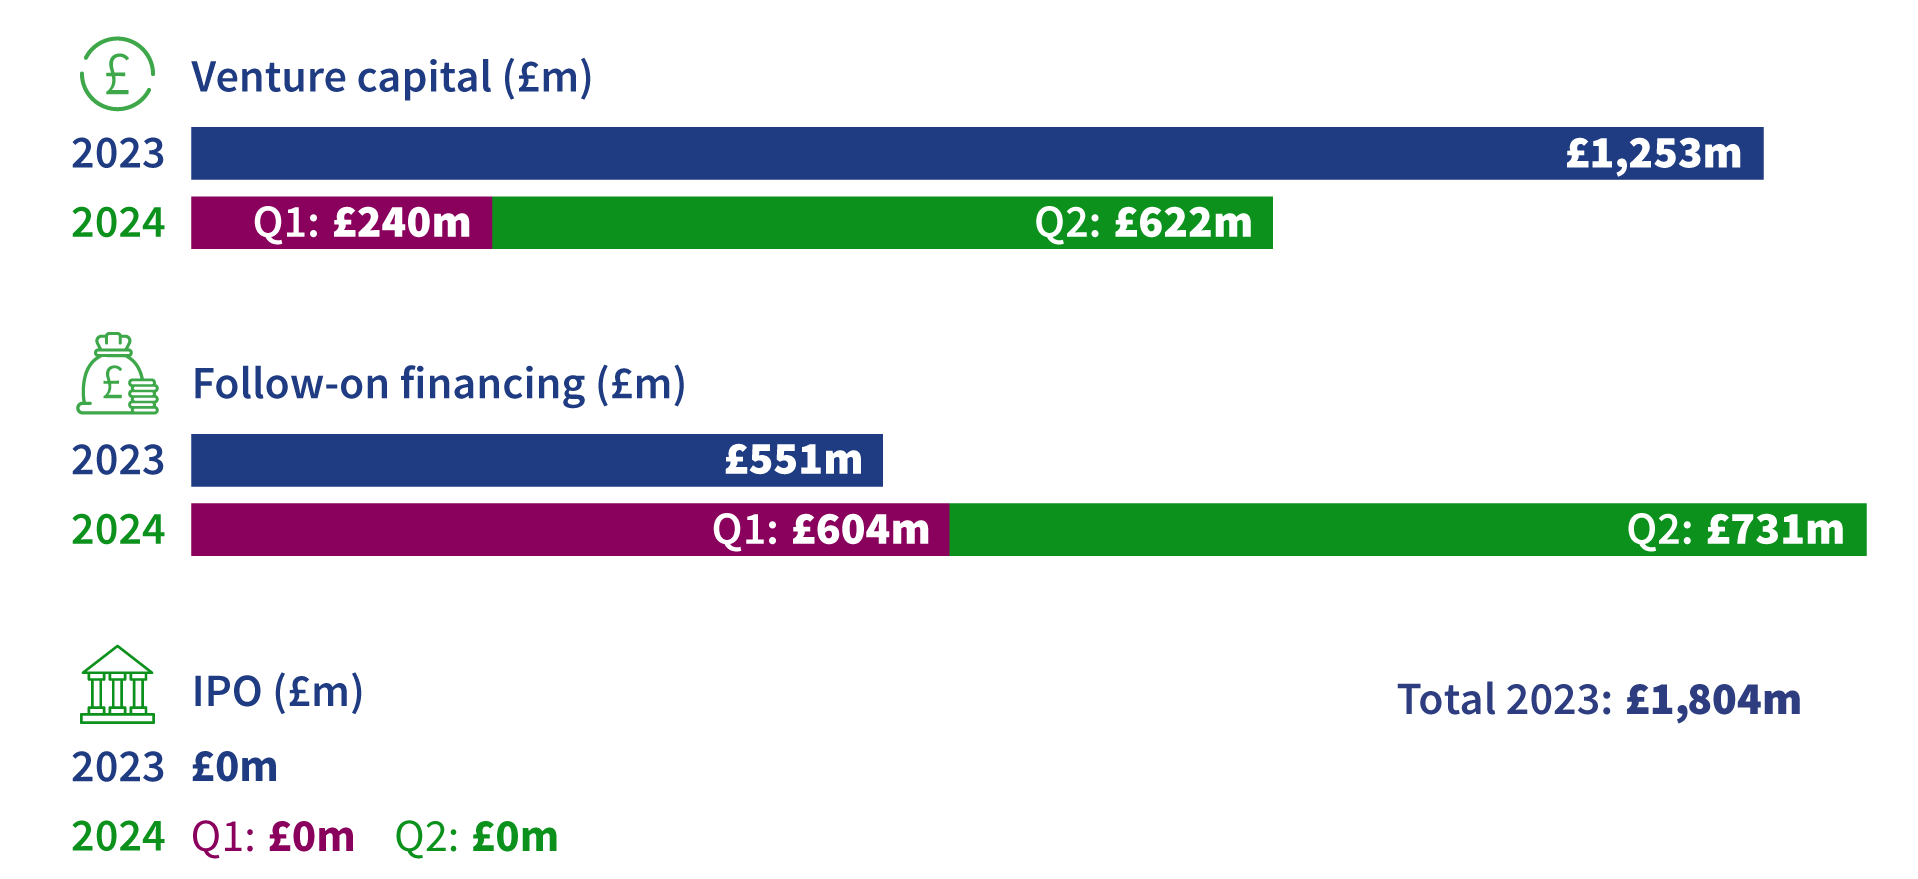
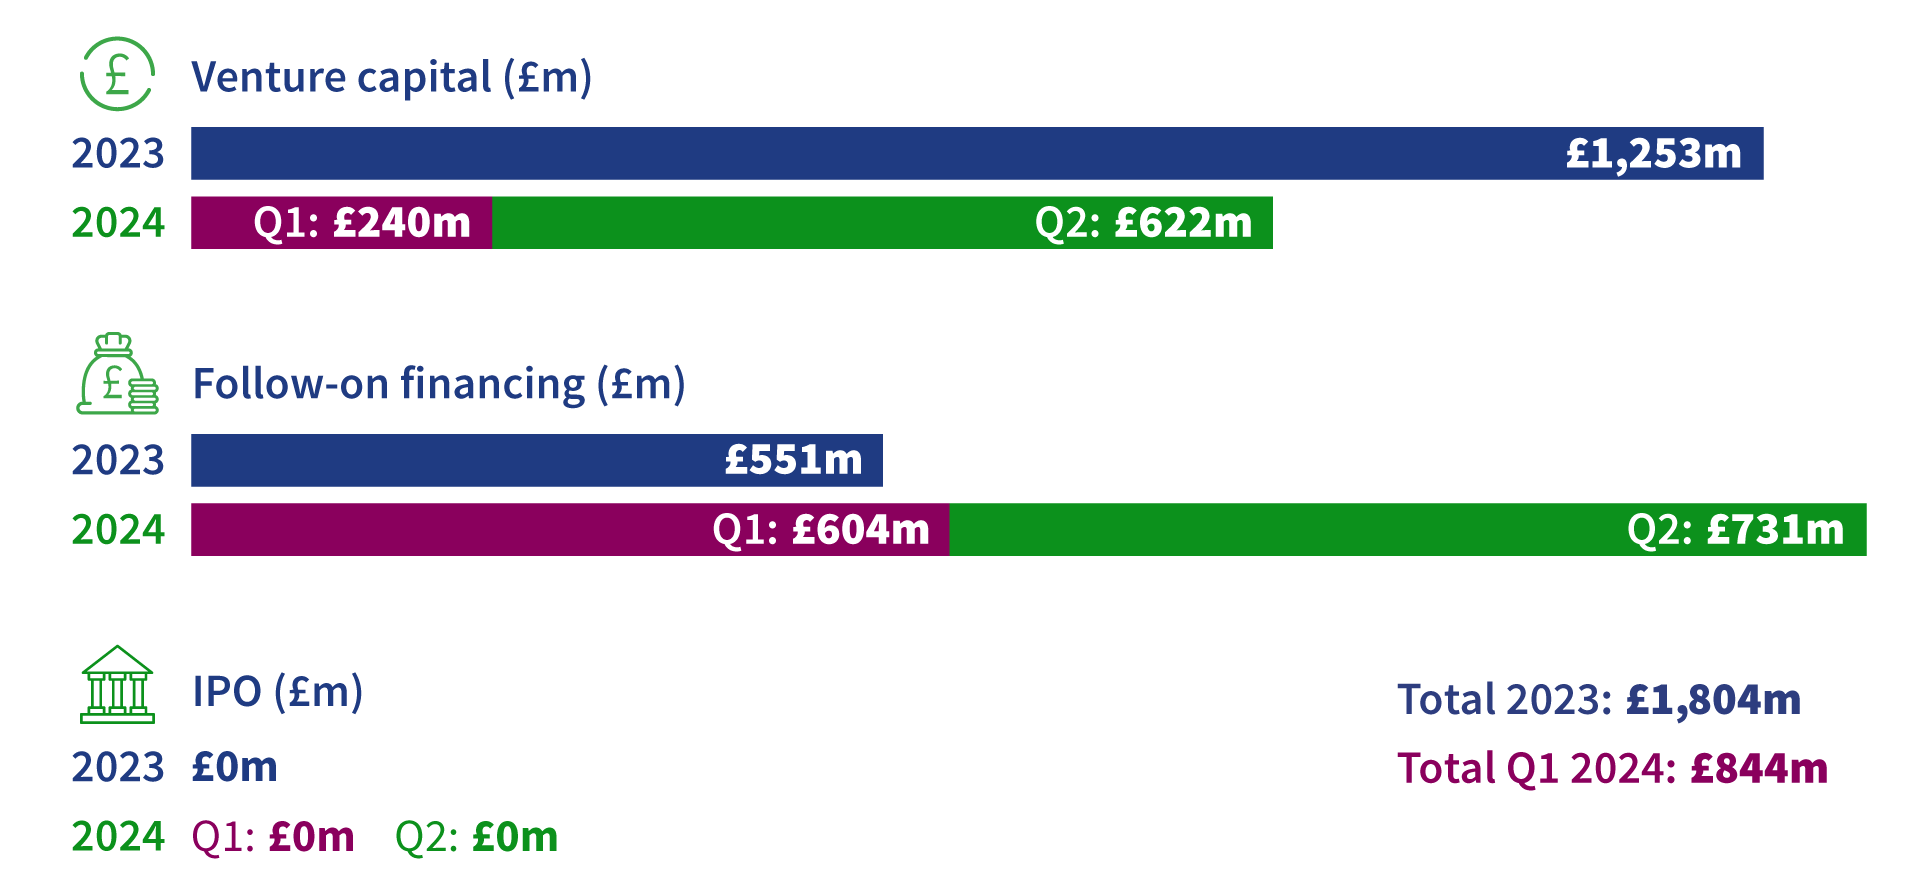
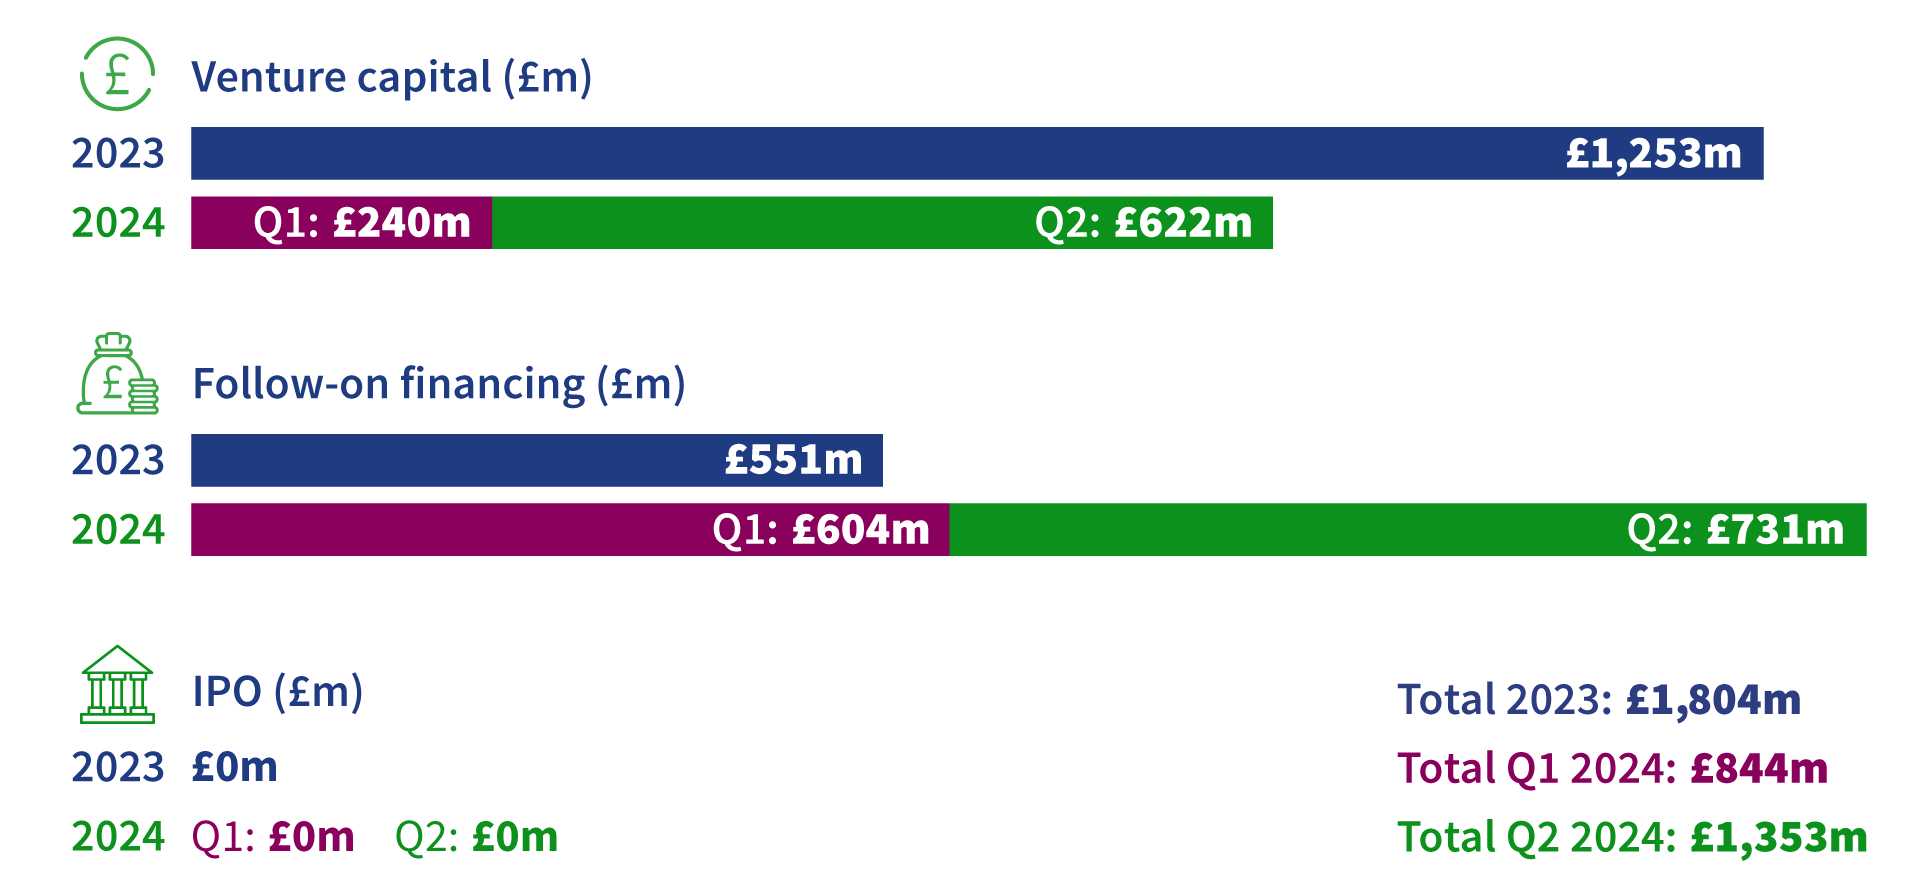
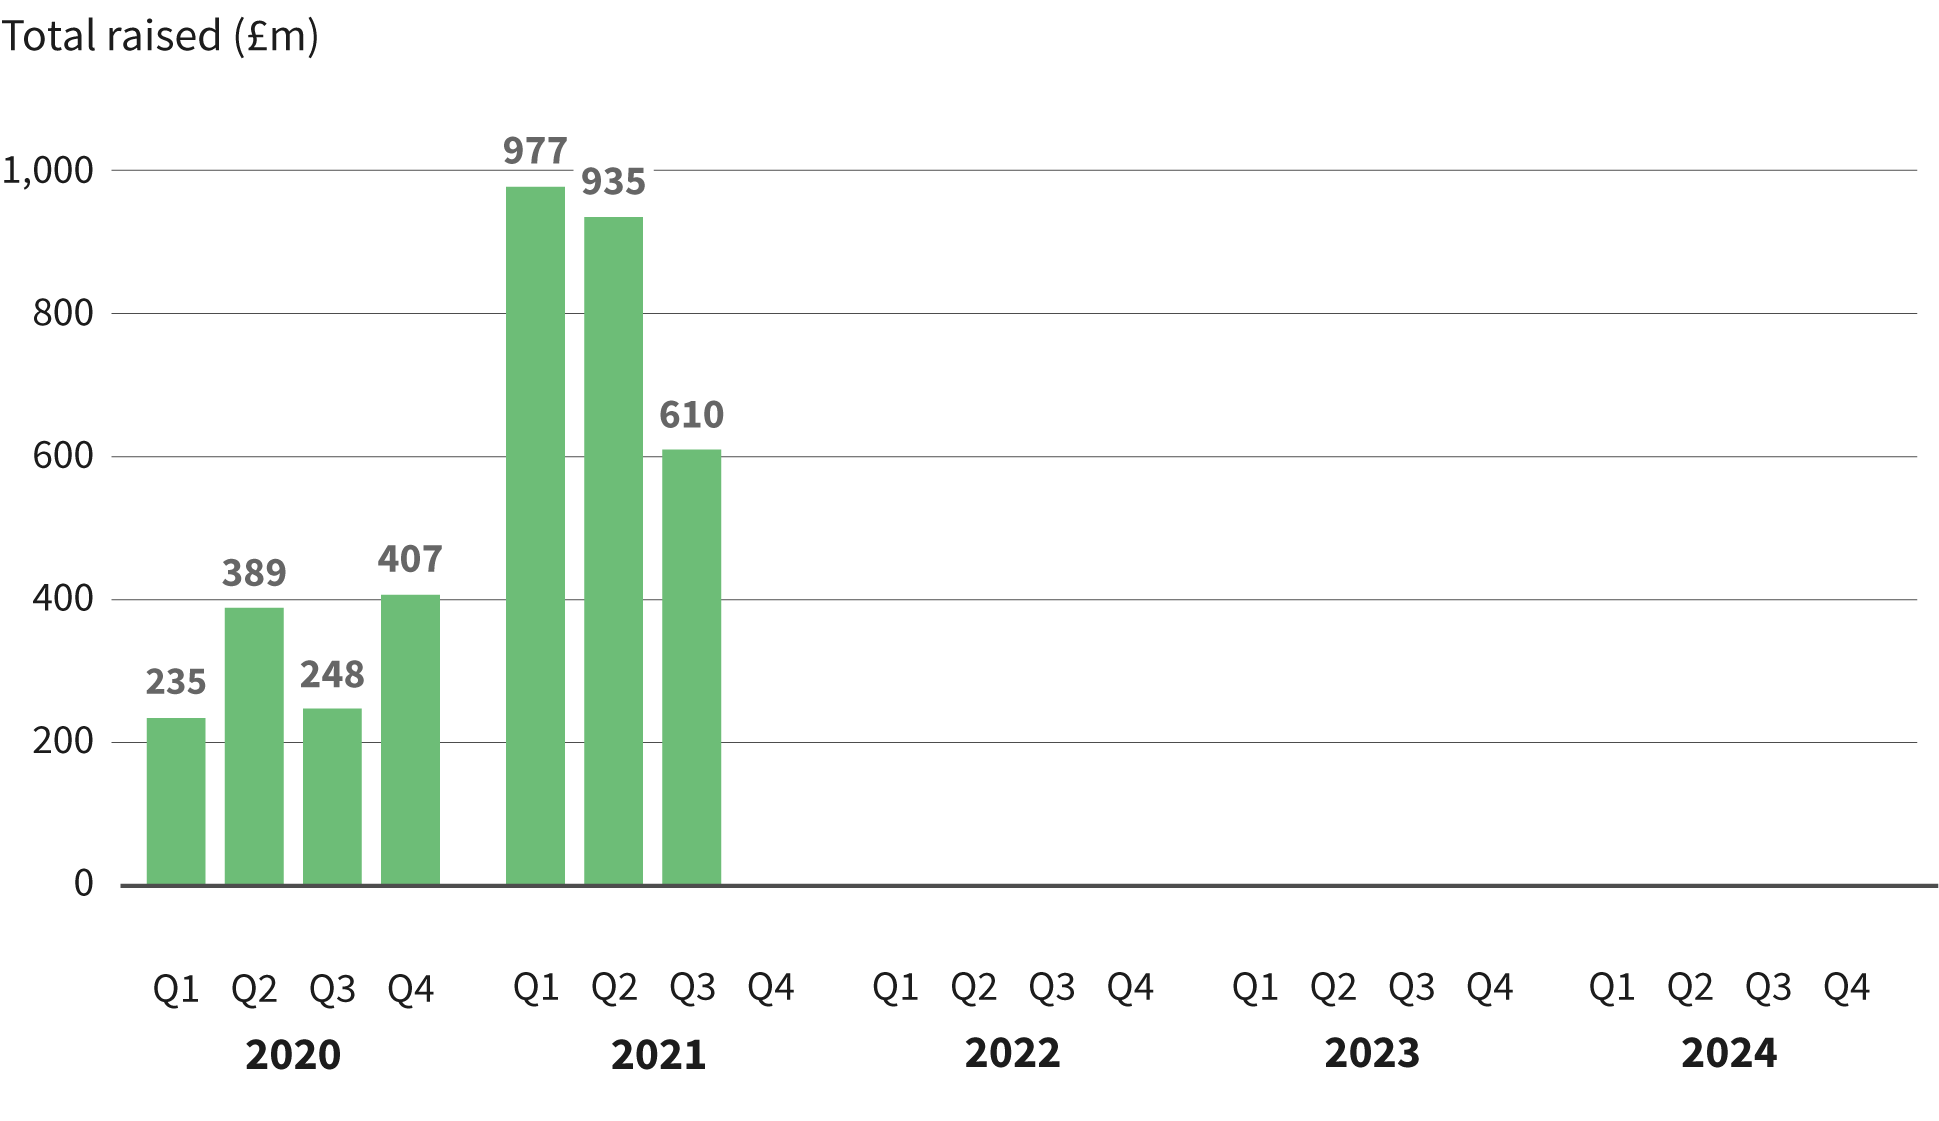
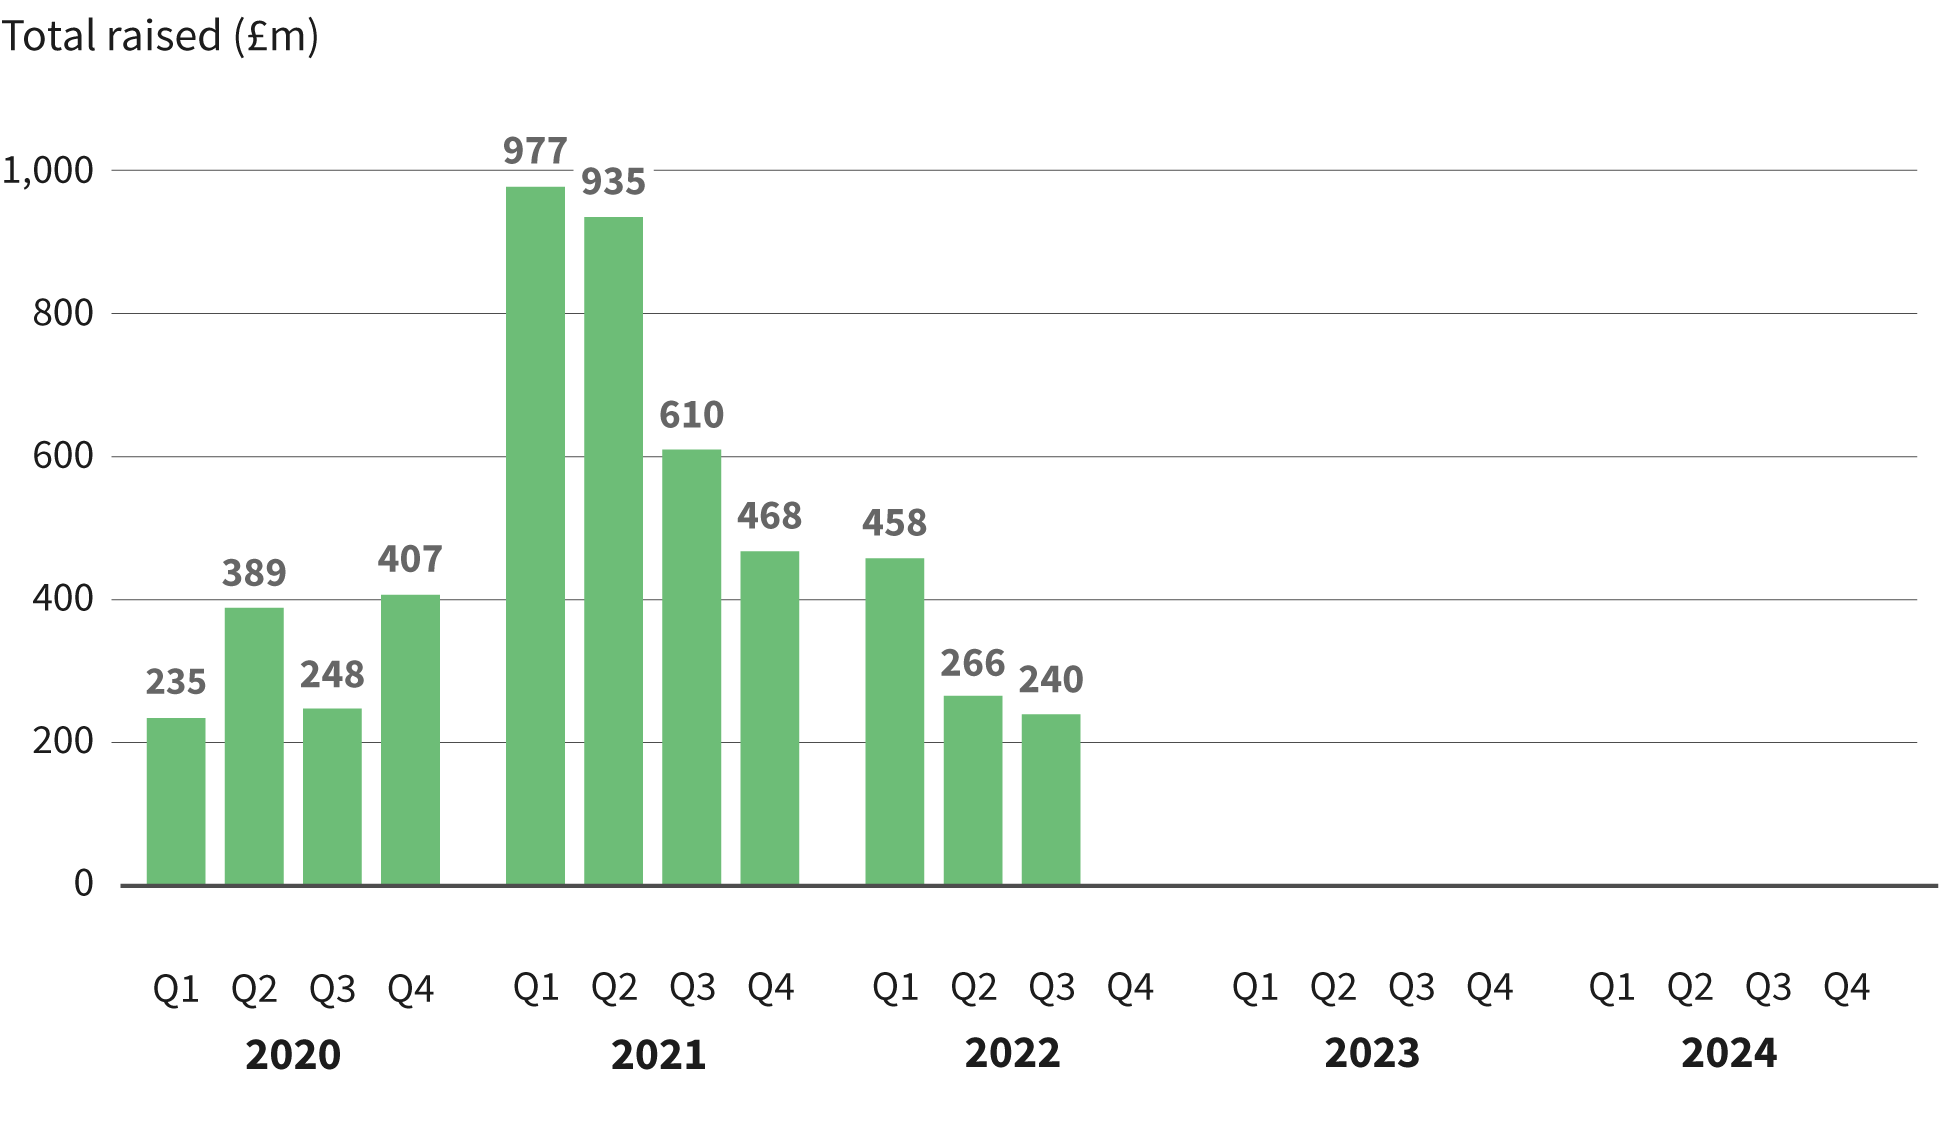
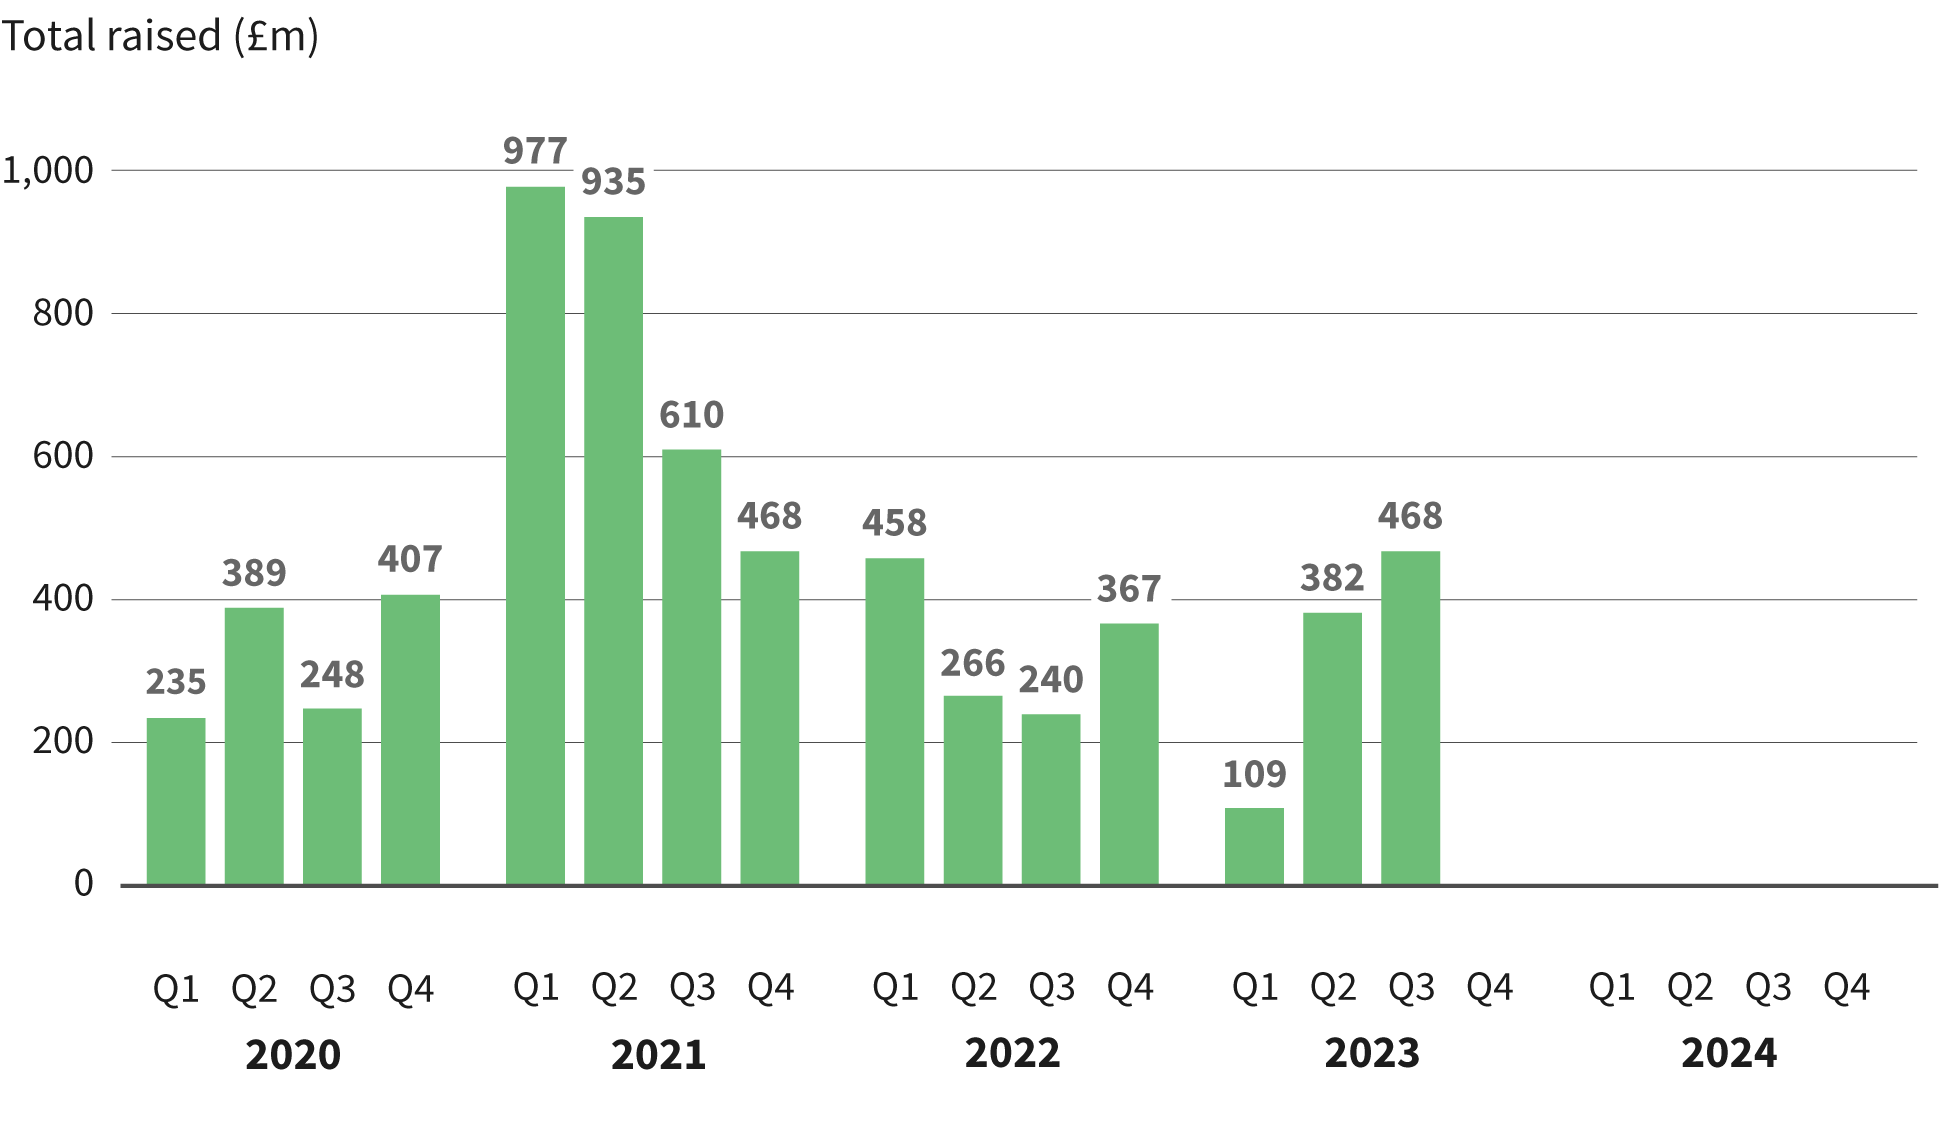
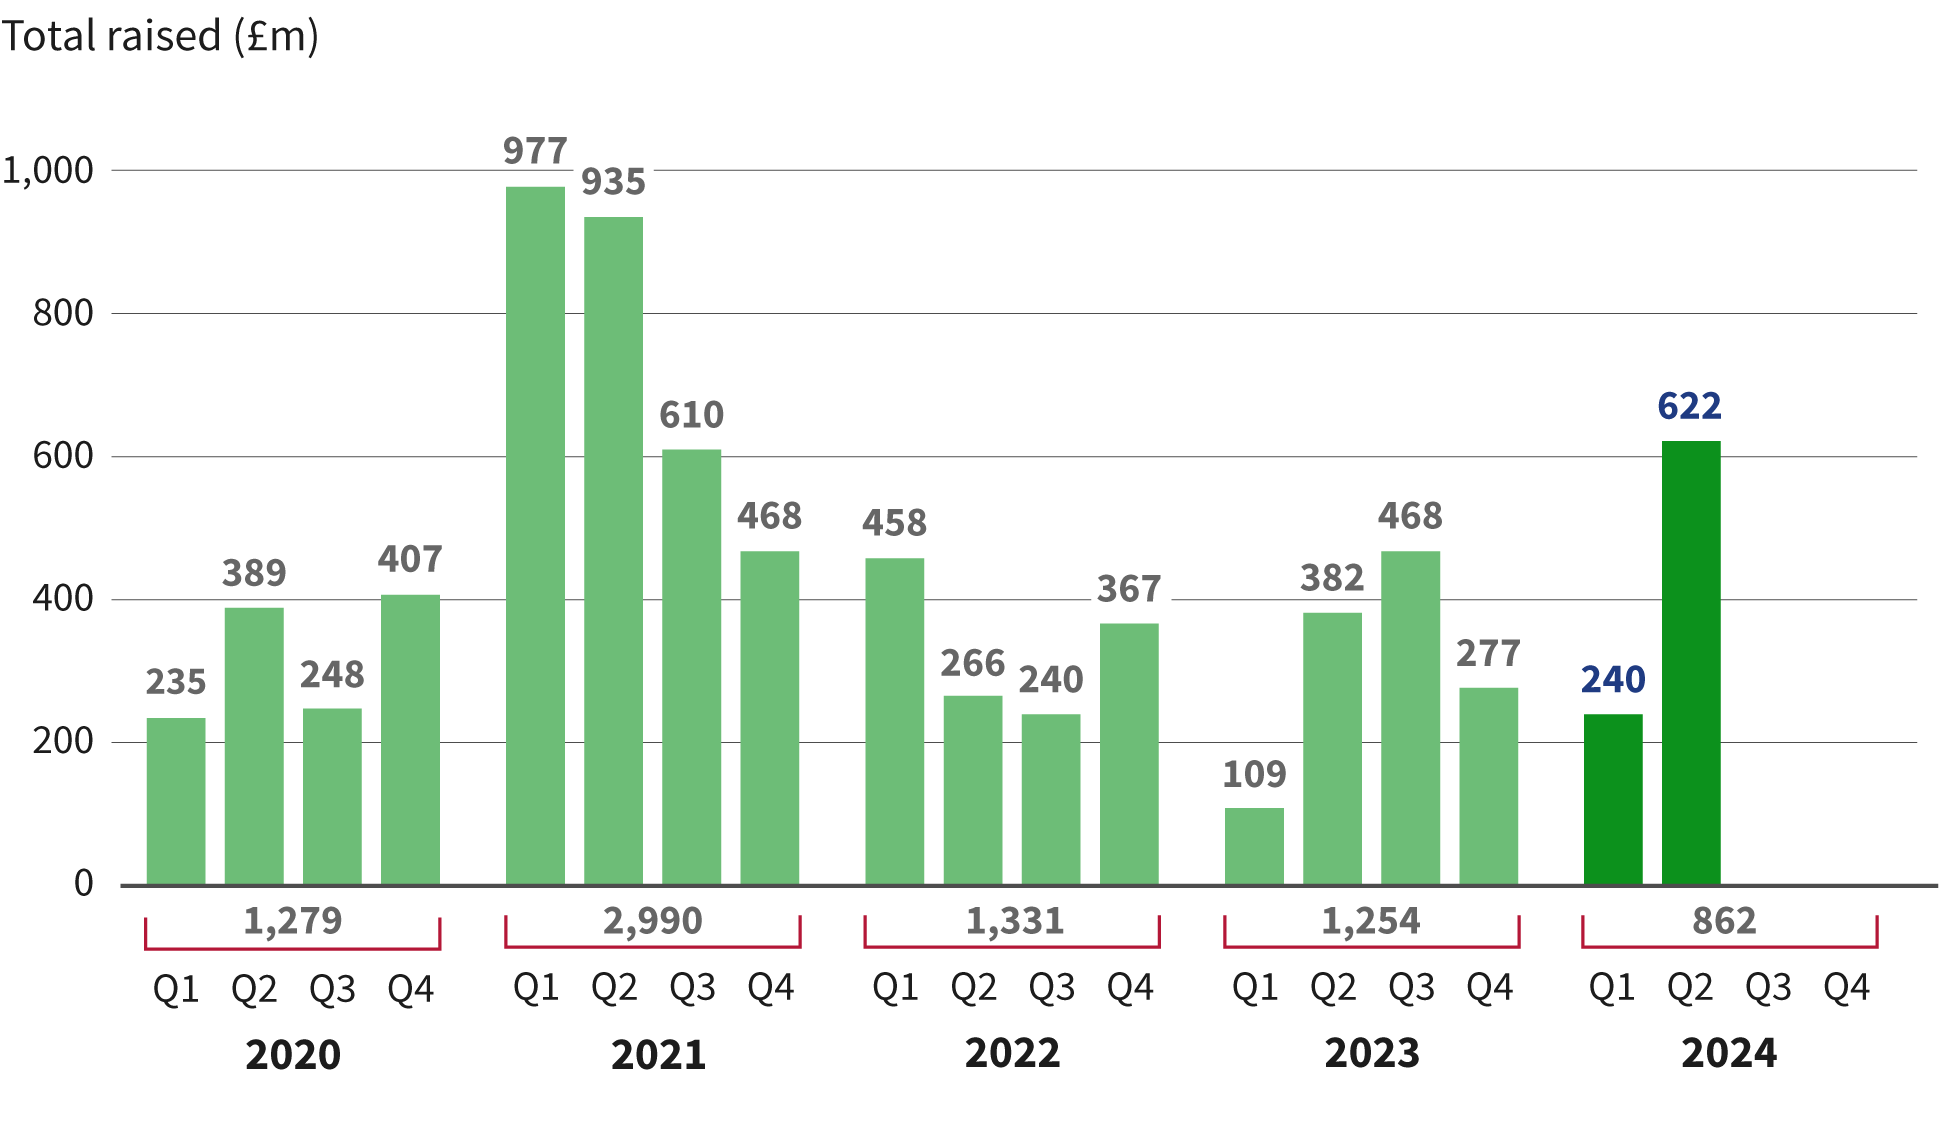
After a sluggish start to the year, the sector saw a significant rise in VC funding, with £564 million raised compared to Q1’s £240 million. This 135% increase marks a stark improvement and is the highest quarterly haul since Q3 of 2021.
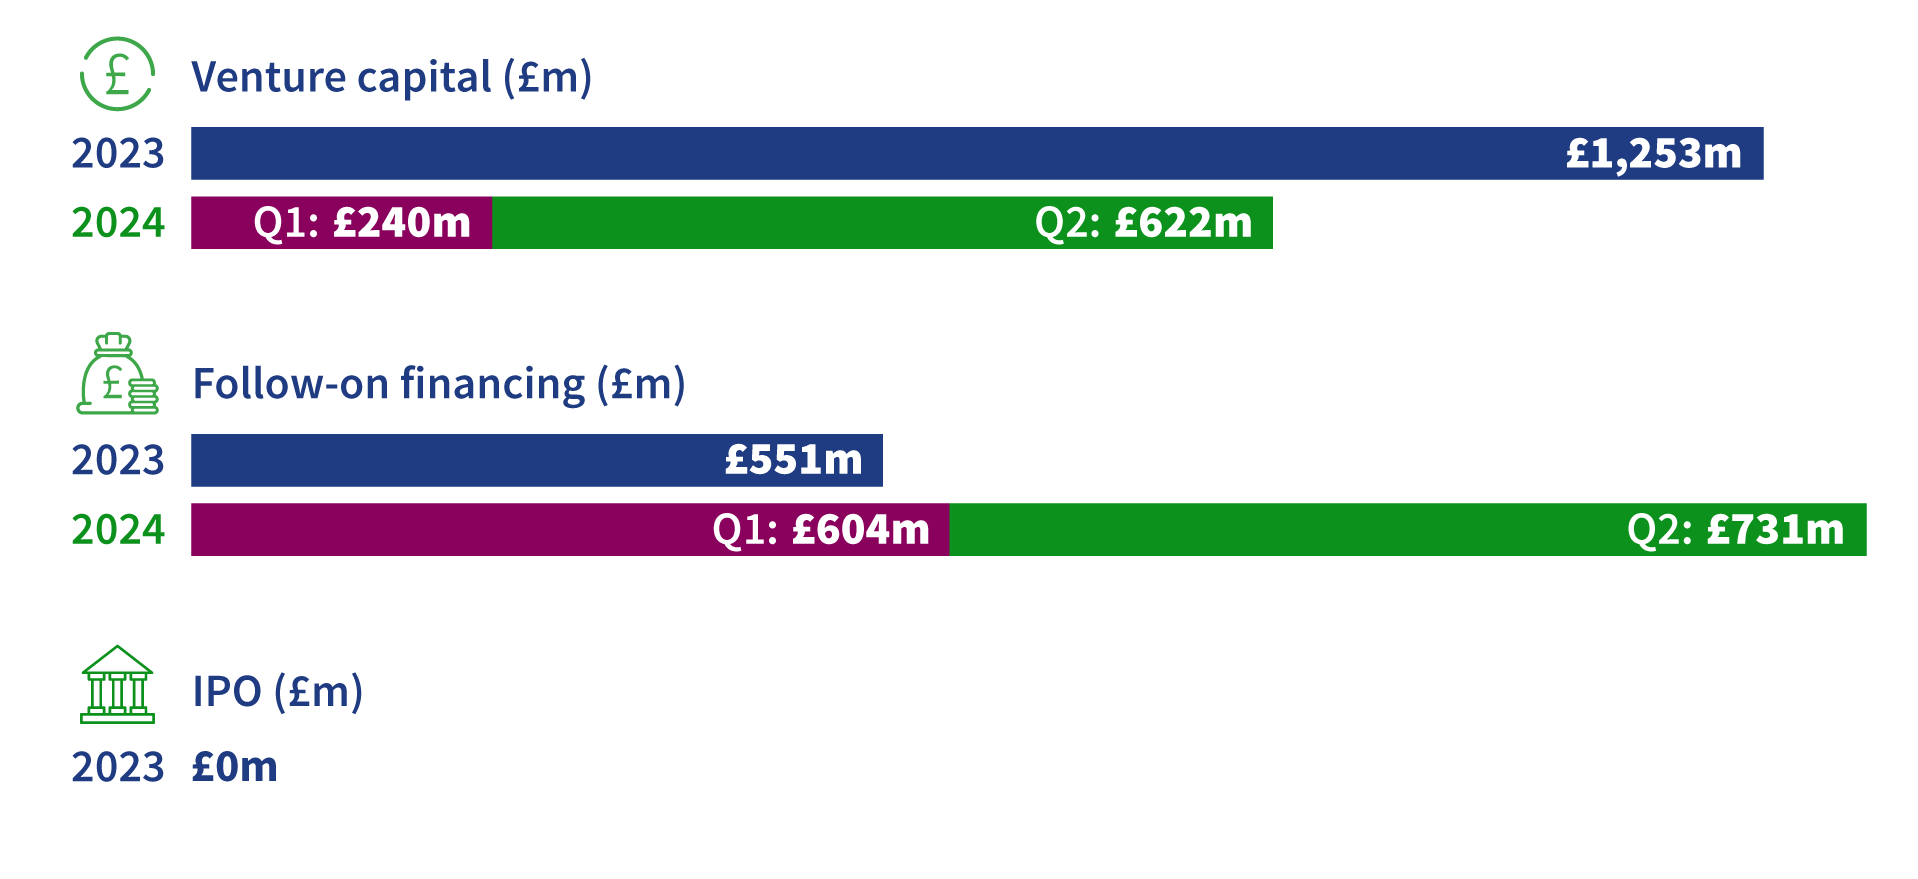
Public financing other than IPOs also showed a marked increase, with £577 million raised. However, the IPO market remained dormant, with no IPOs recorded in the first half of 2024. This highlights a cautious approach towards new market launch amidst the current economic climate.
In the second quarter of 2024, the UK biotech sector has demonstrated a clear path towards sustained growth, supported by large VC deals and significant public finance. Globally, the UK’s fundraising efforts remained competitive when compared to significant biotech hubs in the US and Europe.
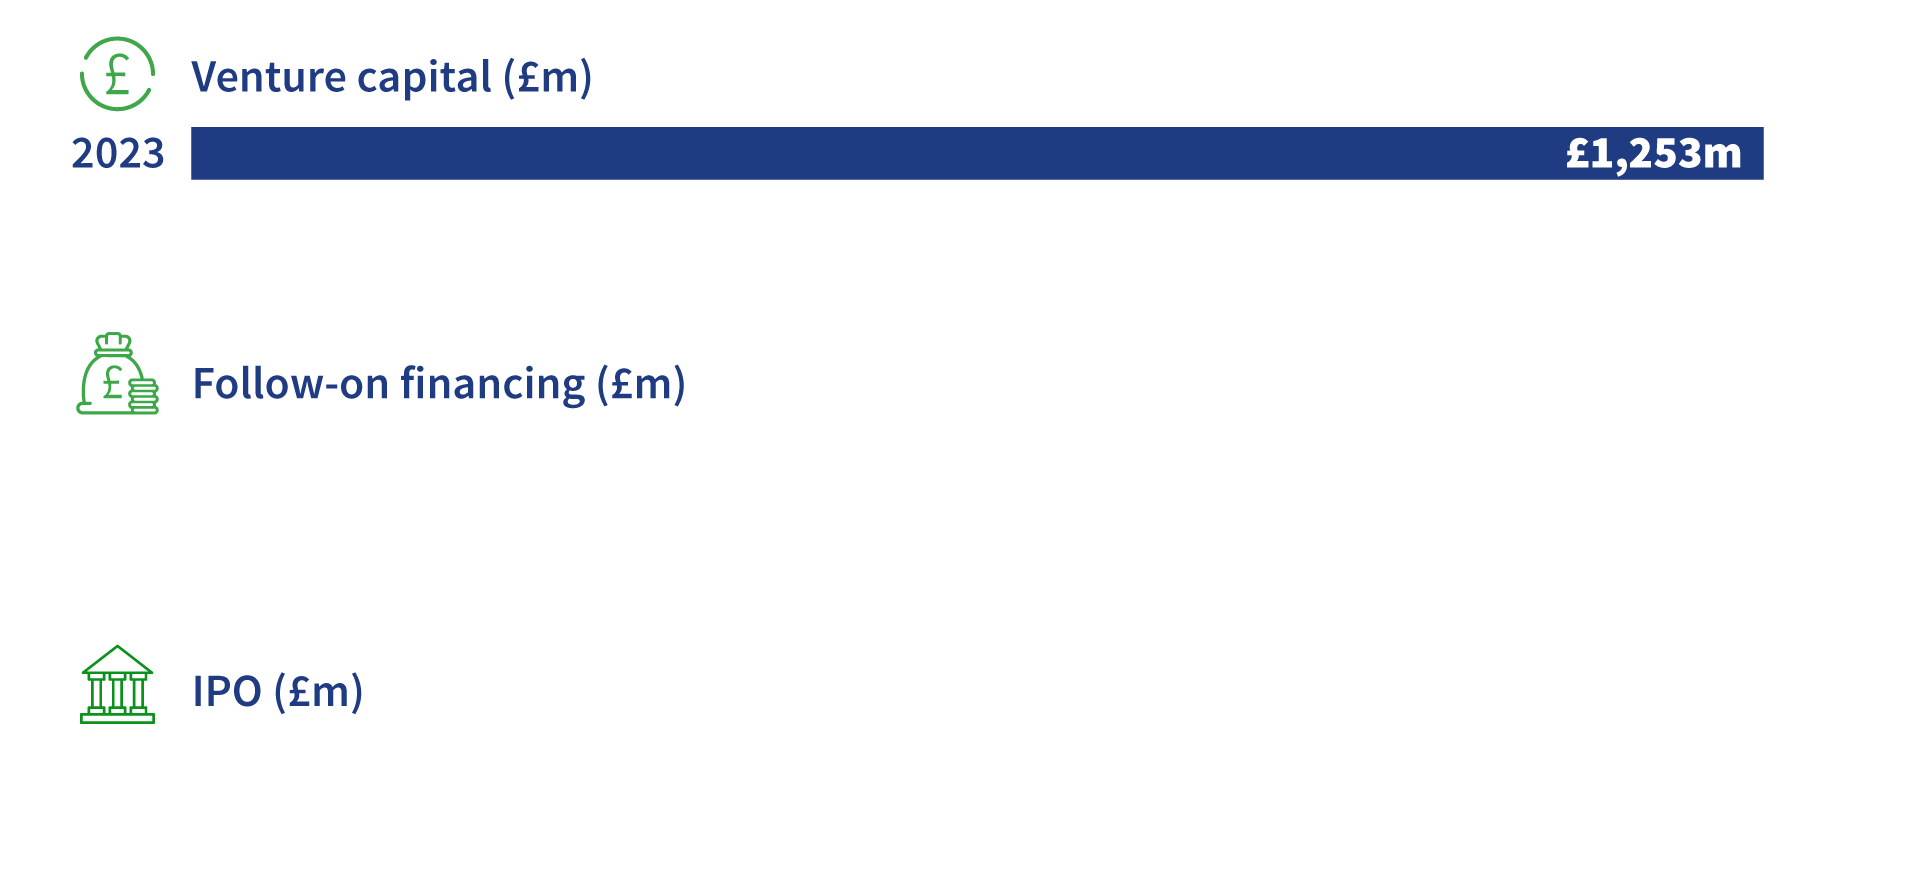
2023 and 2024 Q2 figures at a glance

Steve Bates OBE
CEO, BIA
This quarter has marked a significant step forward for UK biotech, with remarkable growth in venture capital funding and a notable increase in follow-on financings.
Our sector’s performance will be bolstered by the new Labour government’s growth mission that has focused on unlocking new sources of capital from British pension funds. This initiative will create a fertile environment for innovation and investment. As we continue to build on these achievements, the outlook for UK biotech is very promising. With growing investor confidence and a robust pipeline of advancements, we are well-positioned to excel in the global biotech landscape.
 Venture capital
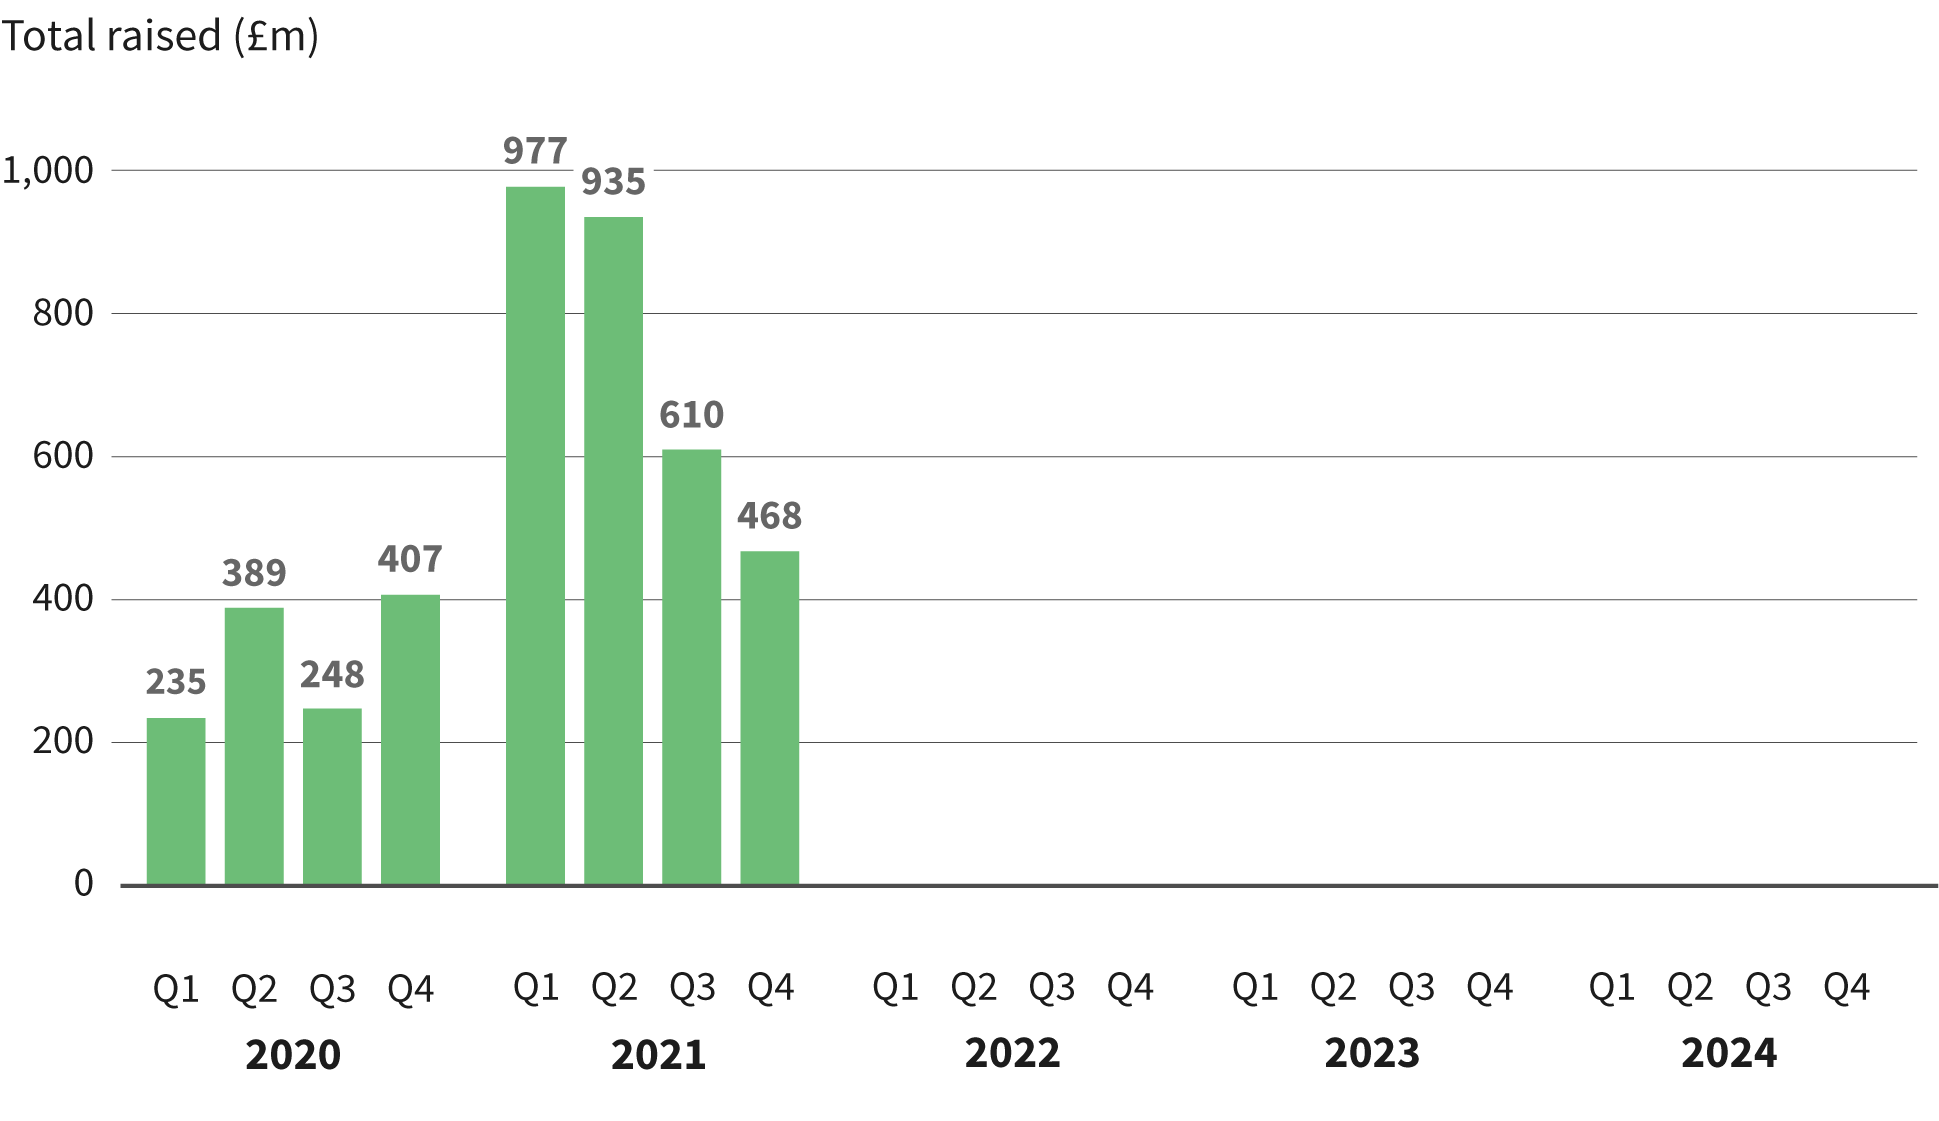
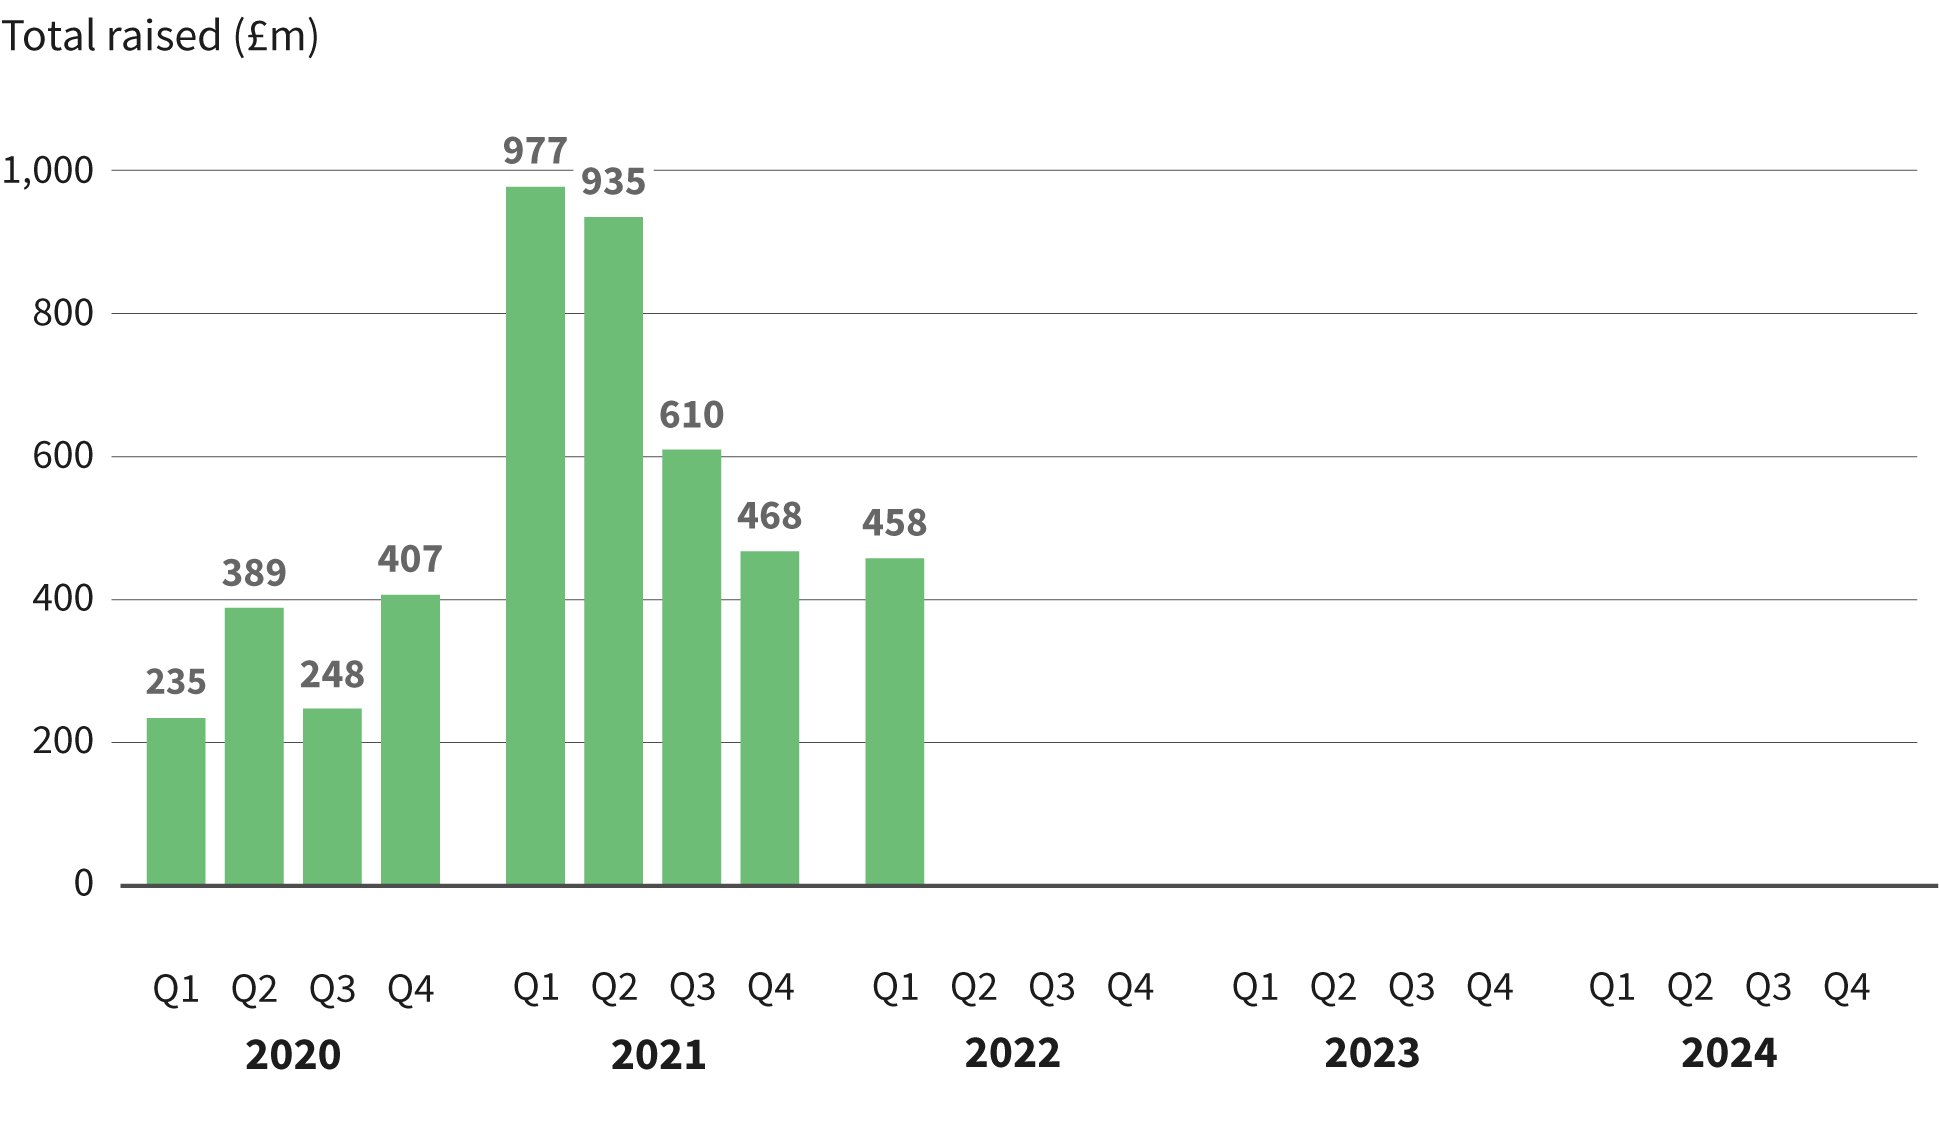
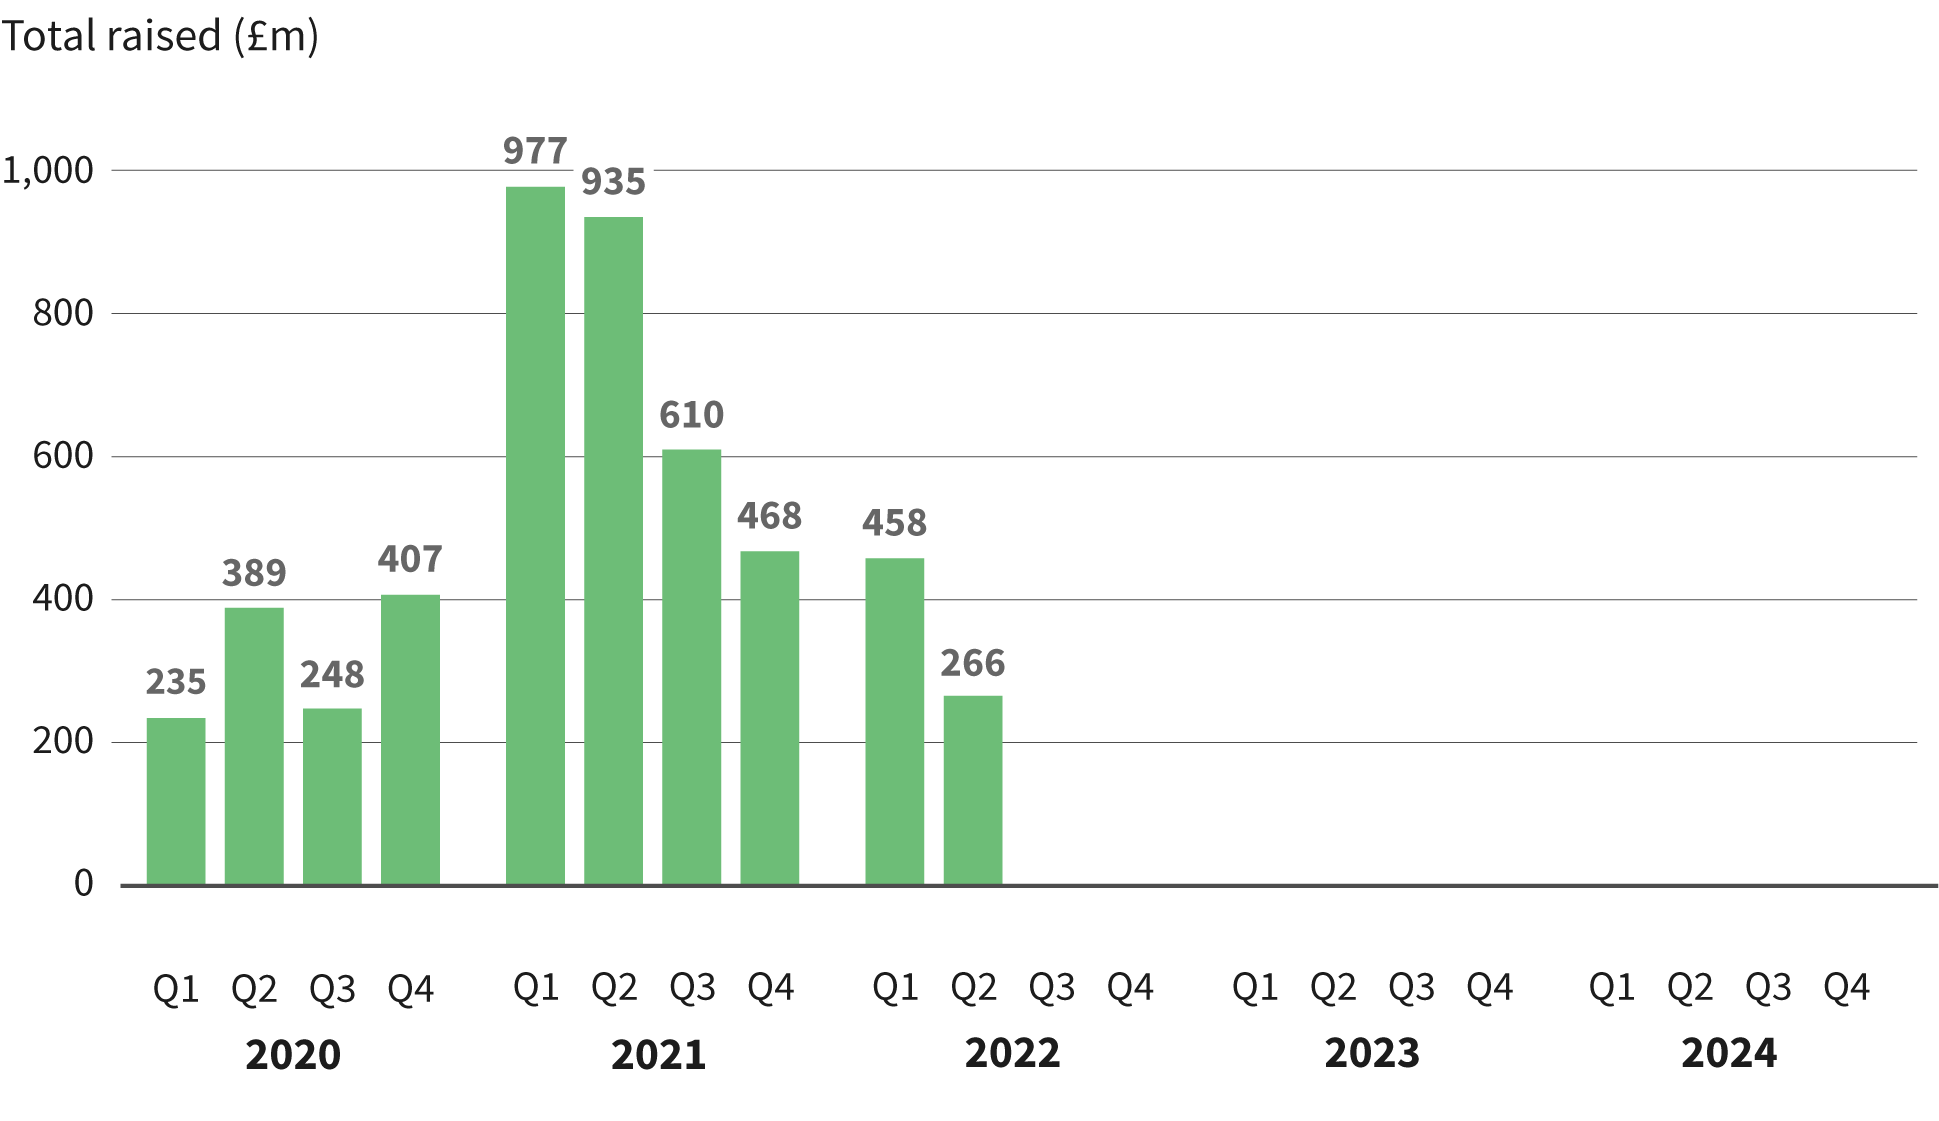
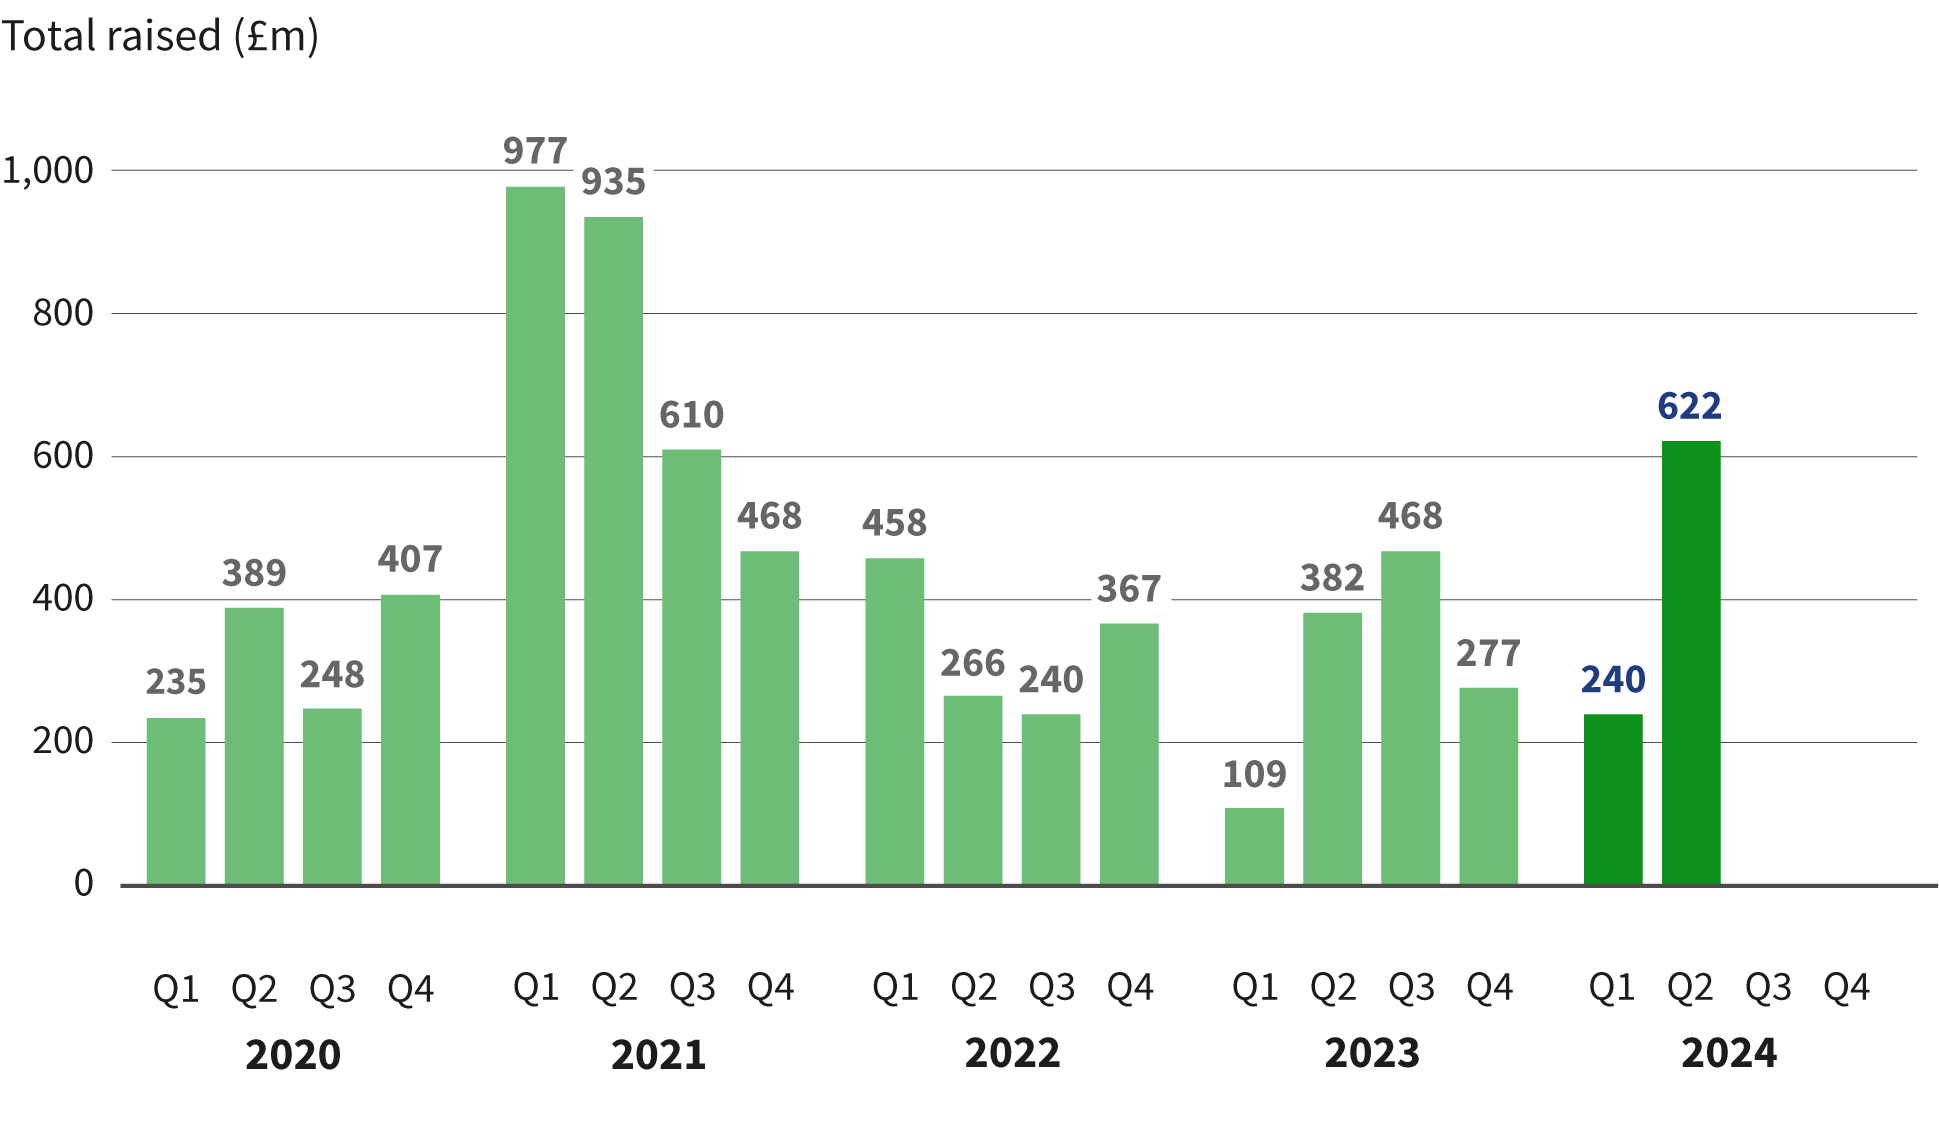
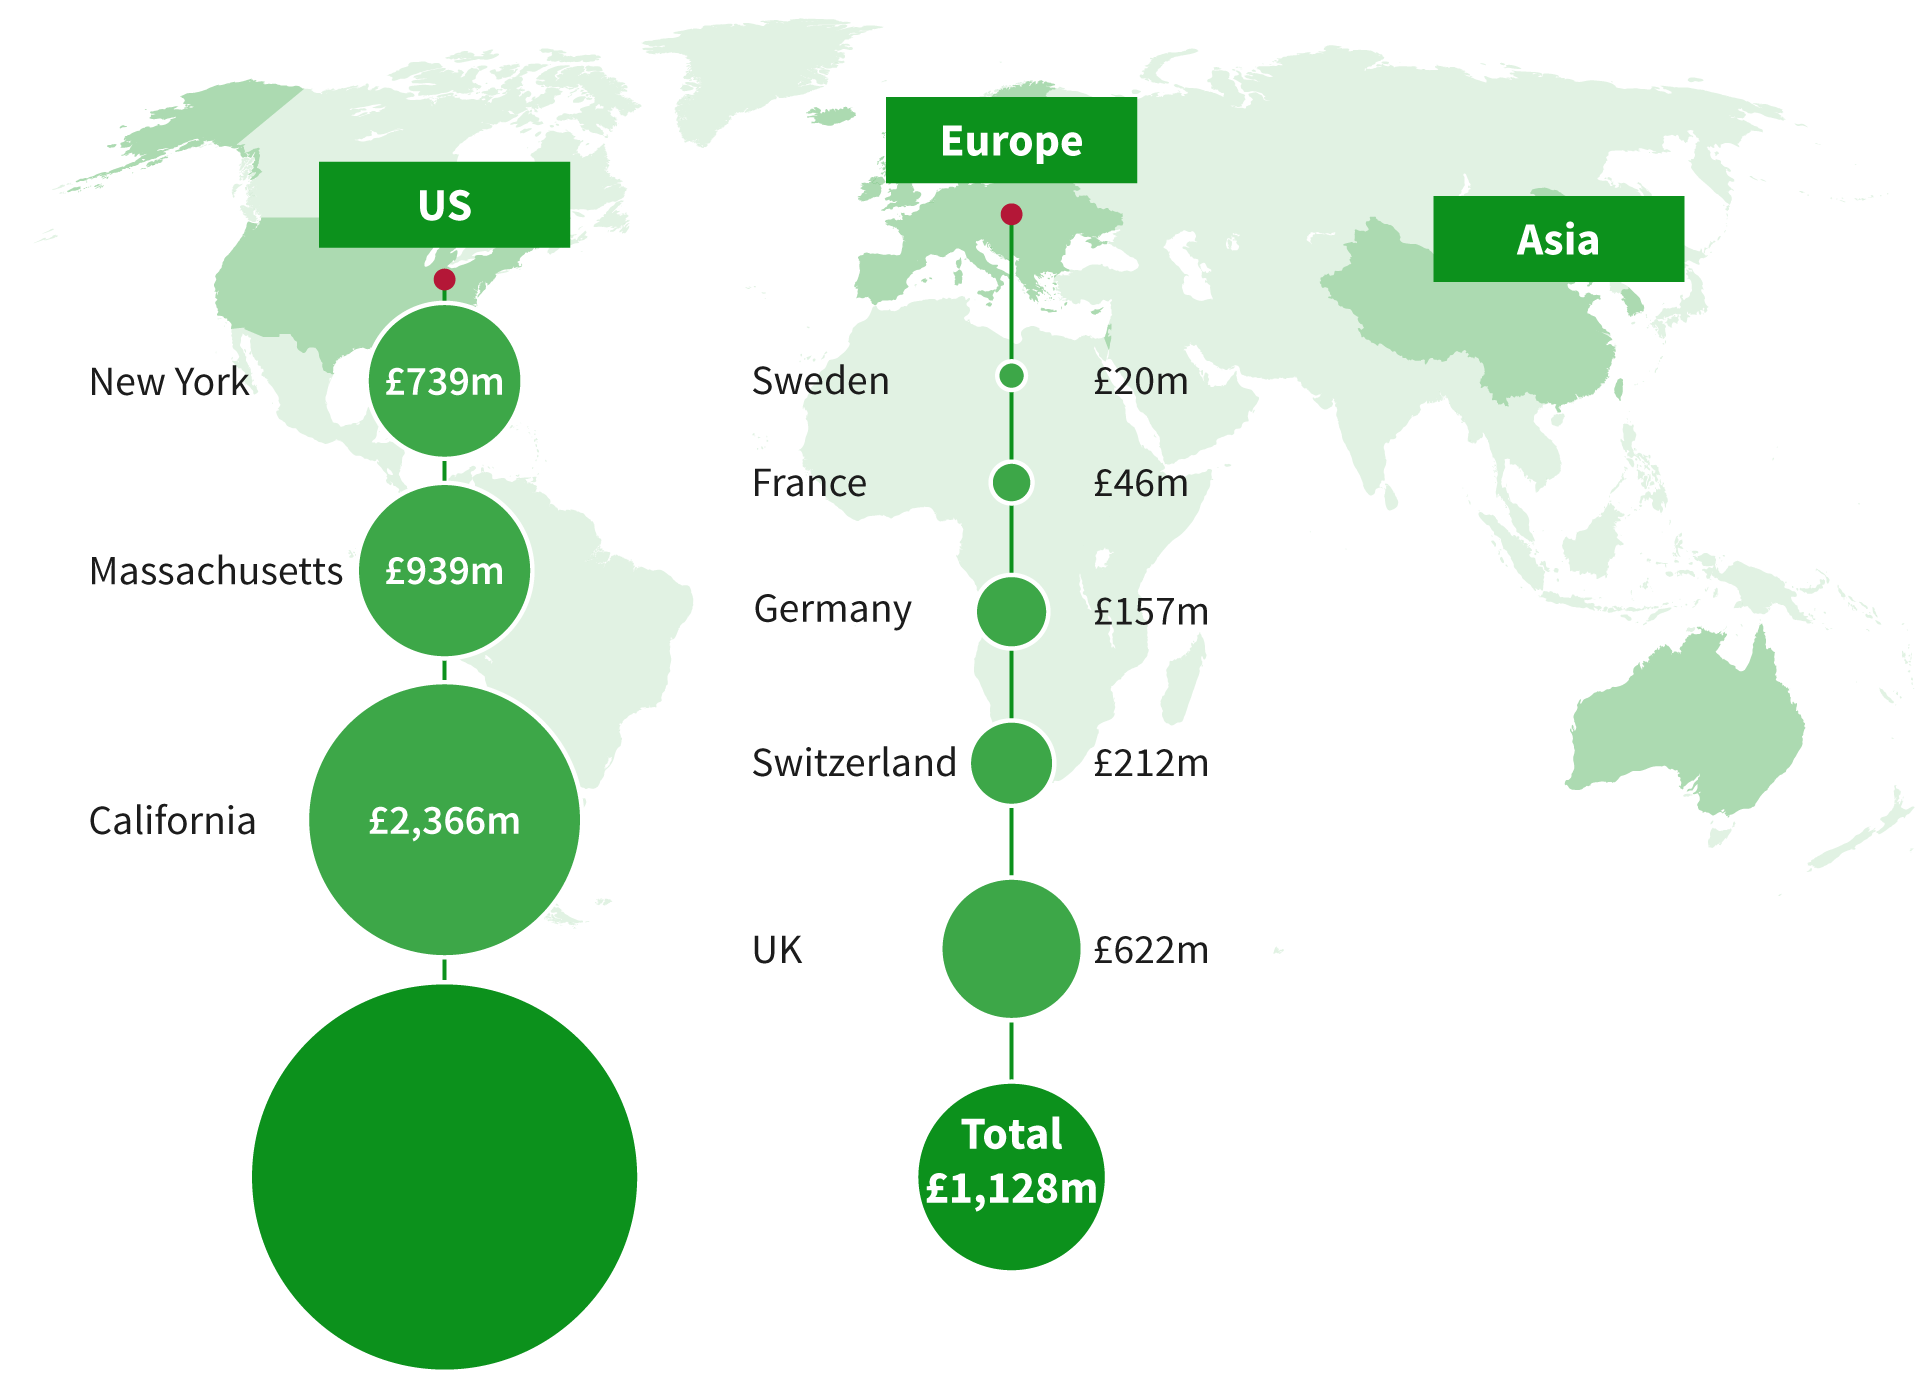
In the second quarter of 2024, UK biotech companies secured a total of £622 million in venture capital funding, marking a significant 259% increase from the previous quarter and a 48% rise compared to the same period last year.
This funding was spread across 38 deals, averaging £15 million per deal. The completion of 15 seed deals in the quarter compares very well against the 28 completed for the whole of 2023 and 20 in 2022. The mean seed deal size was also up slightly compared to past years, signalling renewed appetite for early-stage deals.
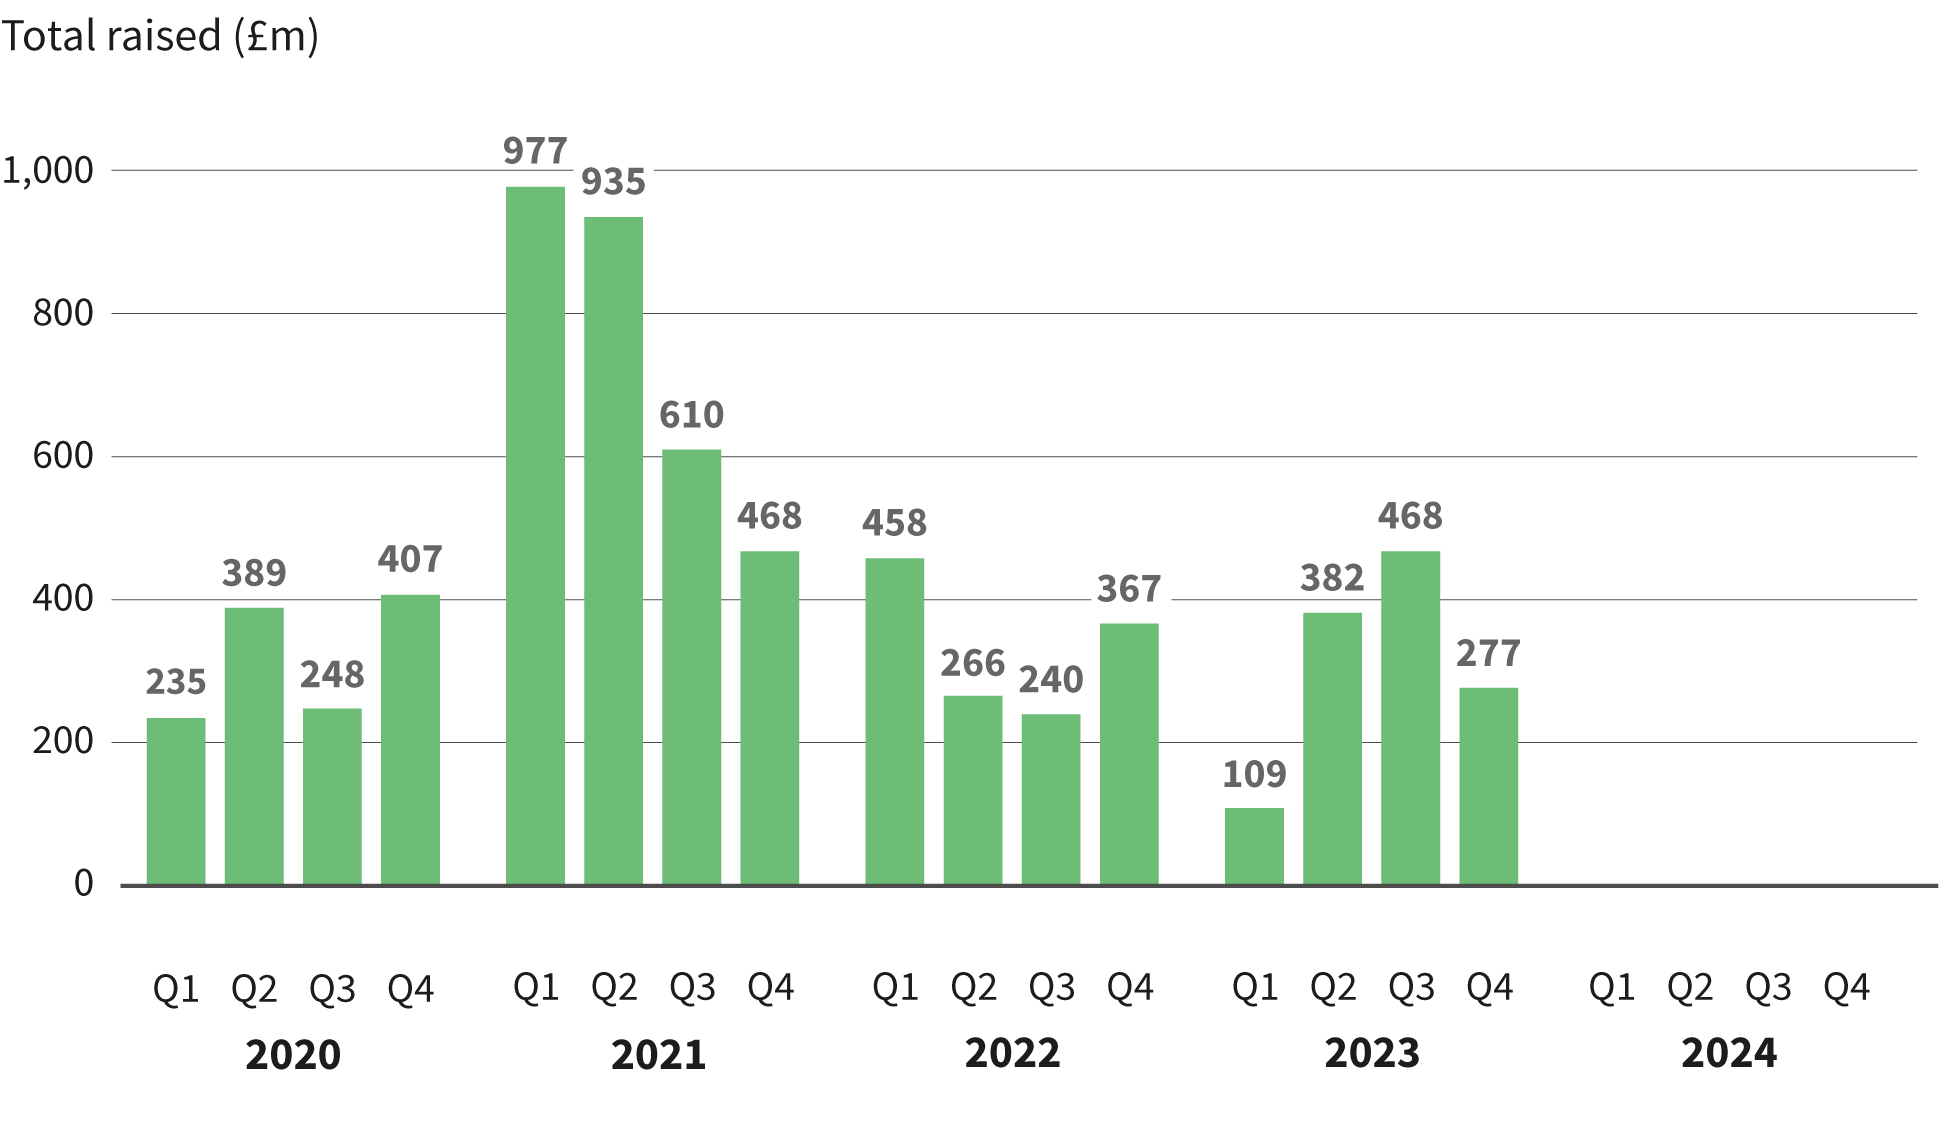
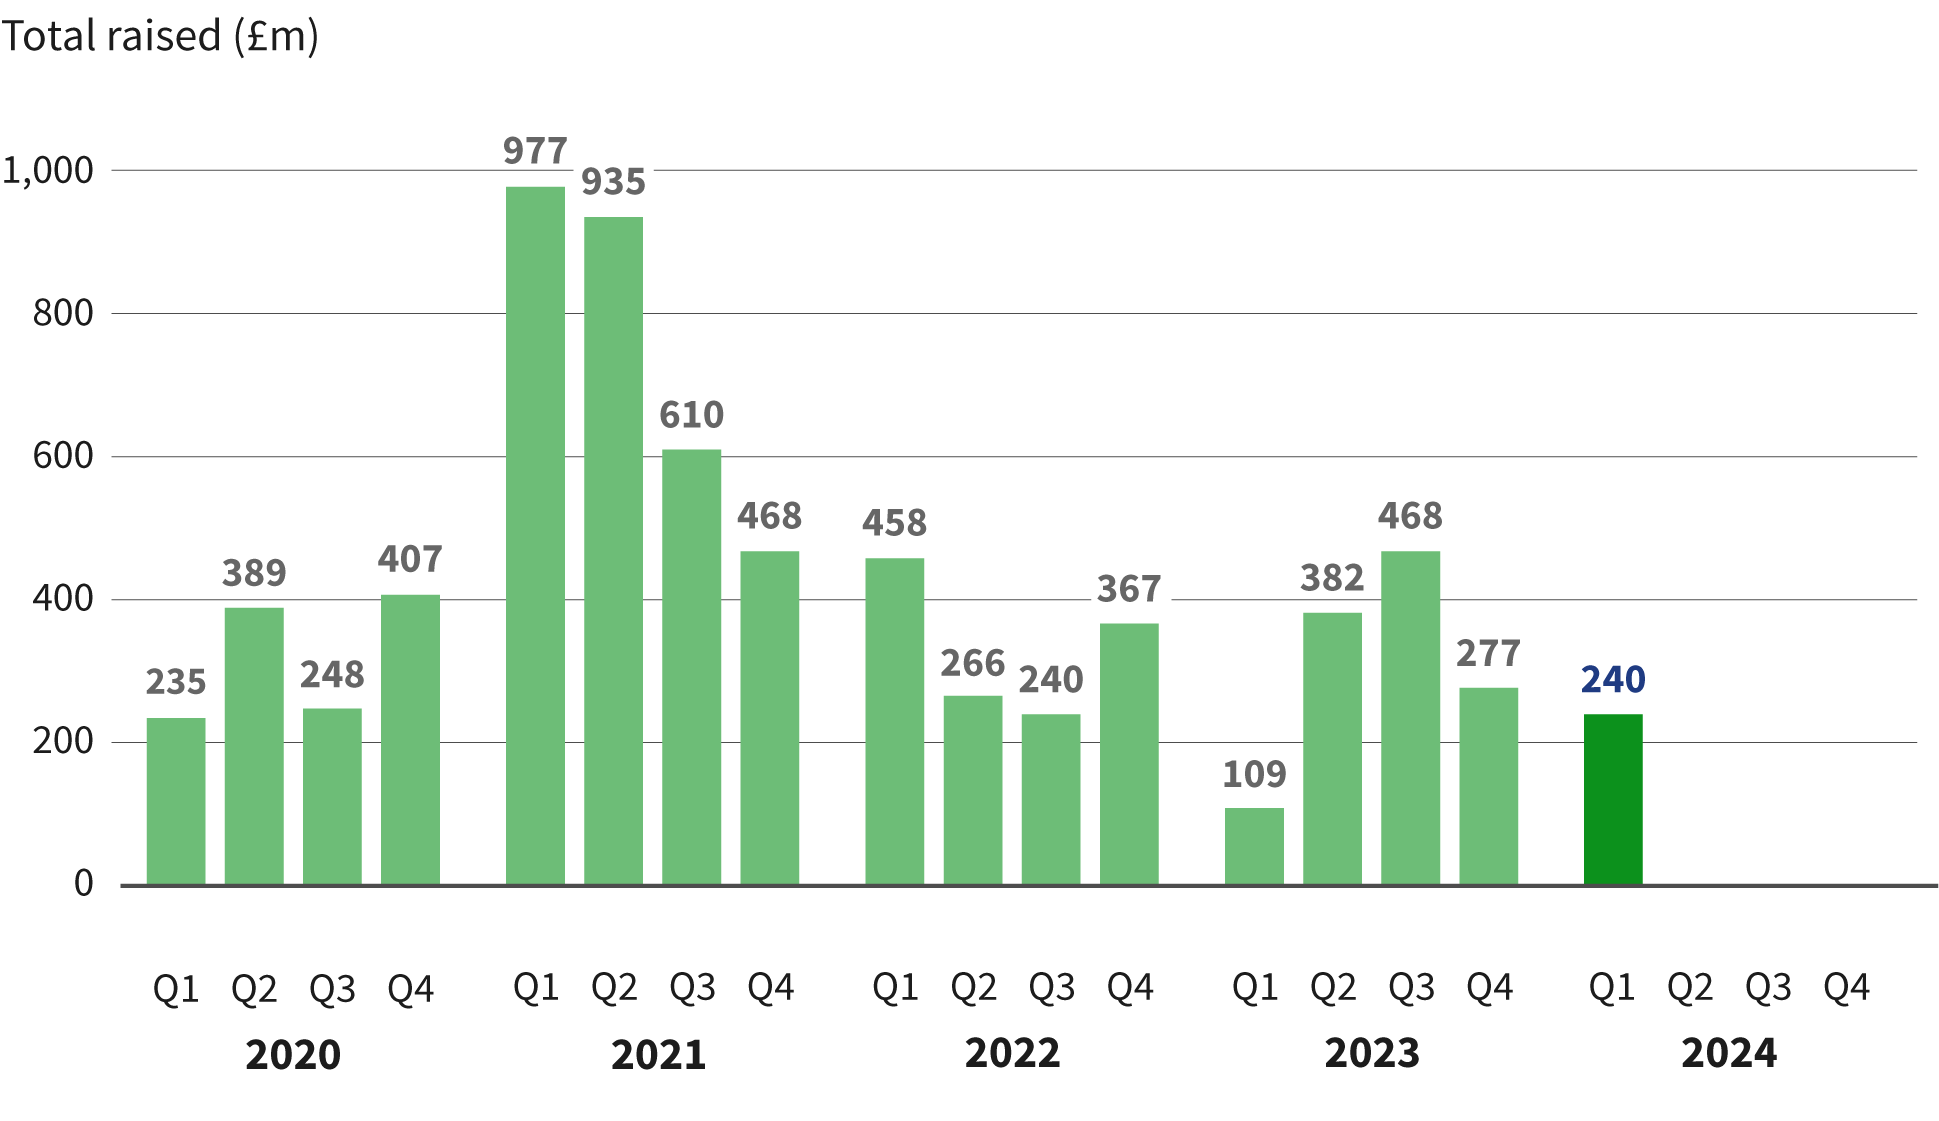
Total venture capital raised by quarter, for the past five years
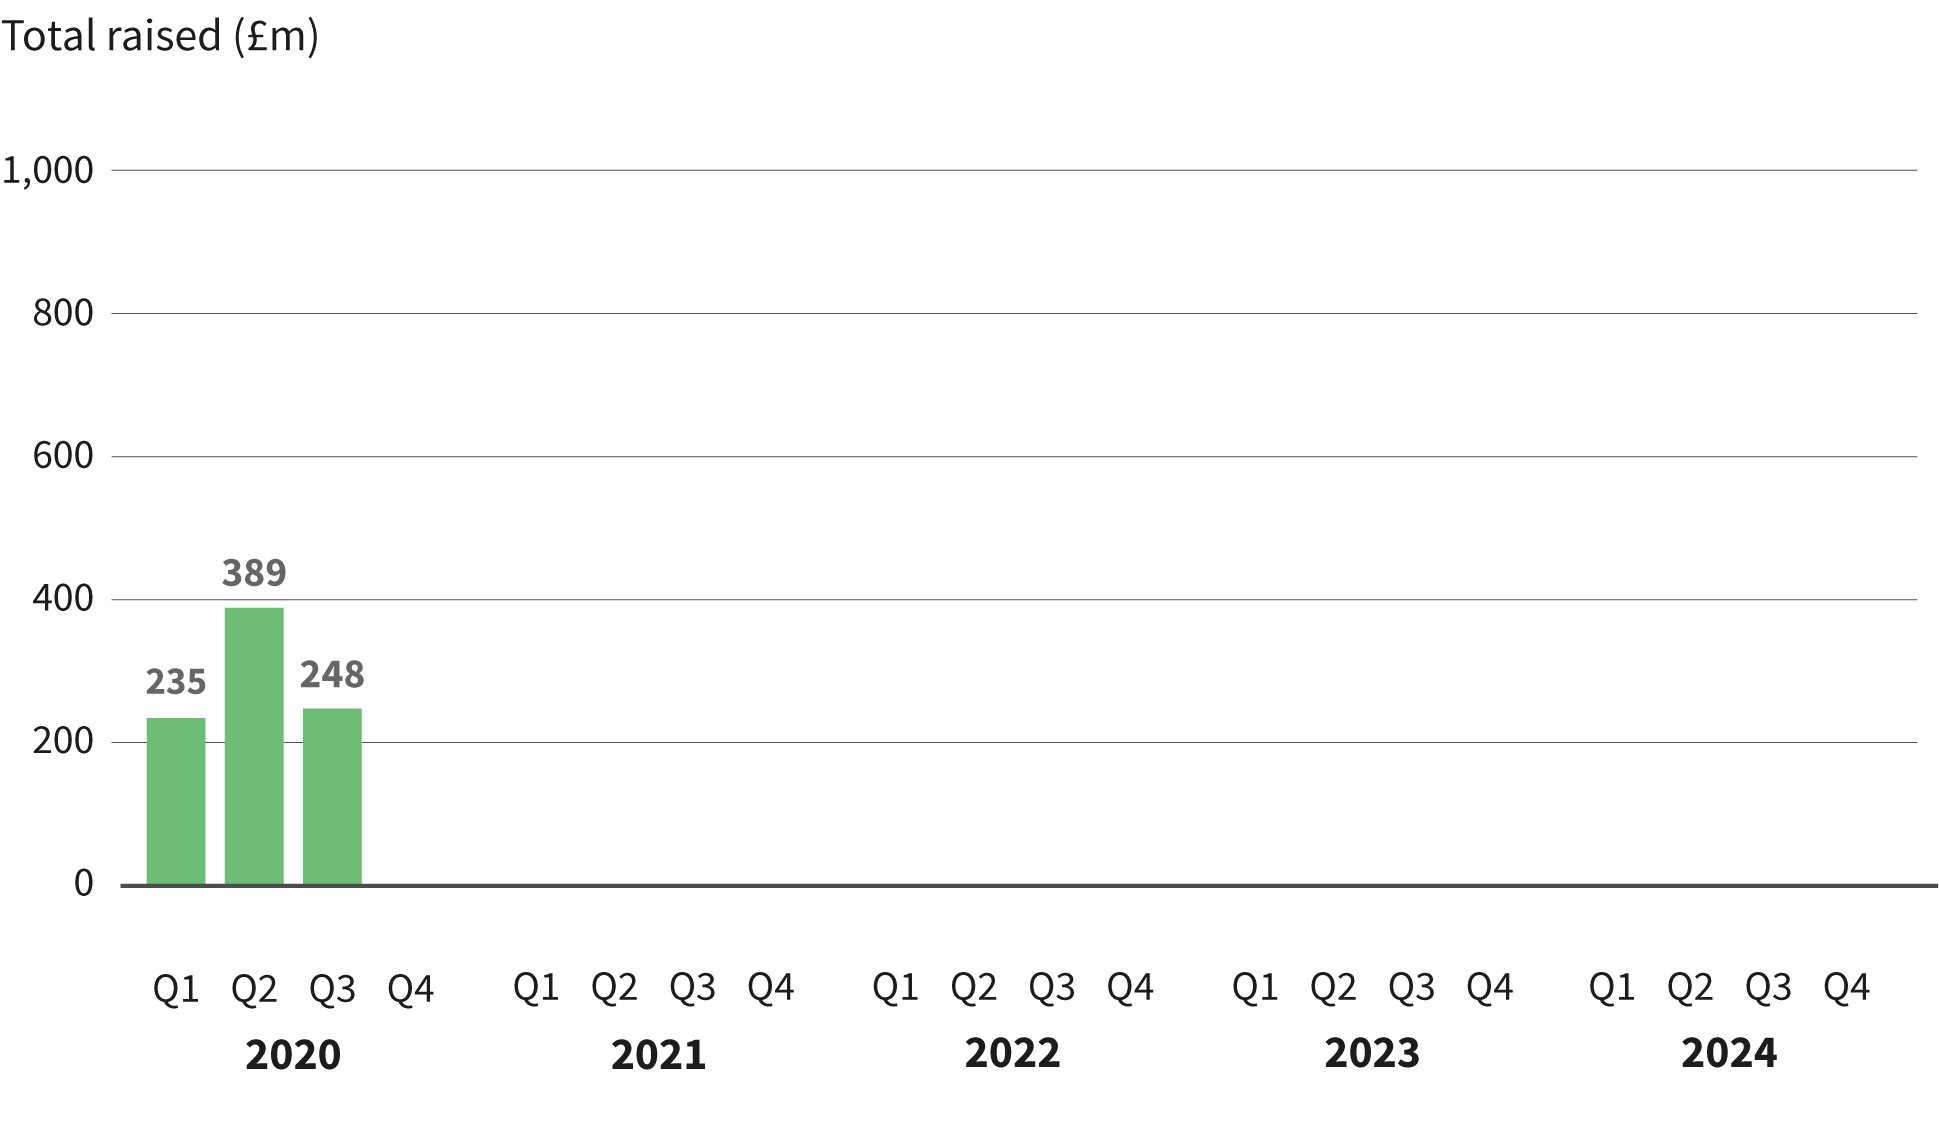
UK biotech venture capital deals by amount raised and deal count
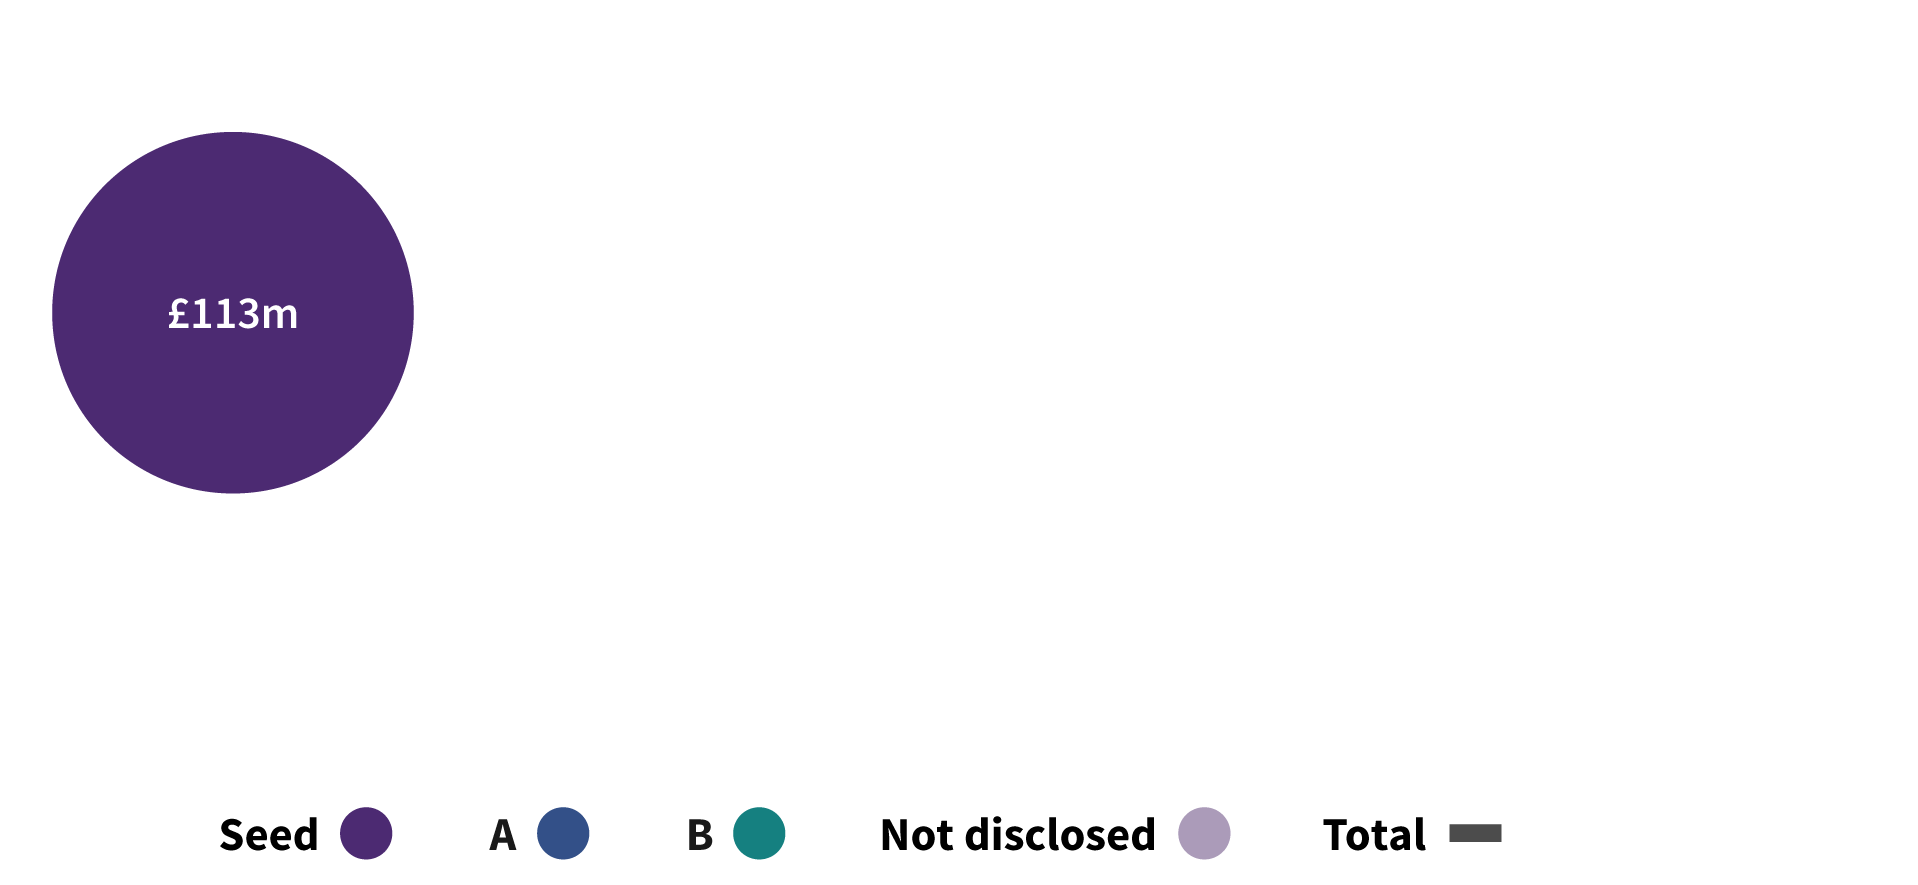
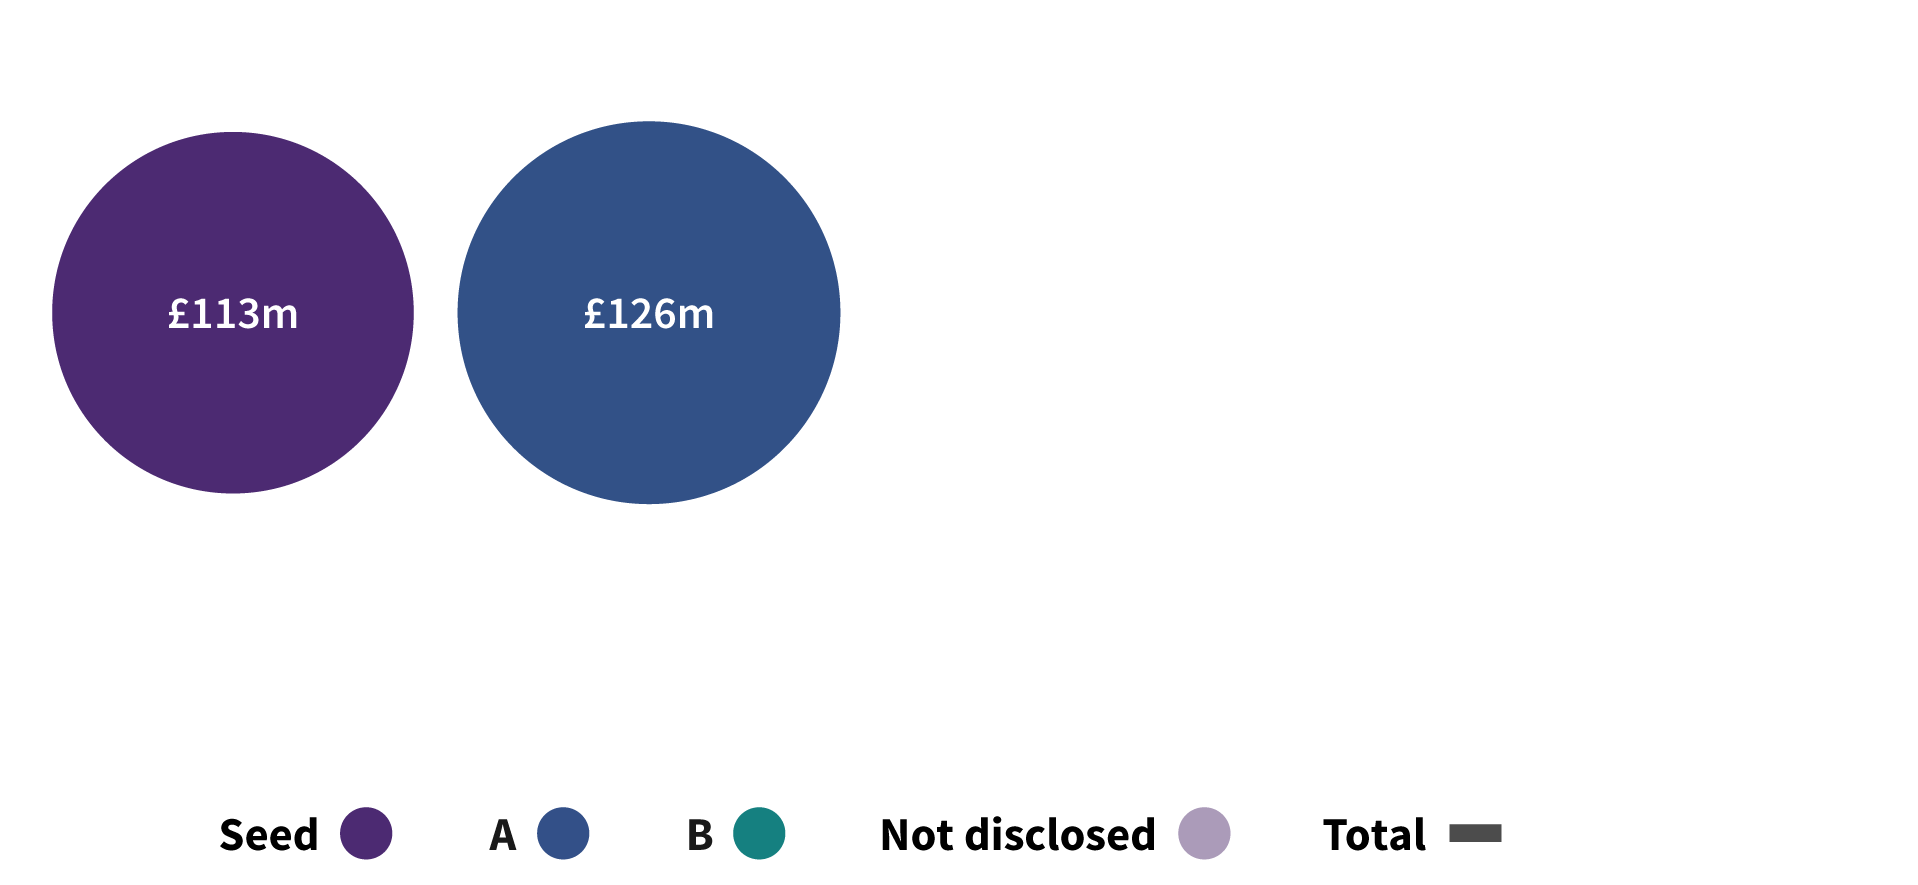
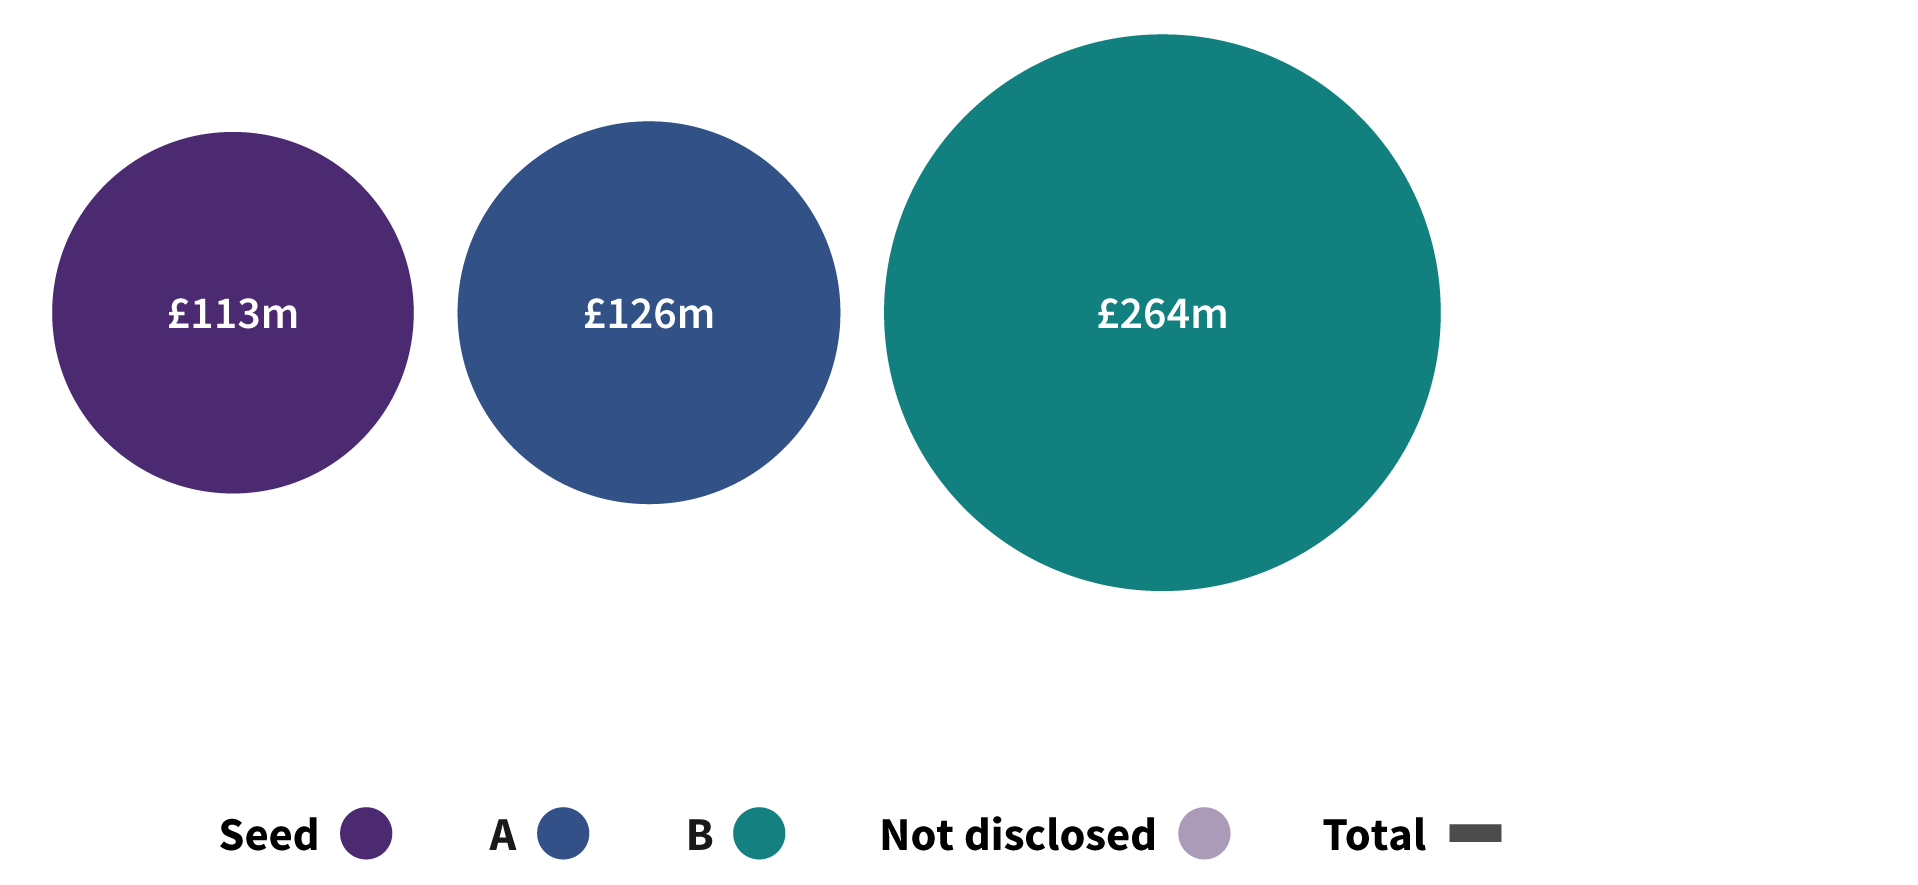
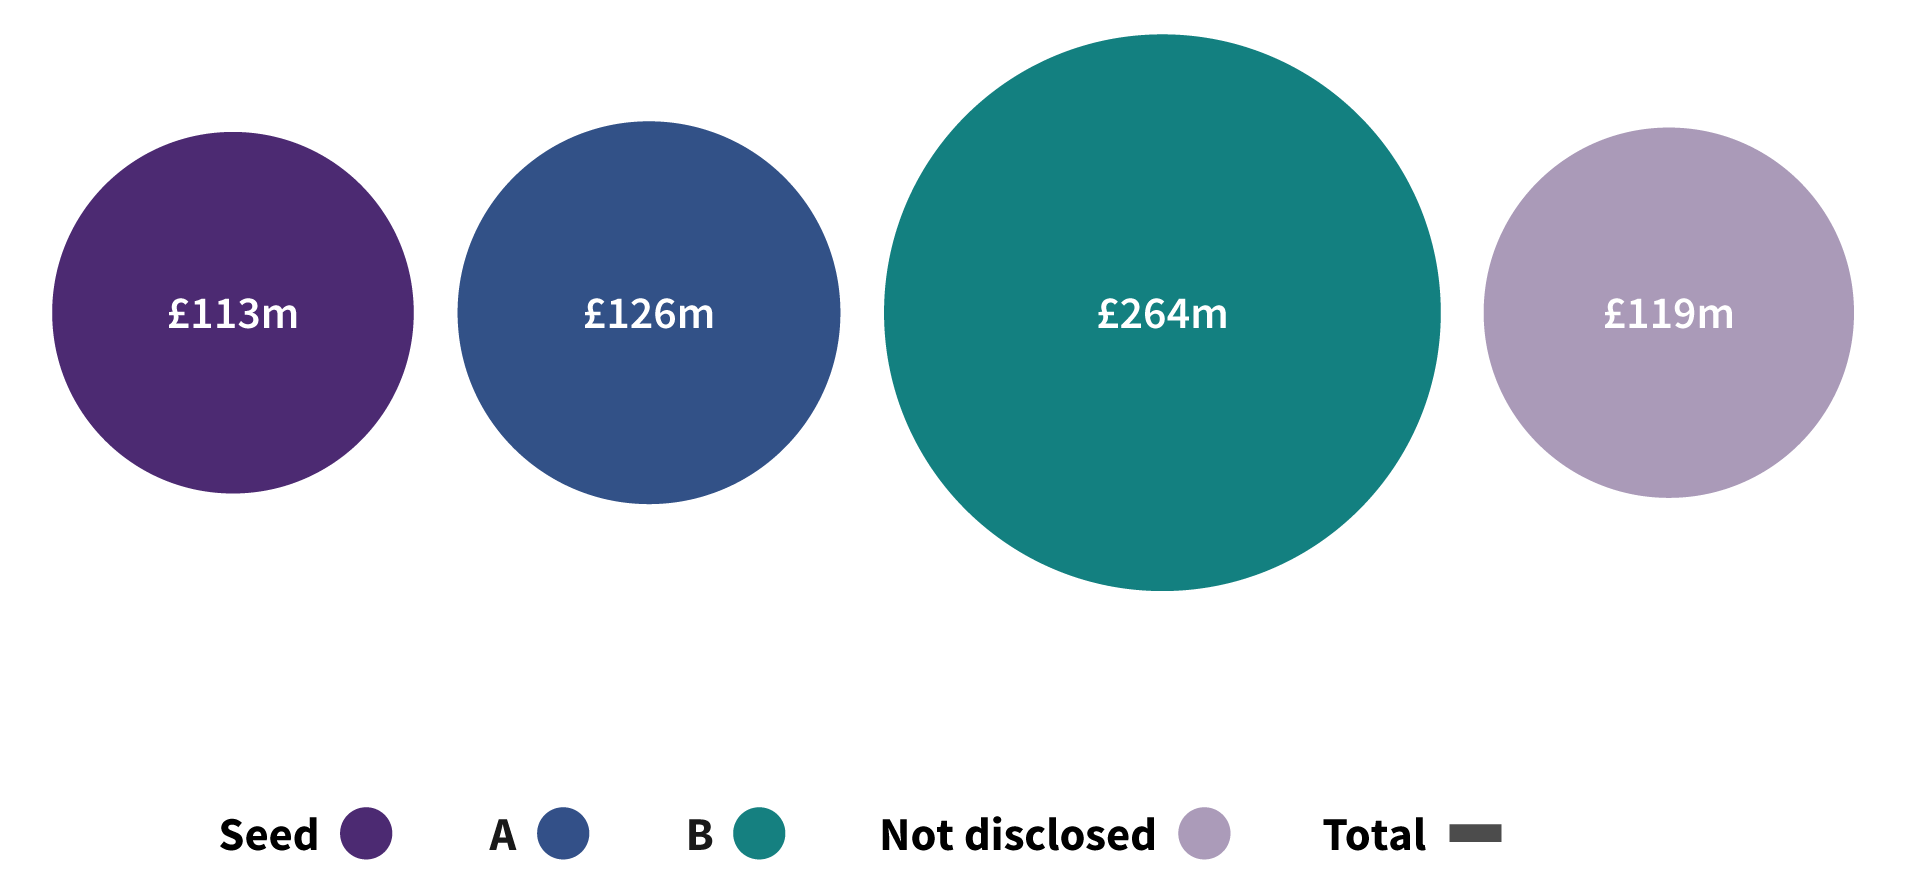
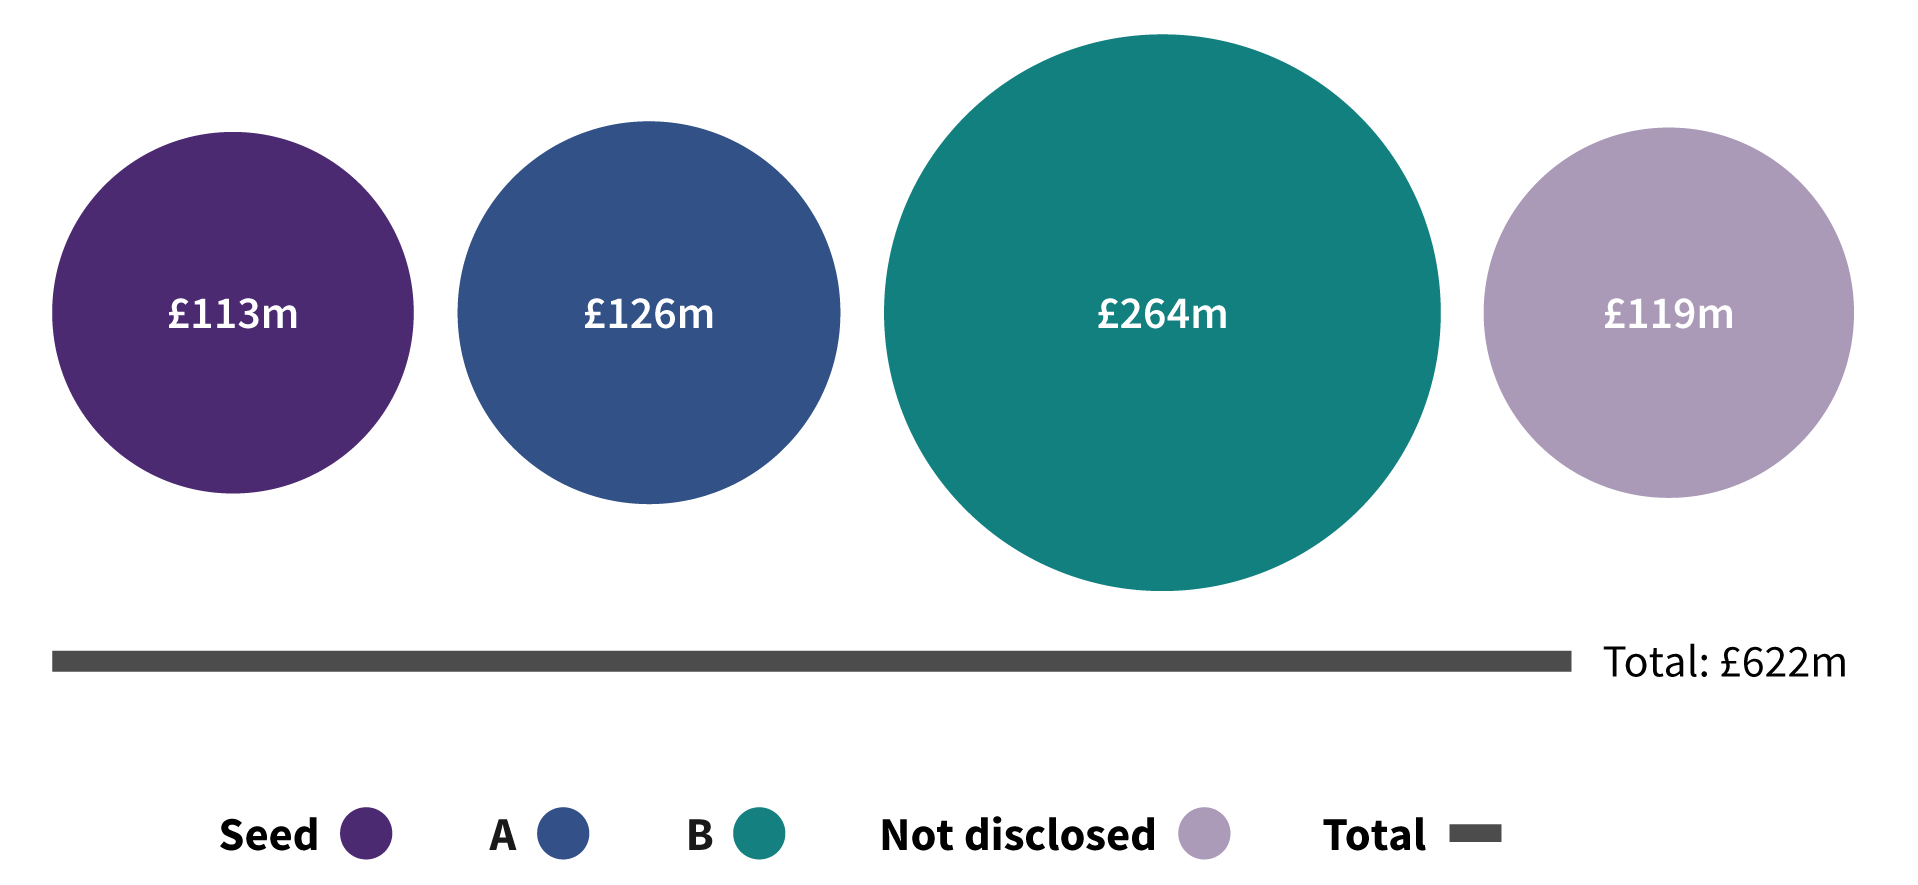
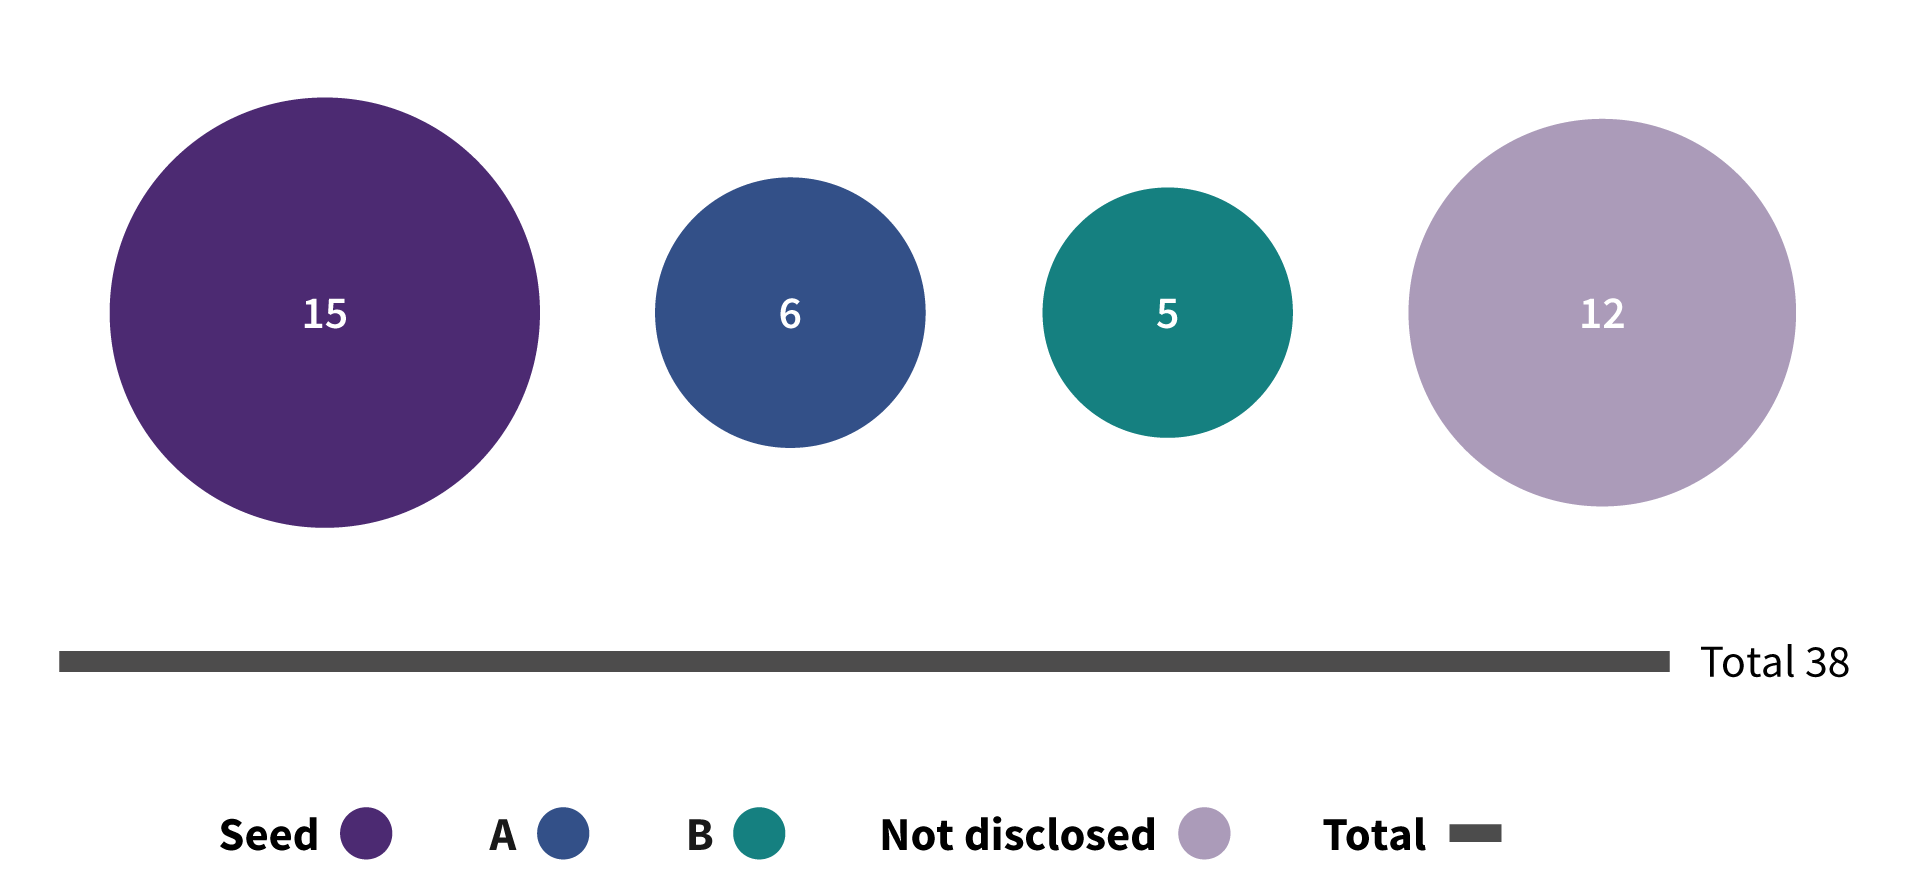
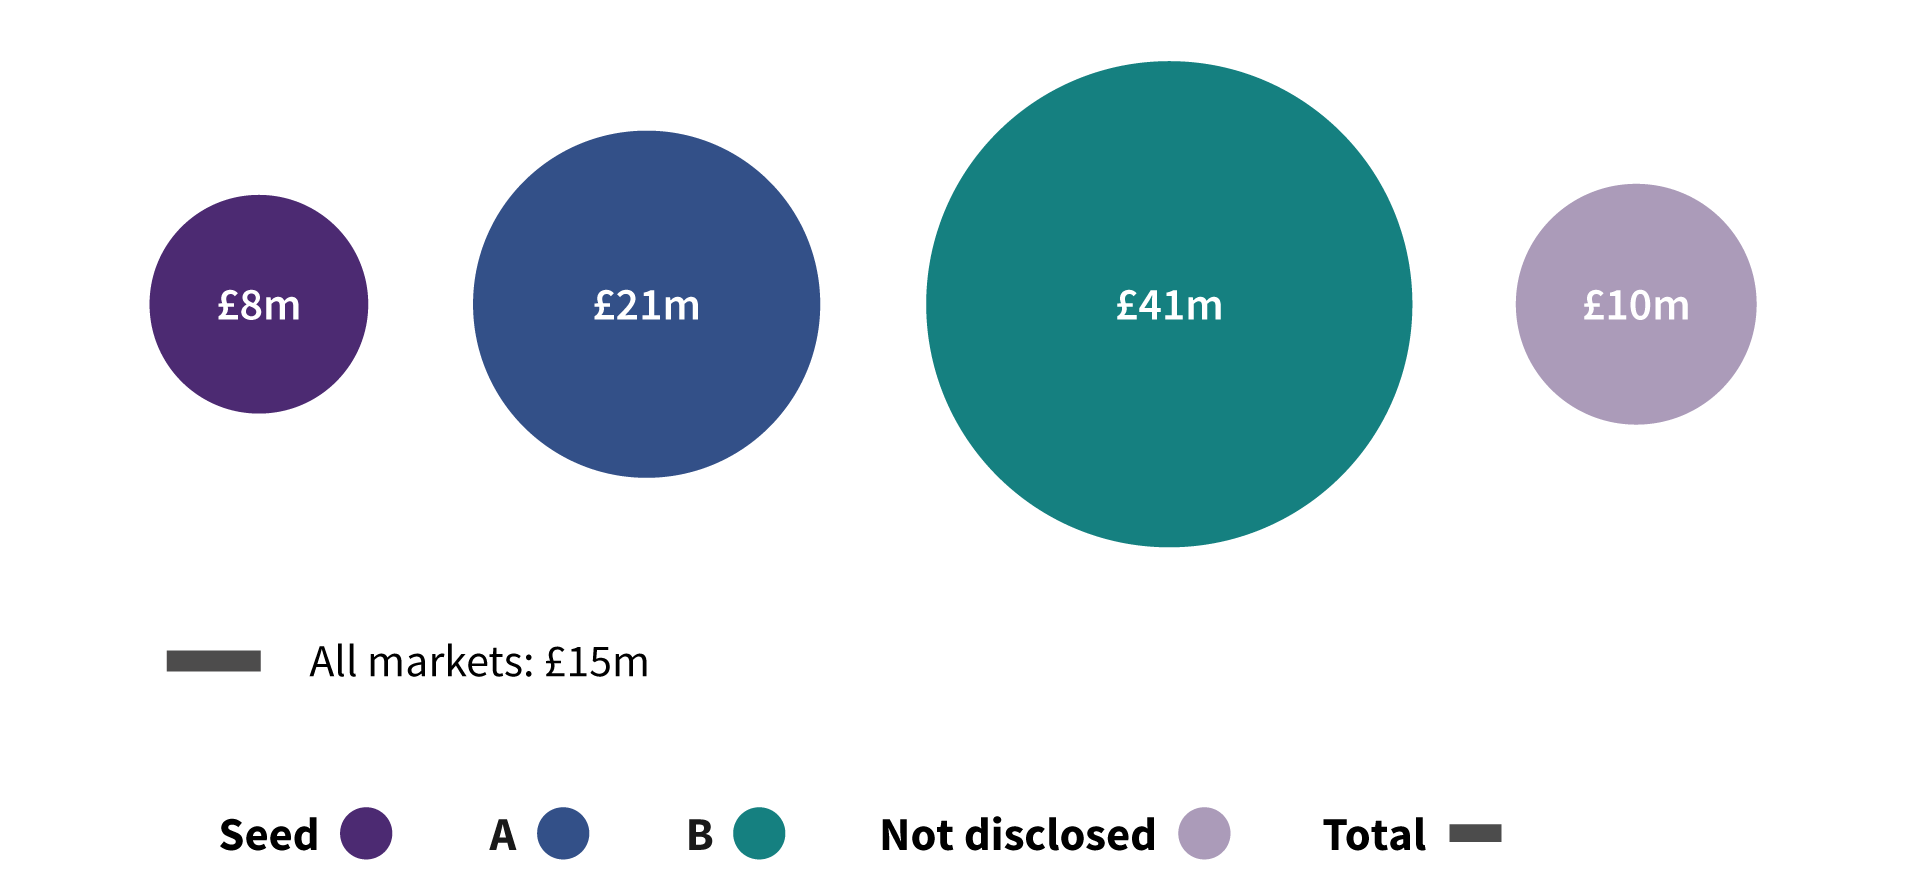
Pheon Therapeutics, an Antibody-Drug Conjugate (ADC) specialist, secured £94 million in Series B funding to fund the development of its pipeline of differentiated ADCs. This funding significantly increased the average Series B deal size to £41 million, up from £25 million in the previous quarter and signals a welcome return to larger financing deals not seen in Q1 – combined with Amber Therapeutics raising £79 million and three other £30 million+ deals.
Top five UK biotech venture capital deals
| Company | Date | Round | Amount (£m) |
|---|---|---|---|
| Pheon Therapeutics | 21/05/2024 | Series B | 94 |
| Amber Therapeutics | 10/06/2024 | Series A | 79 |
| SynOx | 22/04/2024 | Series B | 58 |
| LabGenius | 21/05/2024 | Series B | 35 |
| Genomics | 07/05/2024 | ND | 34 |
International VC financing
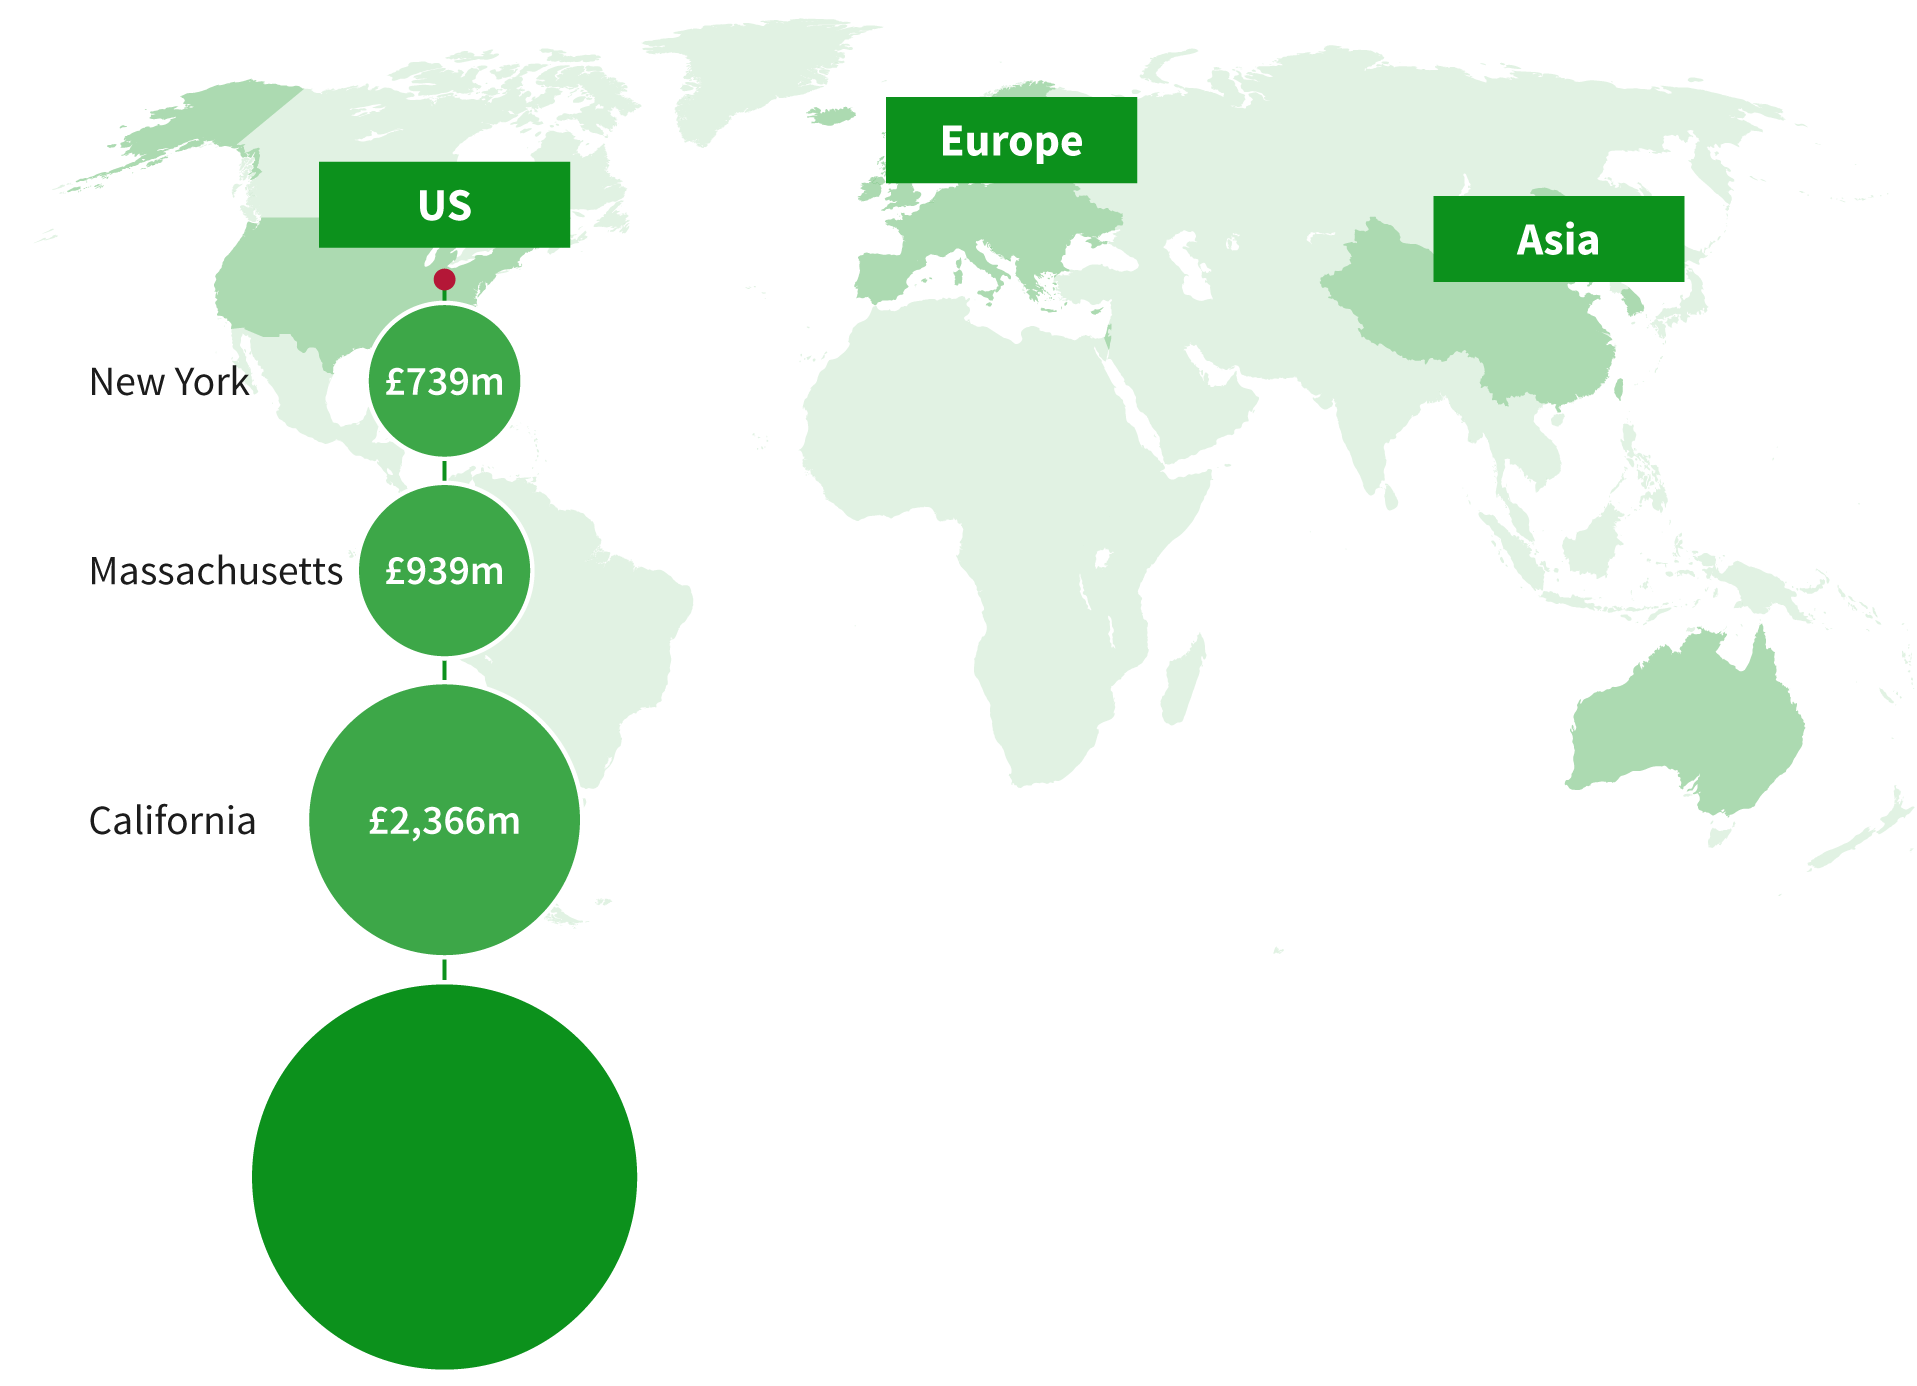
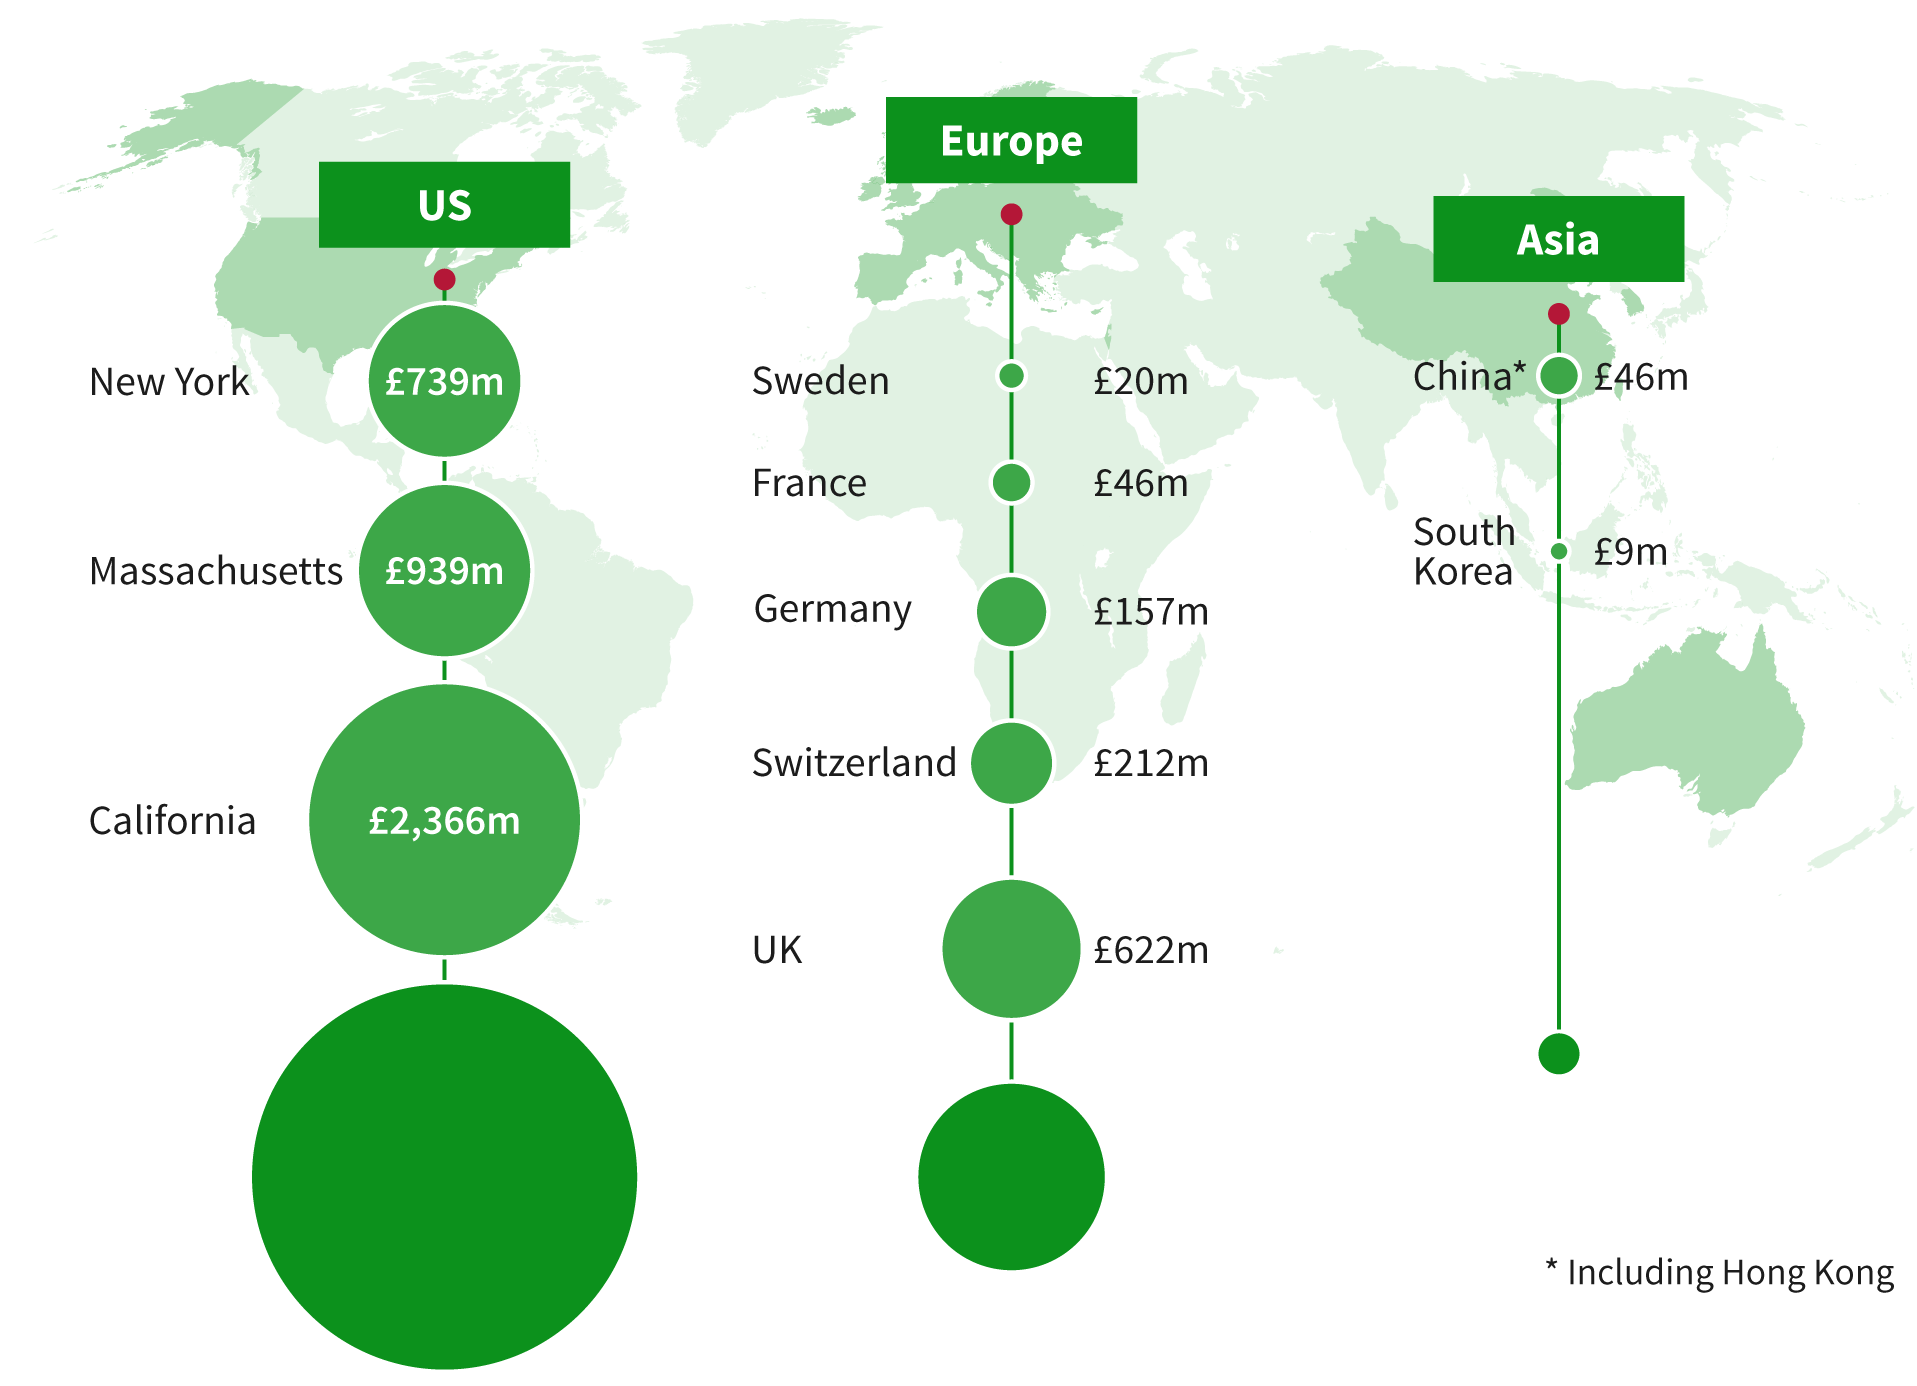
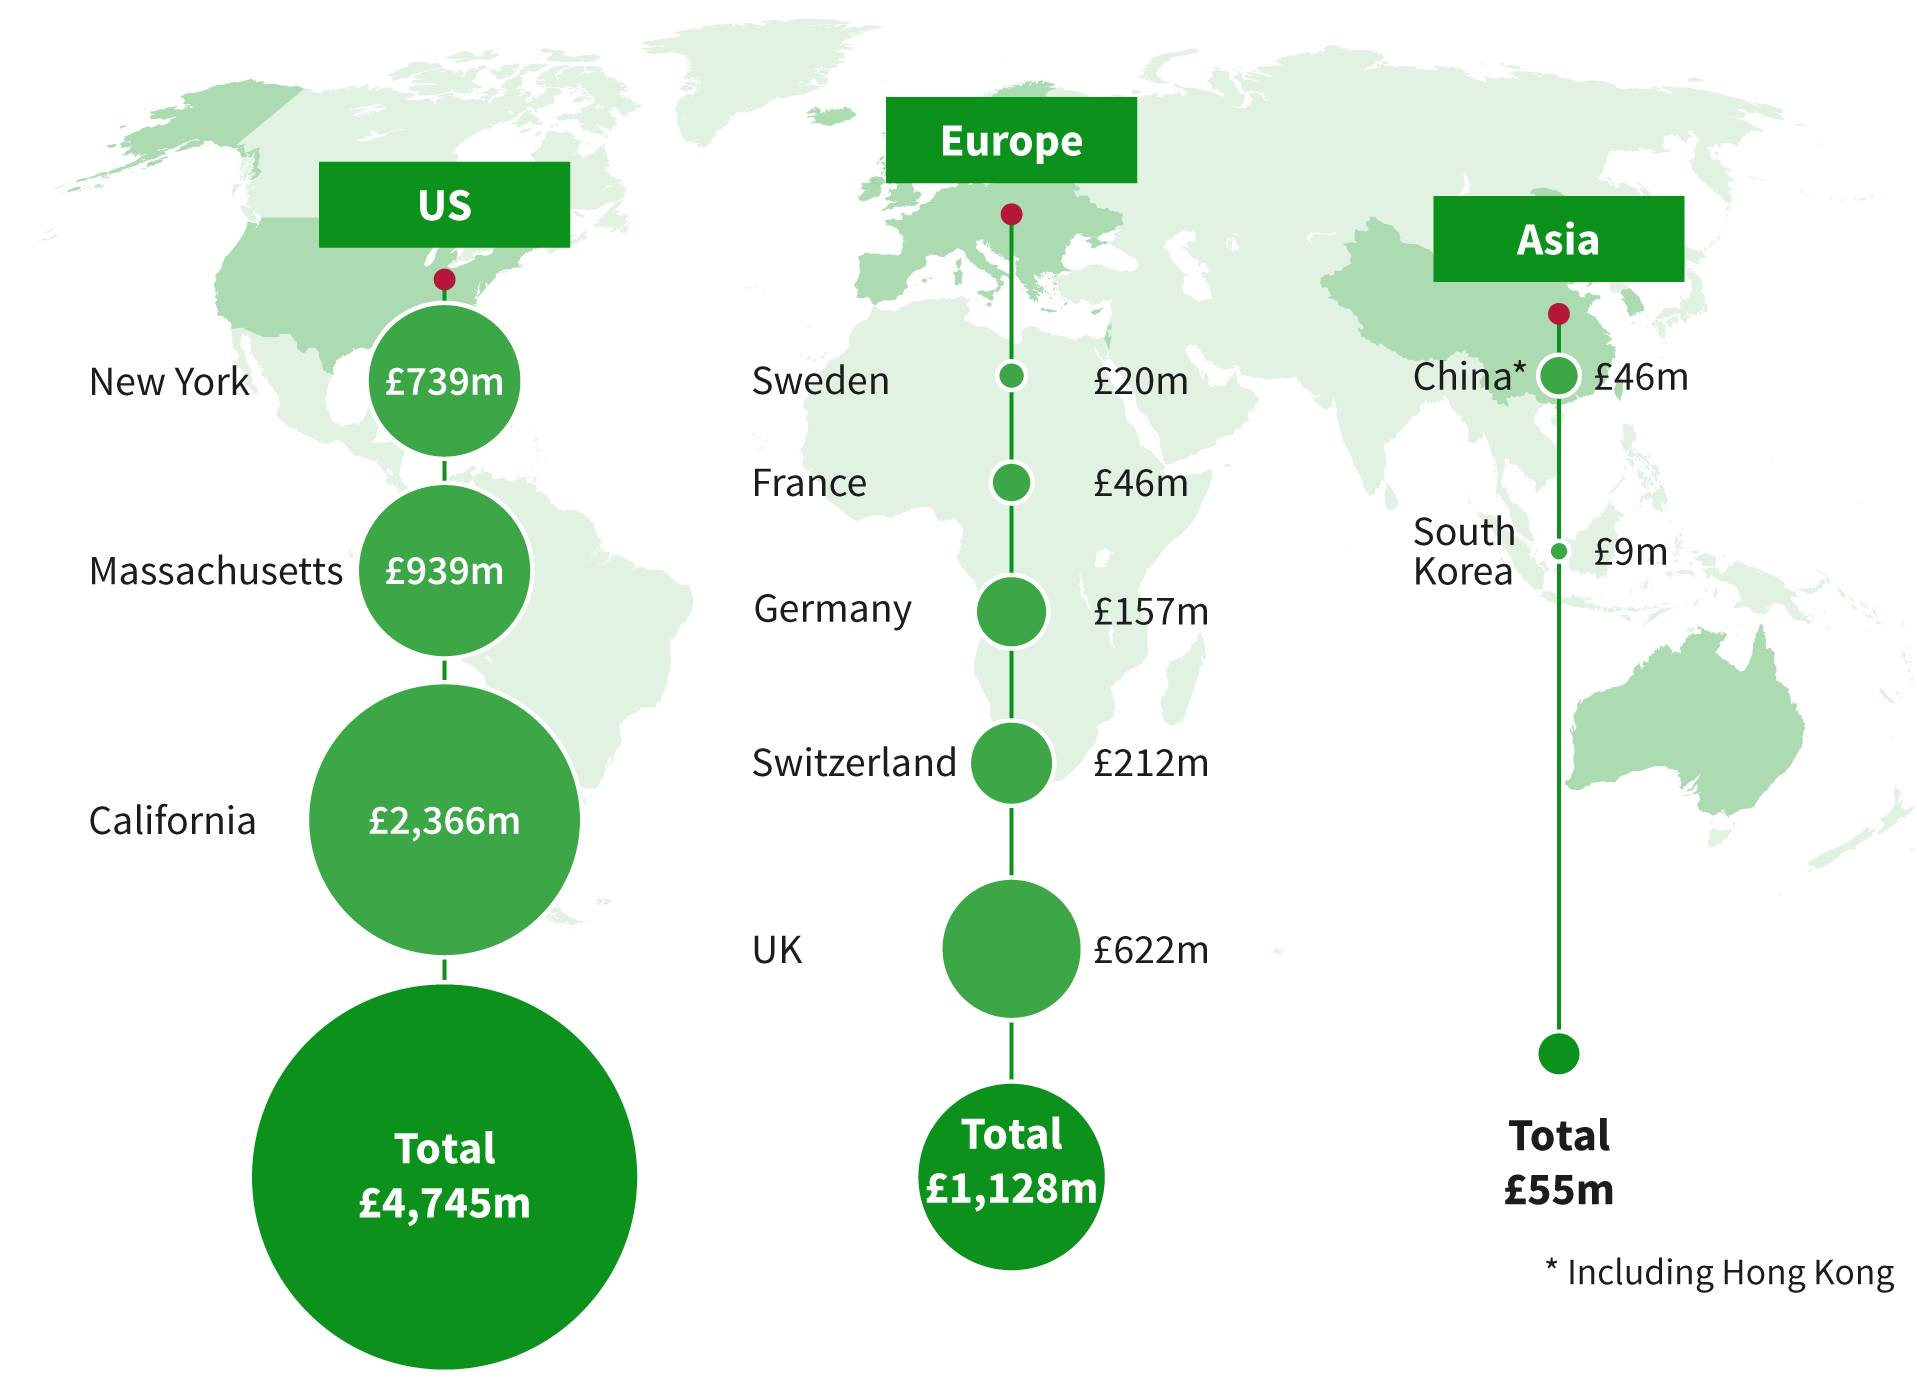
Globally, venture capital funding has been steadily increasing as well. The US secured £4.8 billion, while Europe raised £1.1 billion. This trend aligns with the previous year’s pattern of a slower start to the year. However, Asian companies saw a 76% reduction in fundraising activity.
 Public markets
IPOs
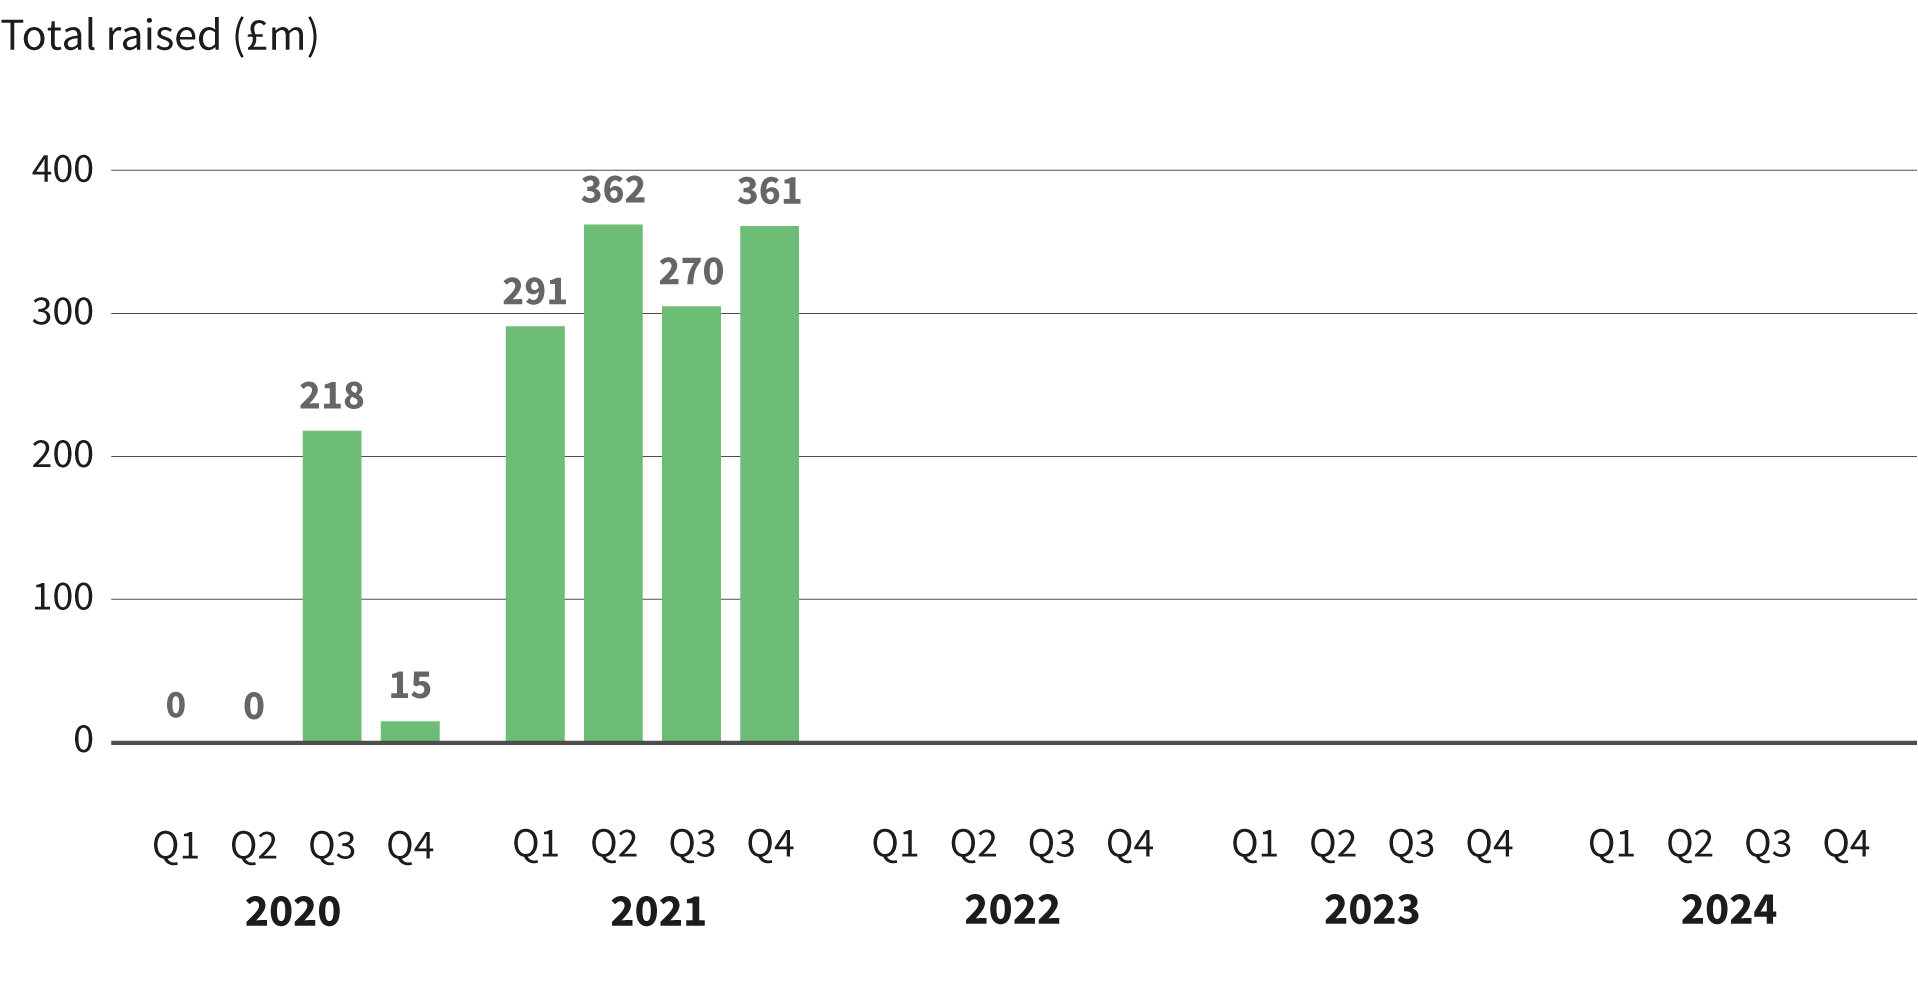
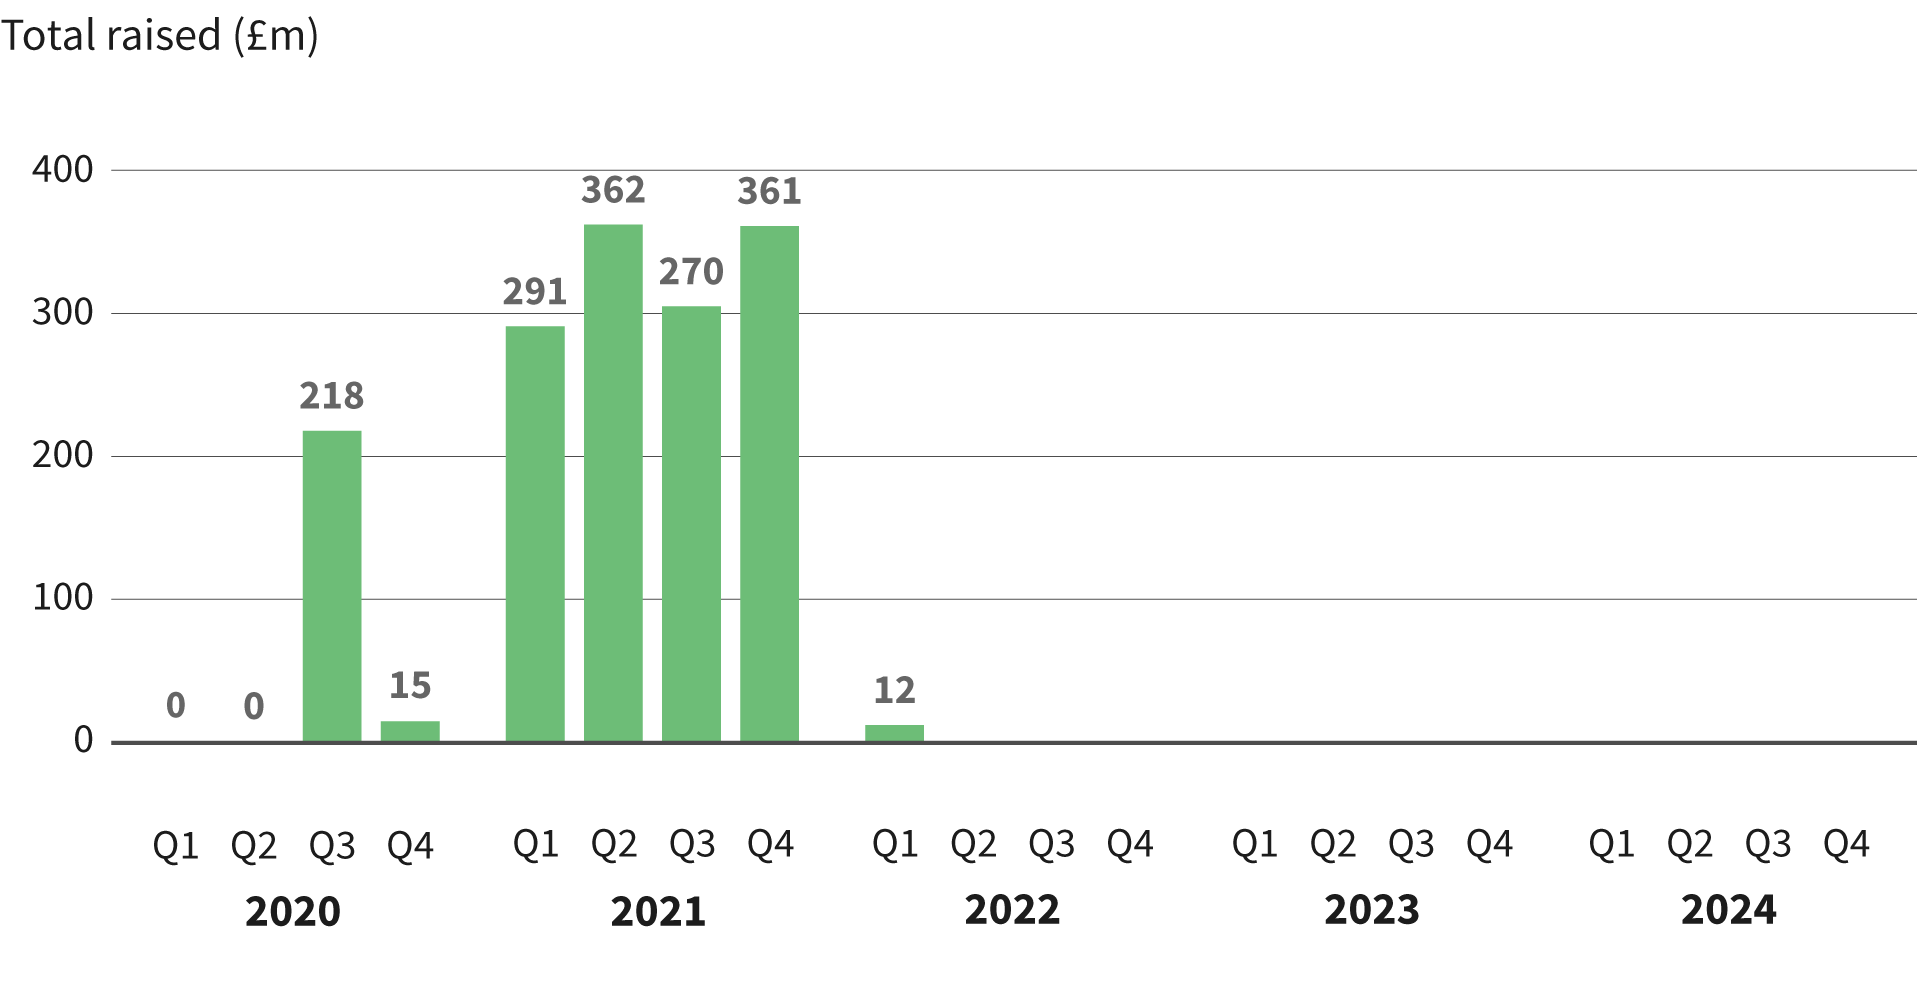
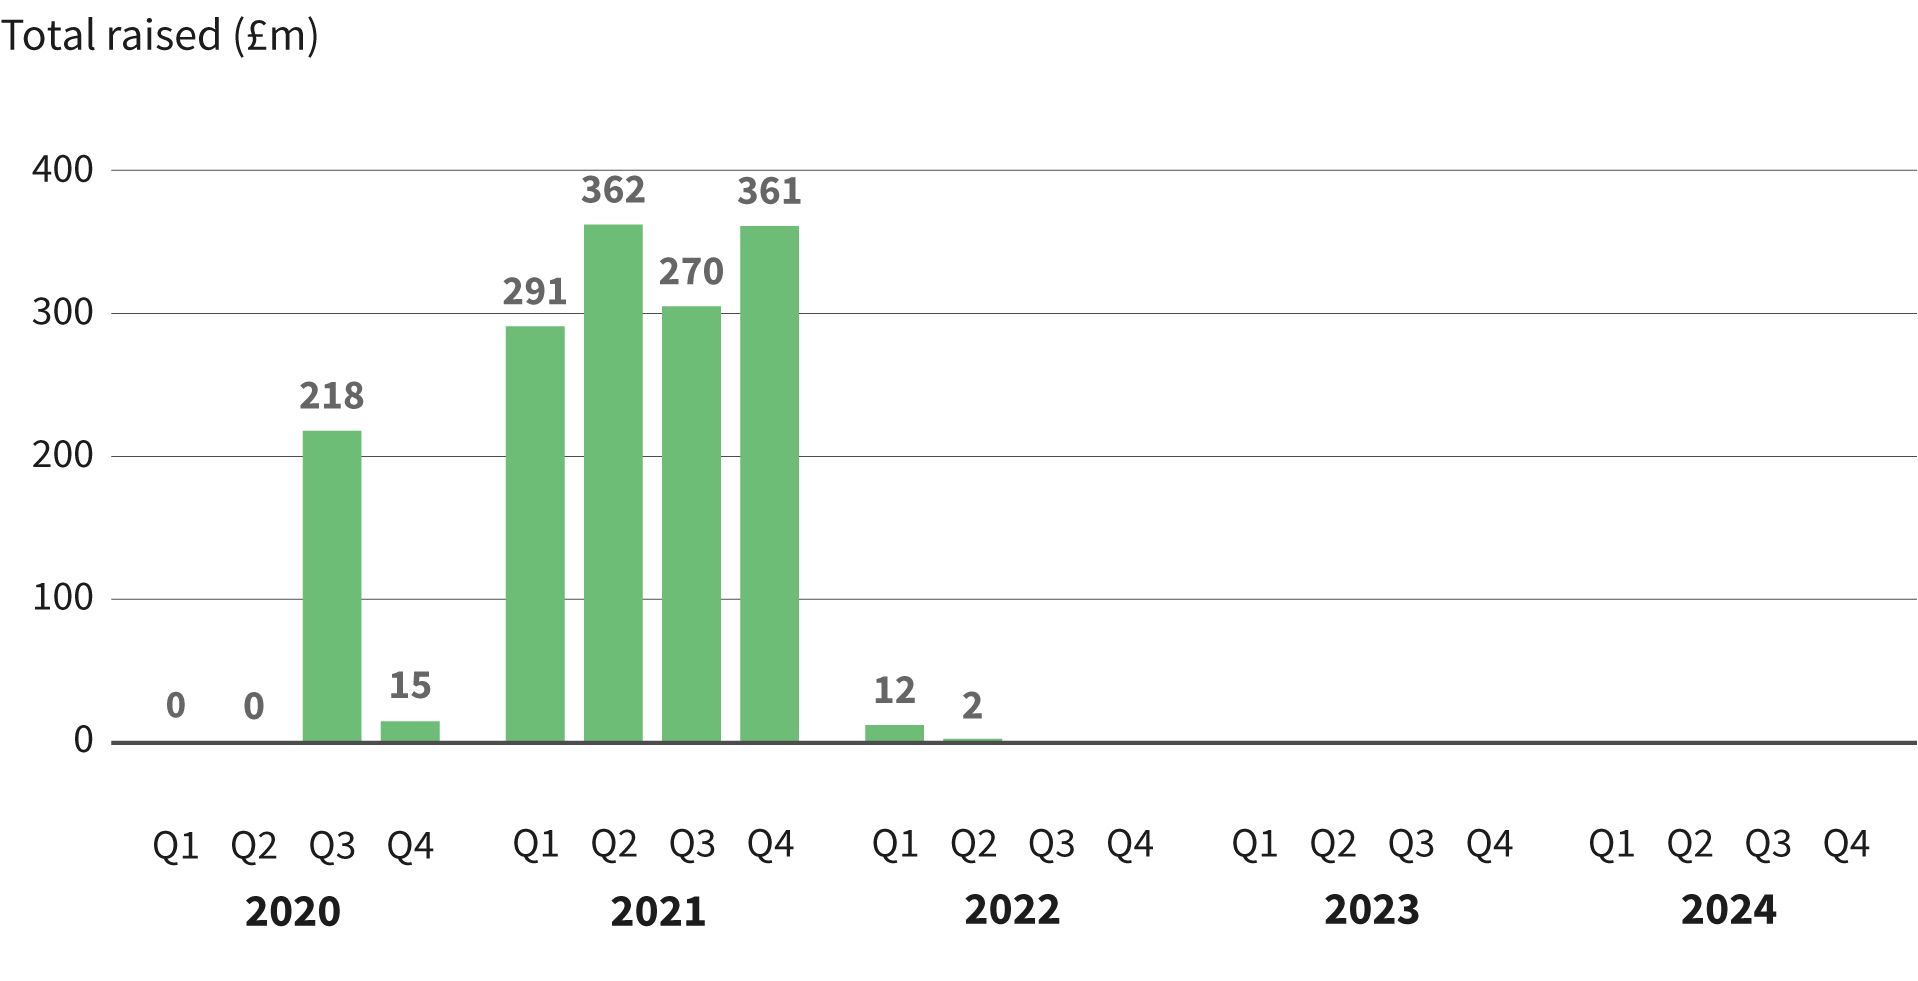
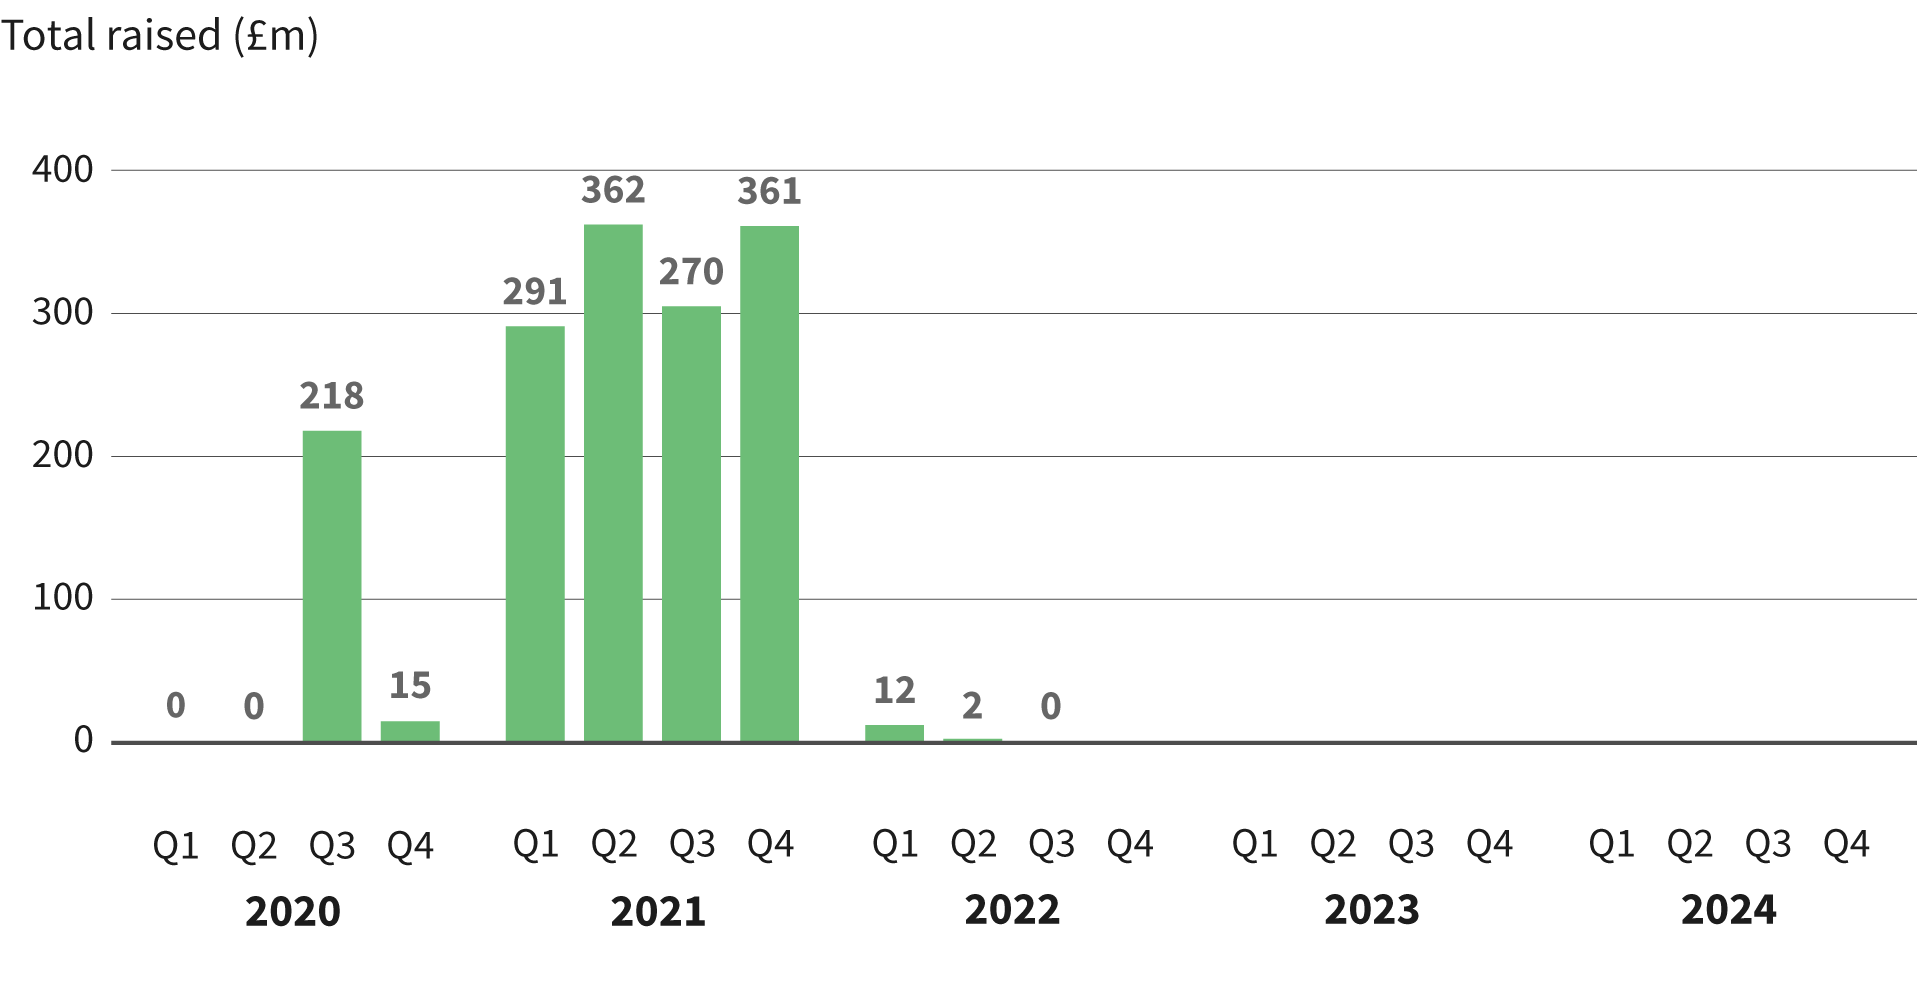
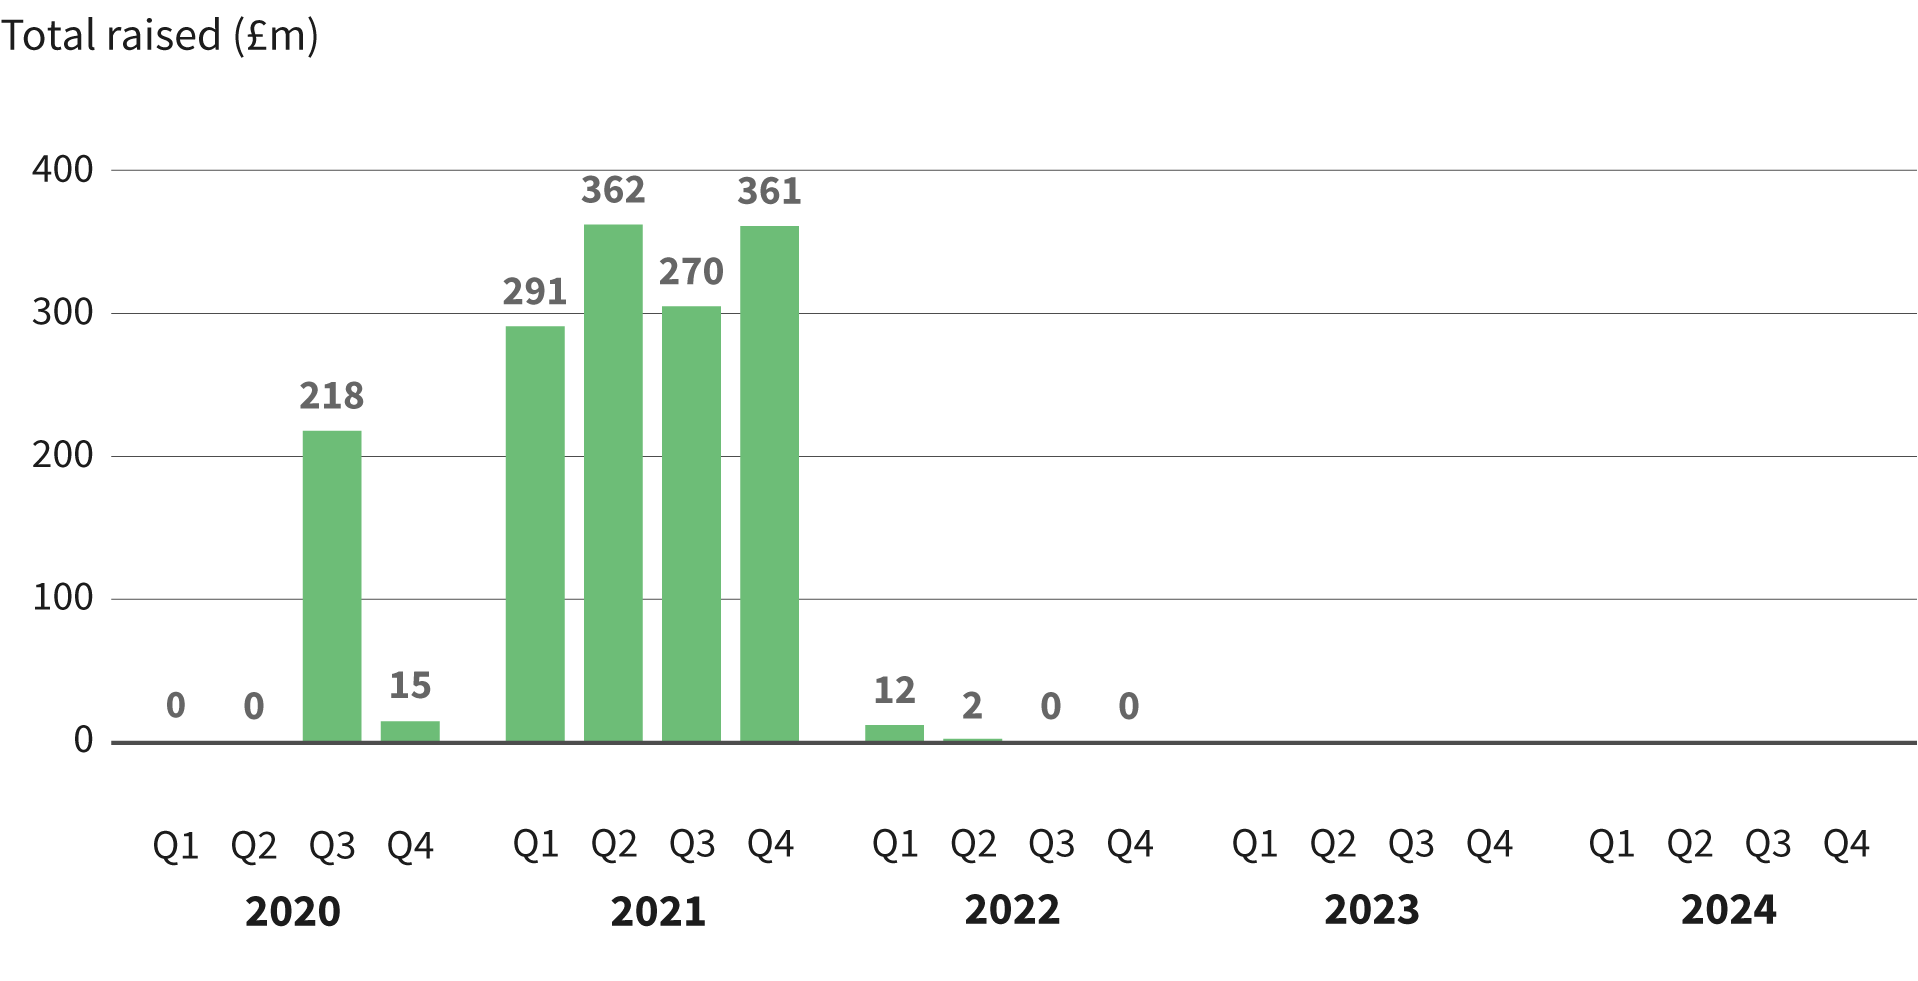
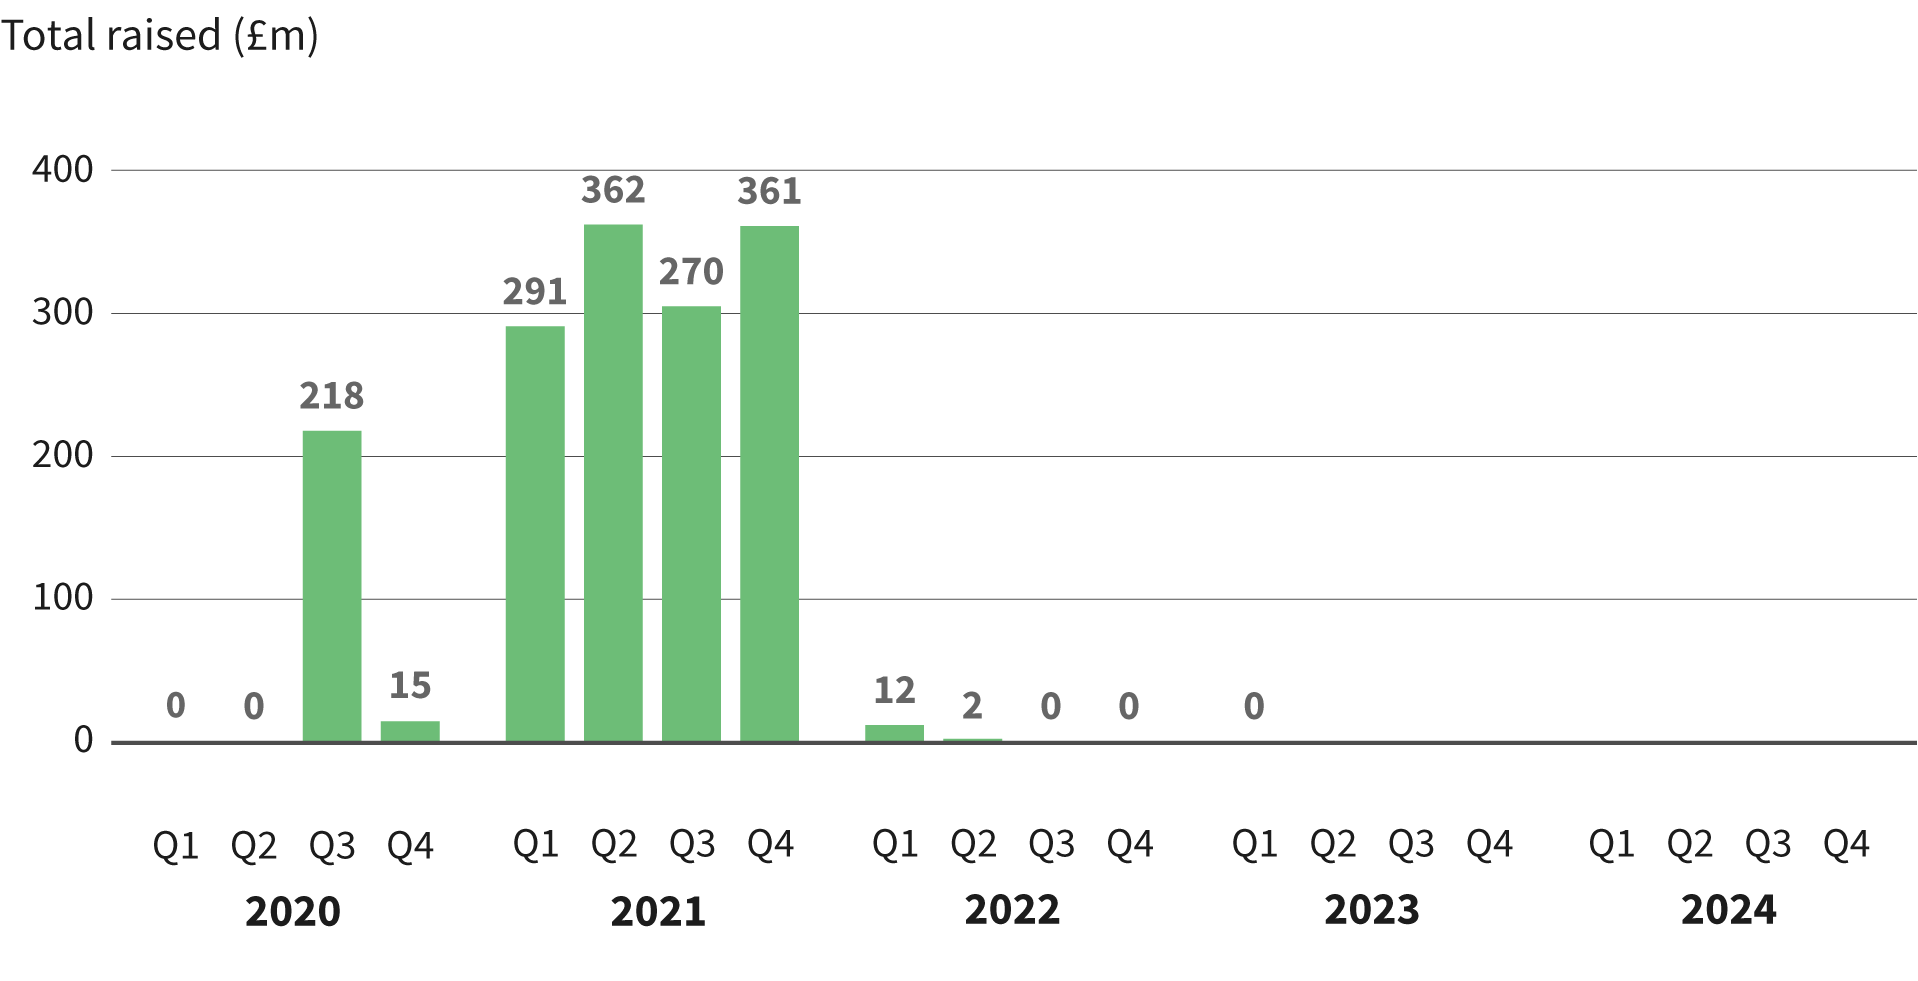
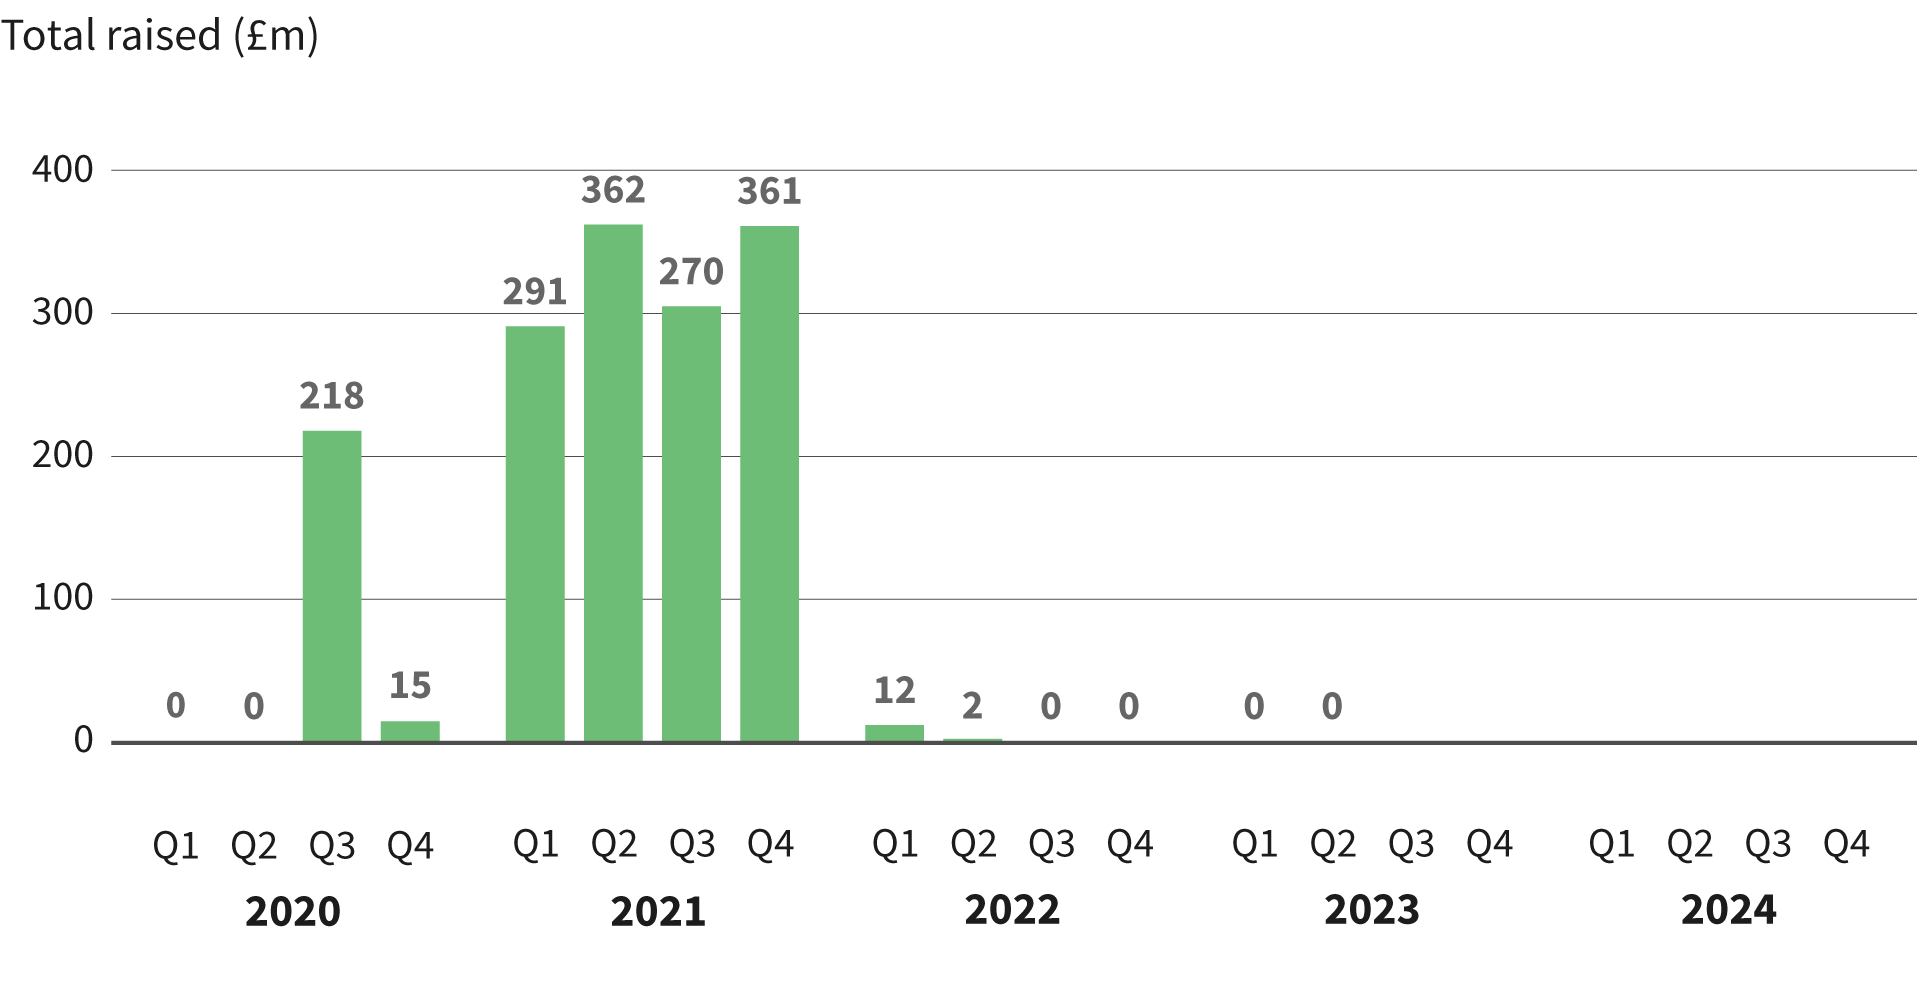
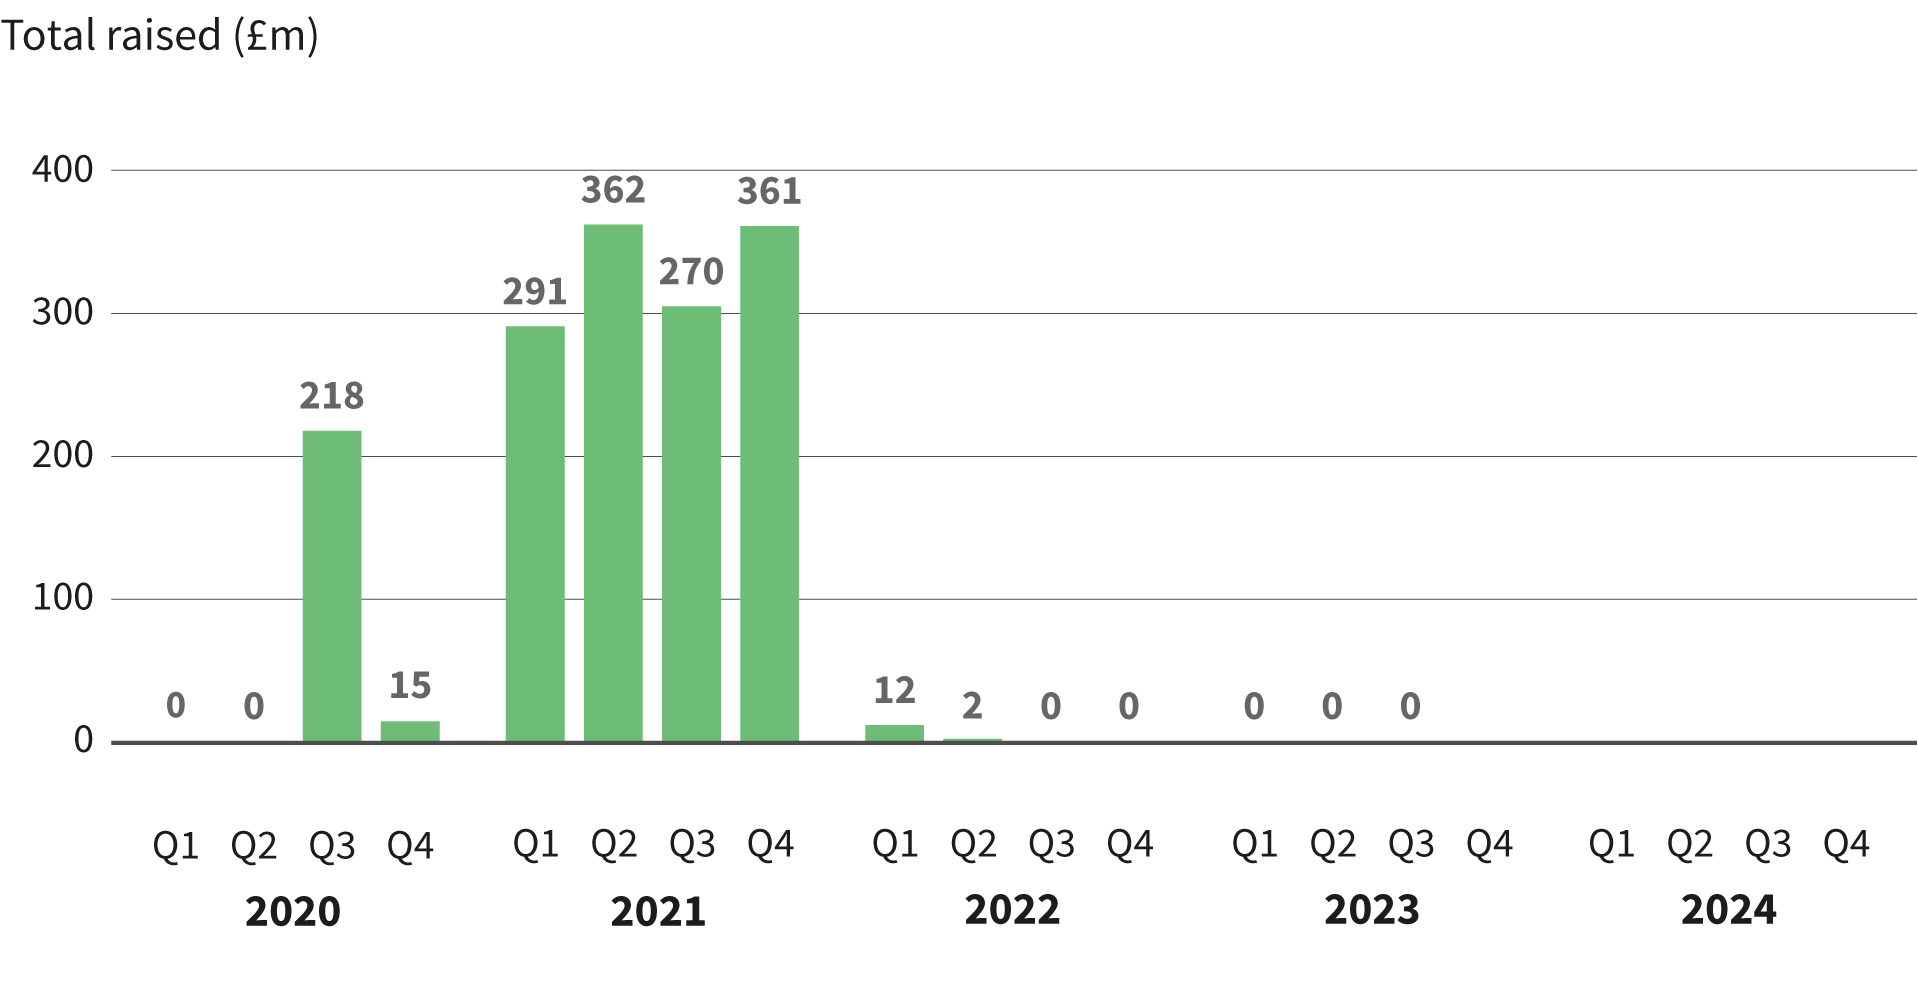
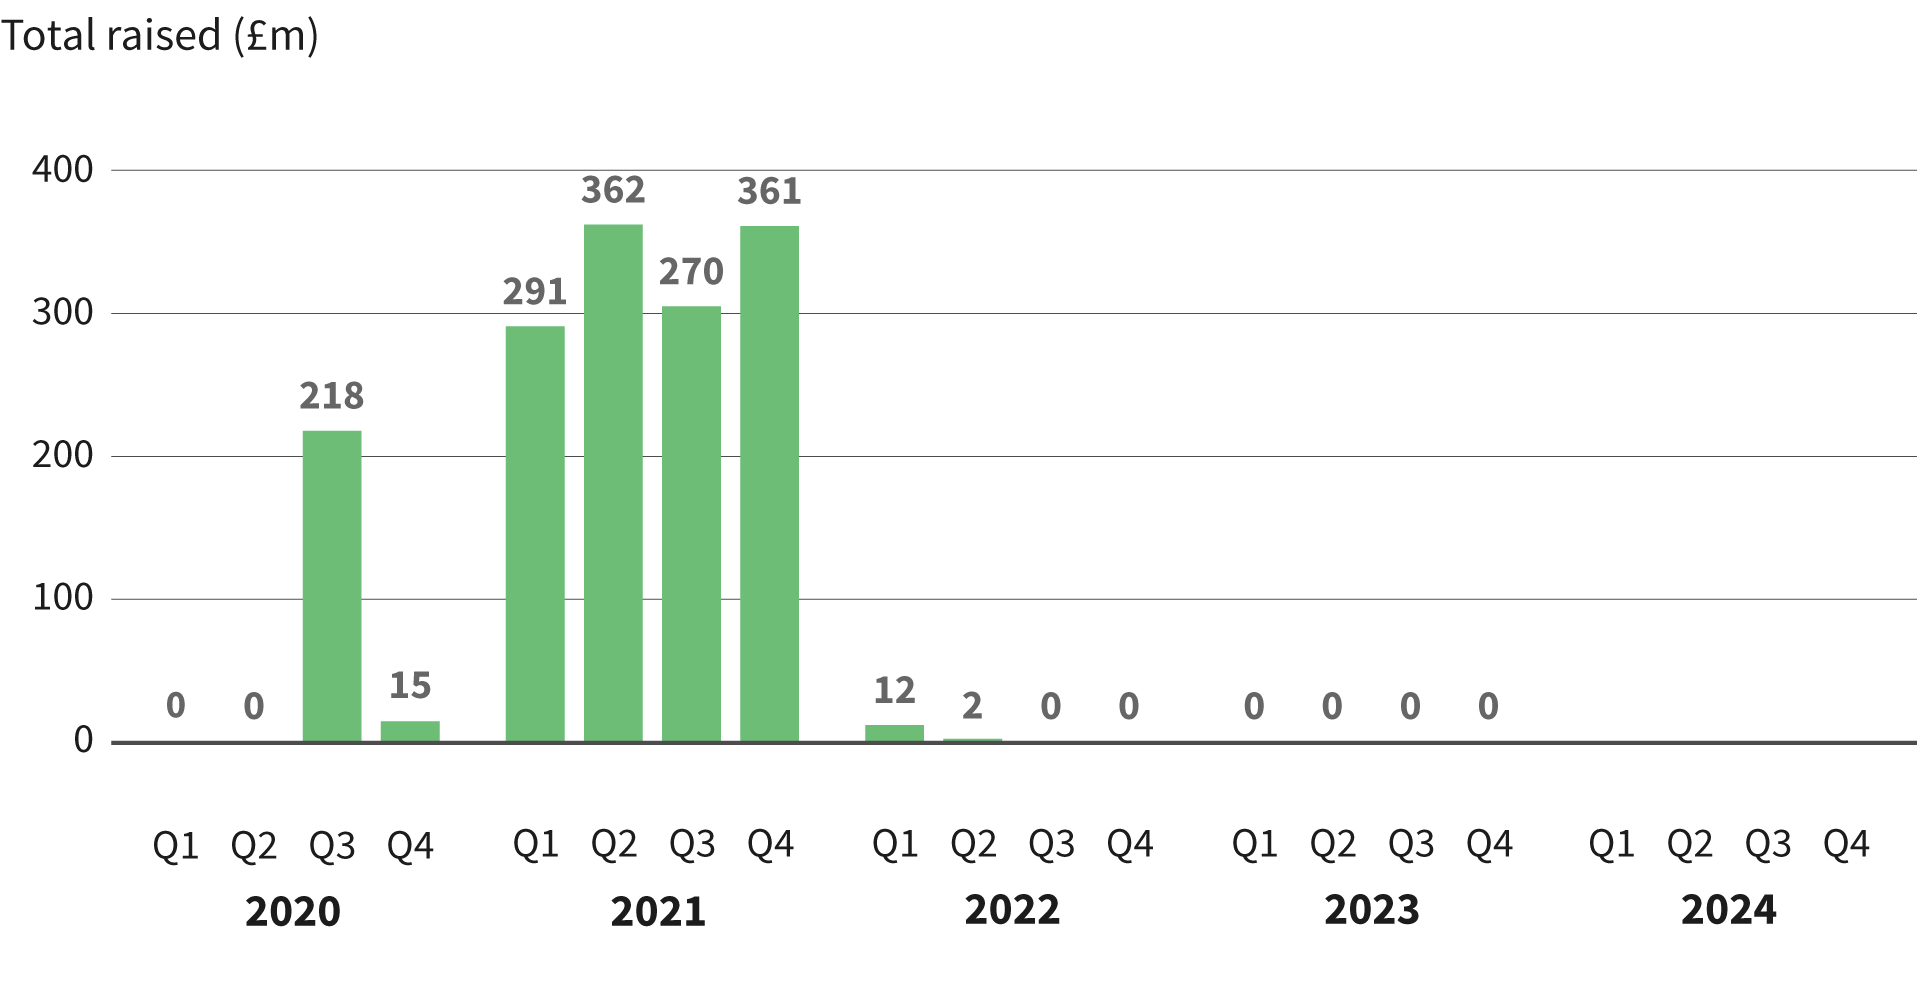
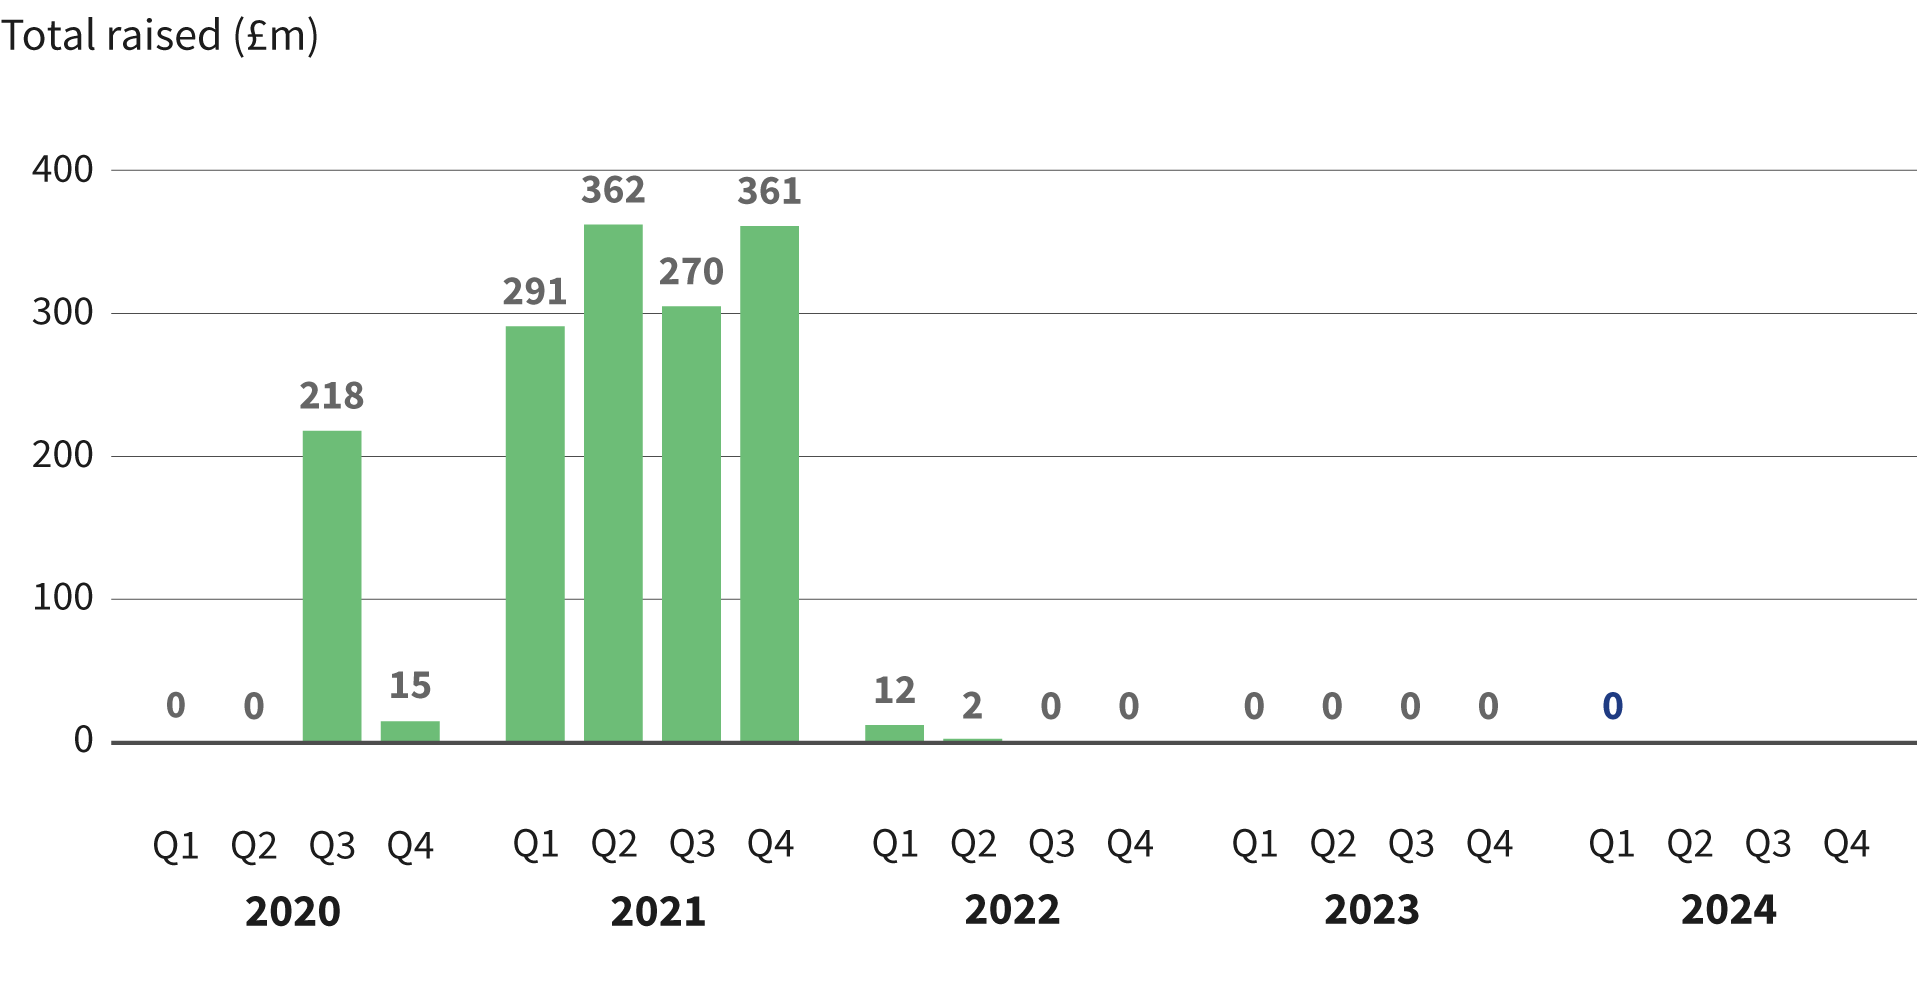
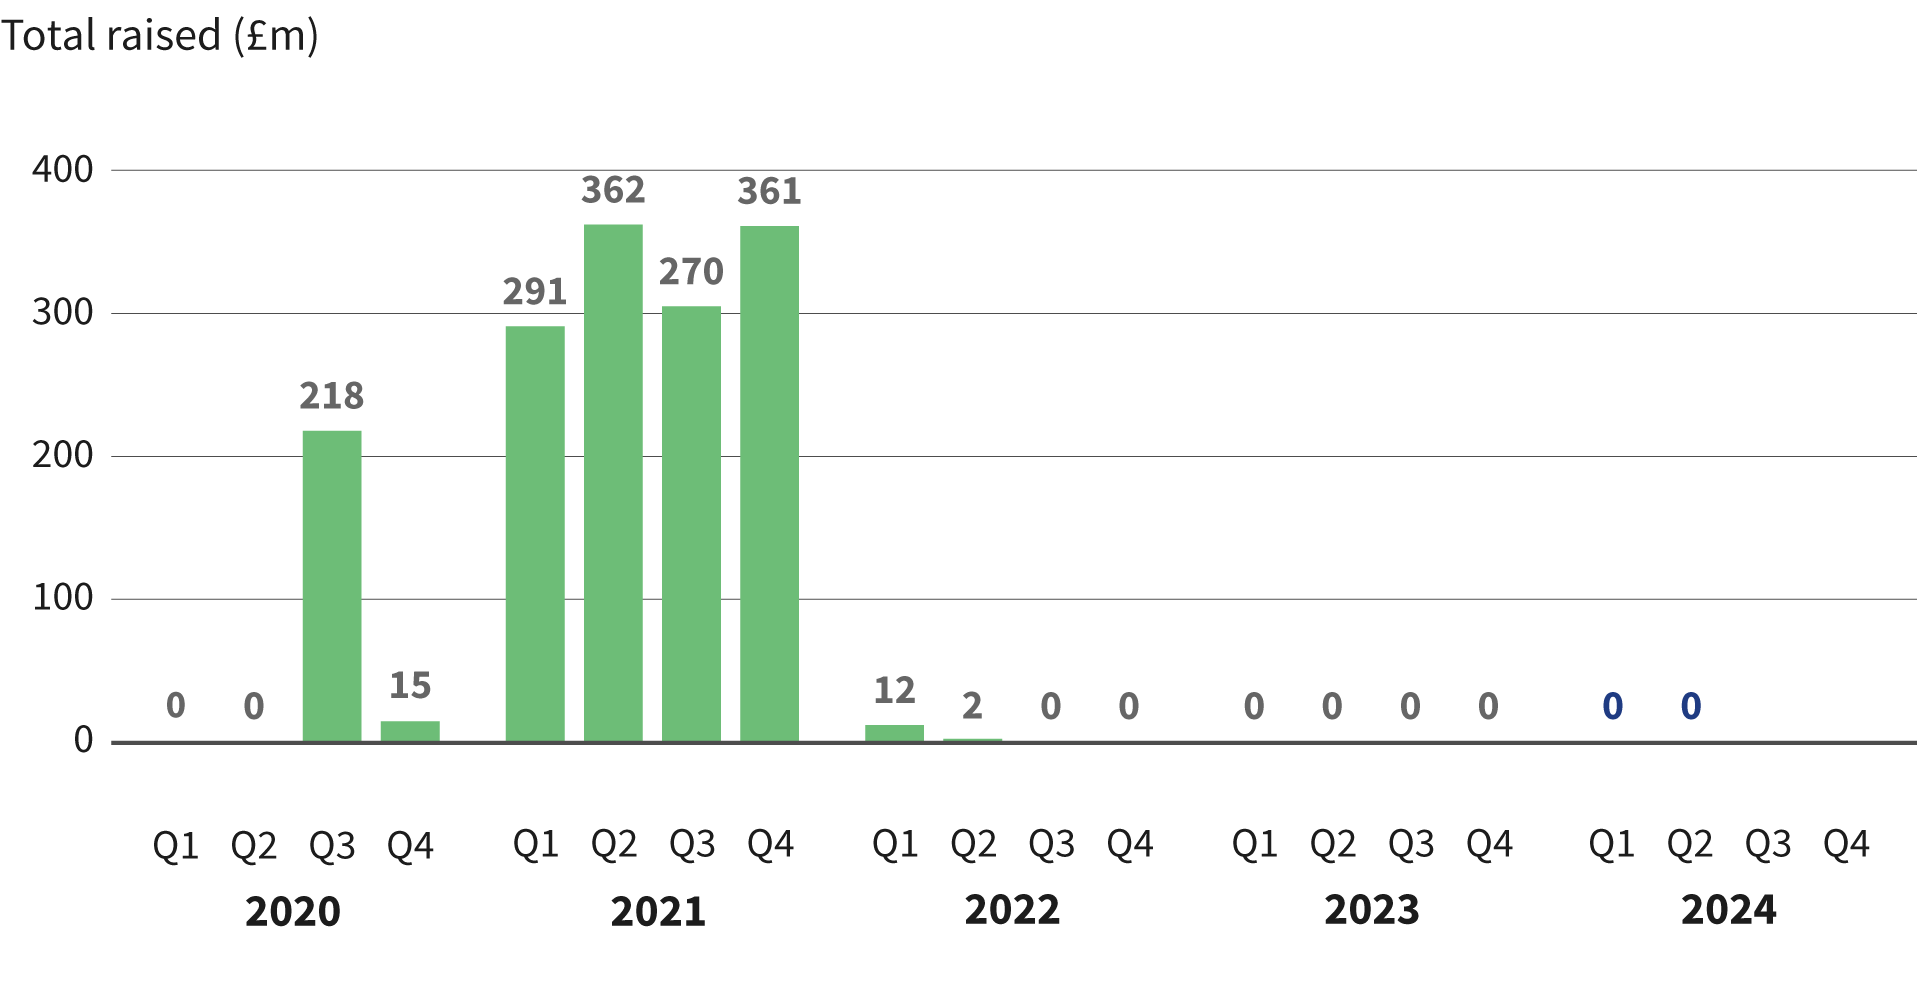
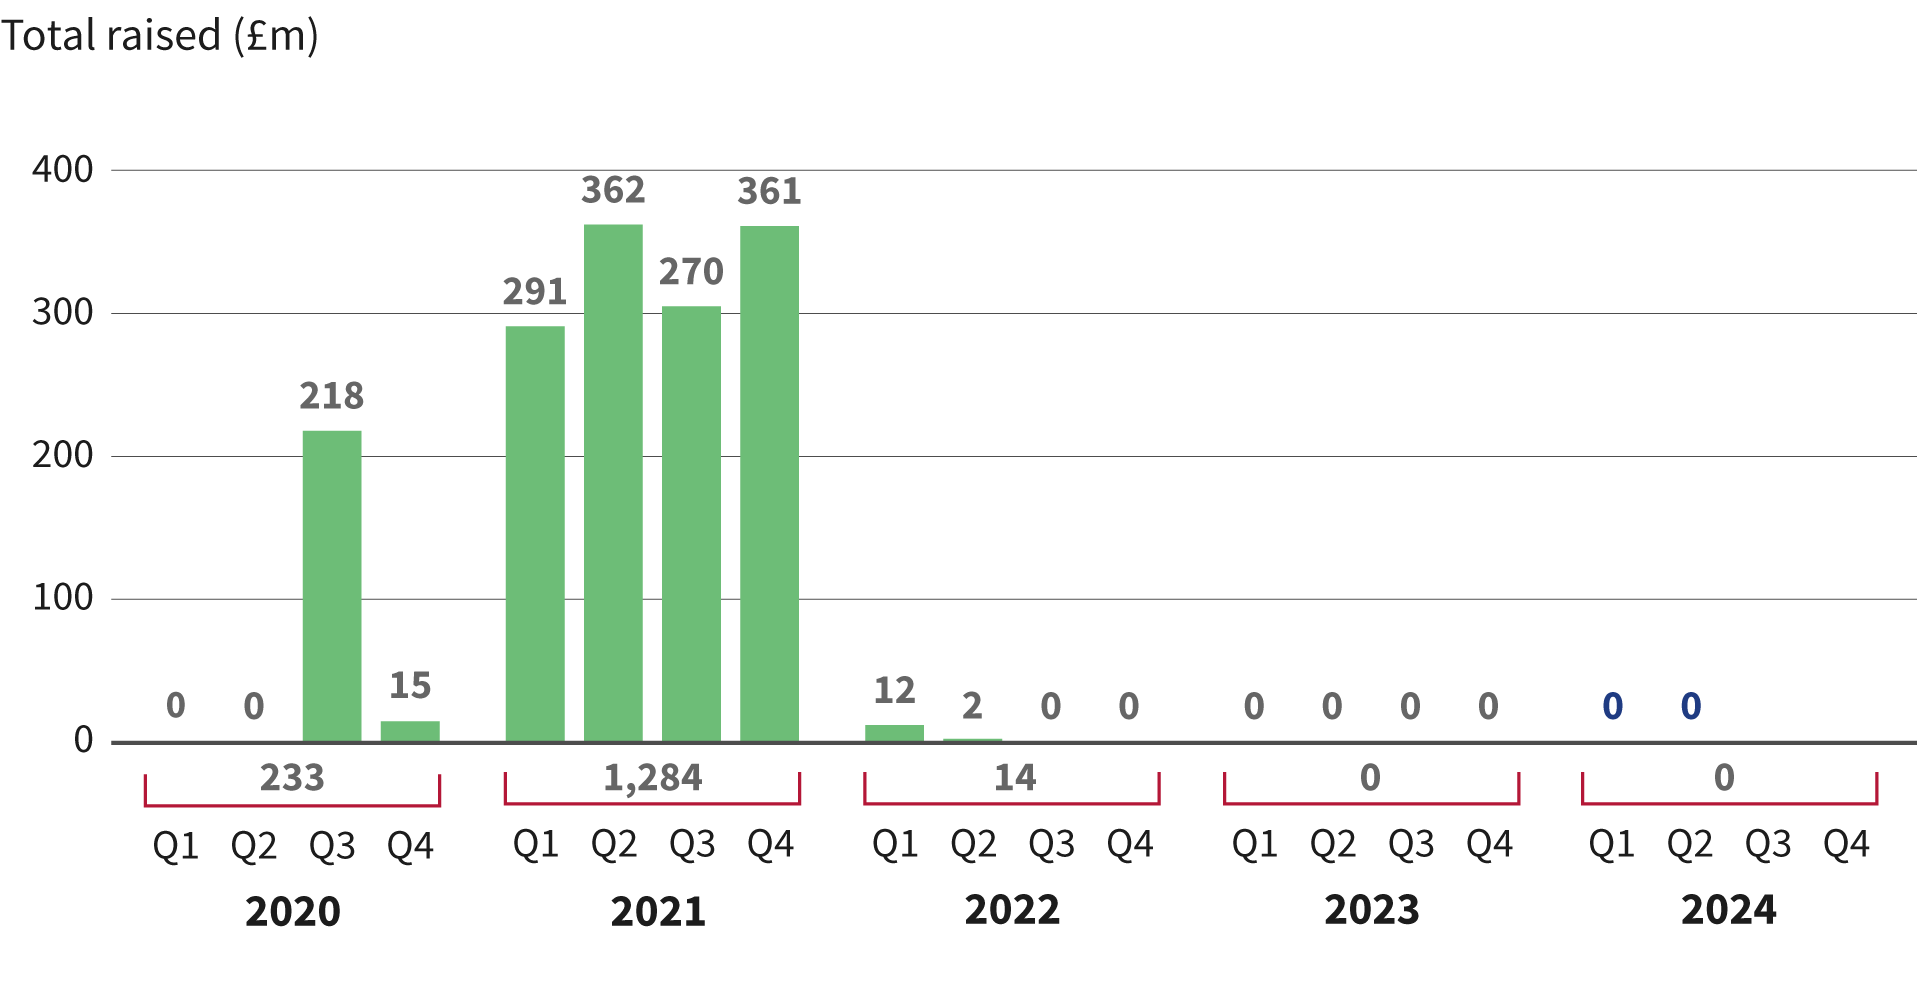
The UK sector entered its eighth consecutive quarter without an IPO as global market conditions continue to put companies off listing.
The Federal Reserve’s and other central banks’ slow action to lower interest rates is partly behind this, as is the looming US Presidential Election. However, it is notable that several UK biotech’s have chosen to delist from the London Stock Exchange in the first half of this year, citing better fundraising prospects in the private market.
Total raised in IPO by quarter, for the past five years
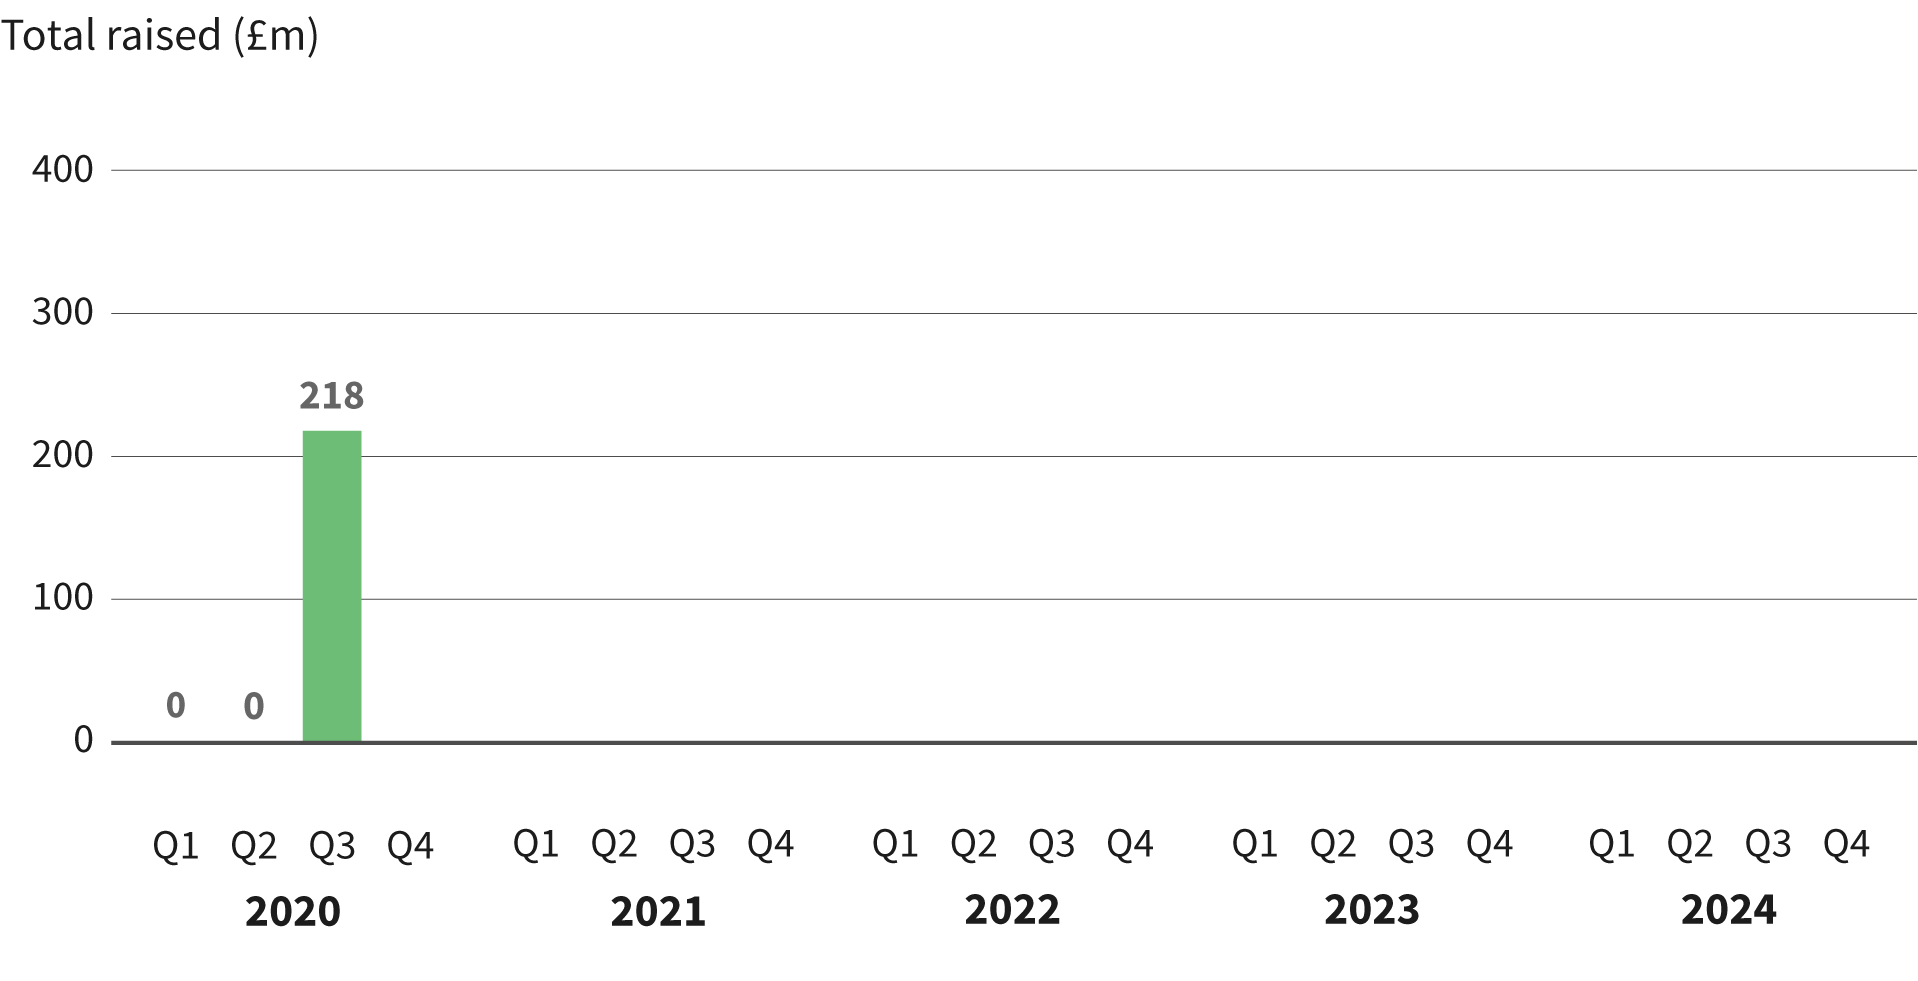
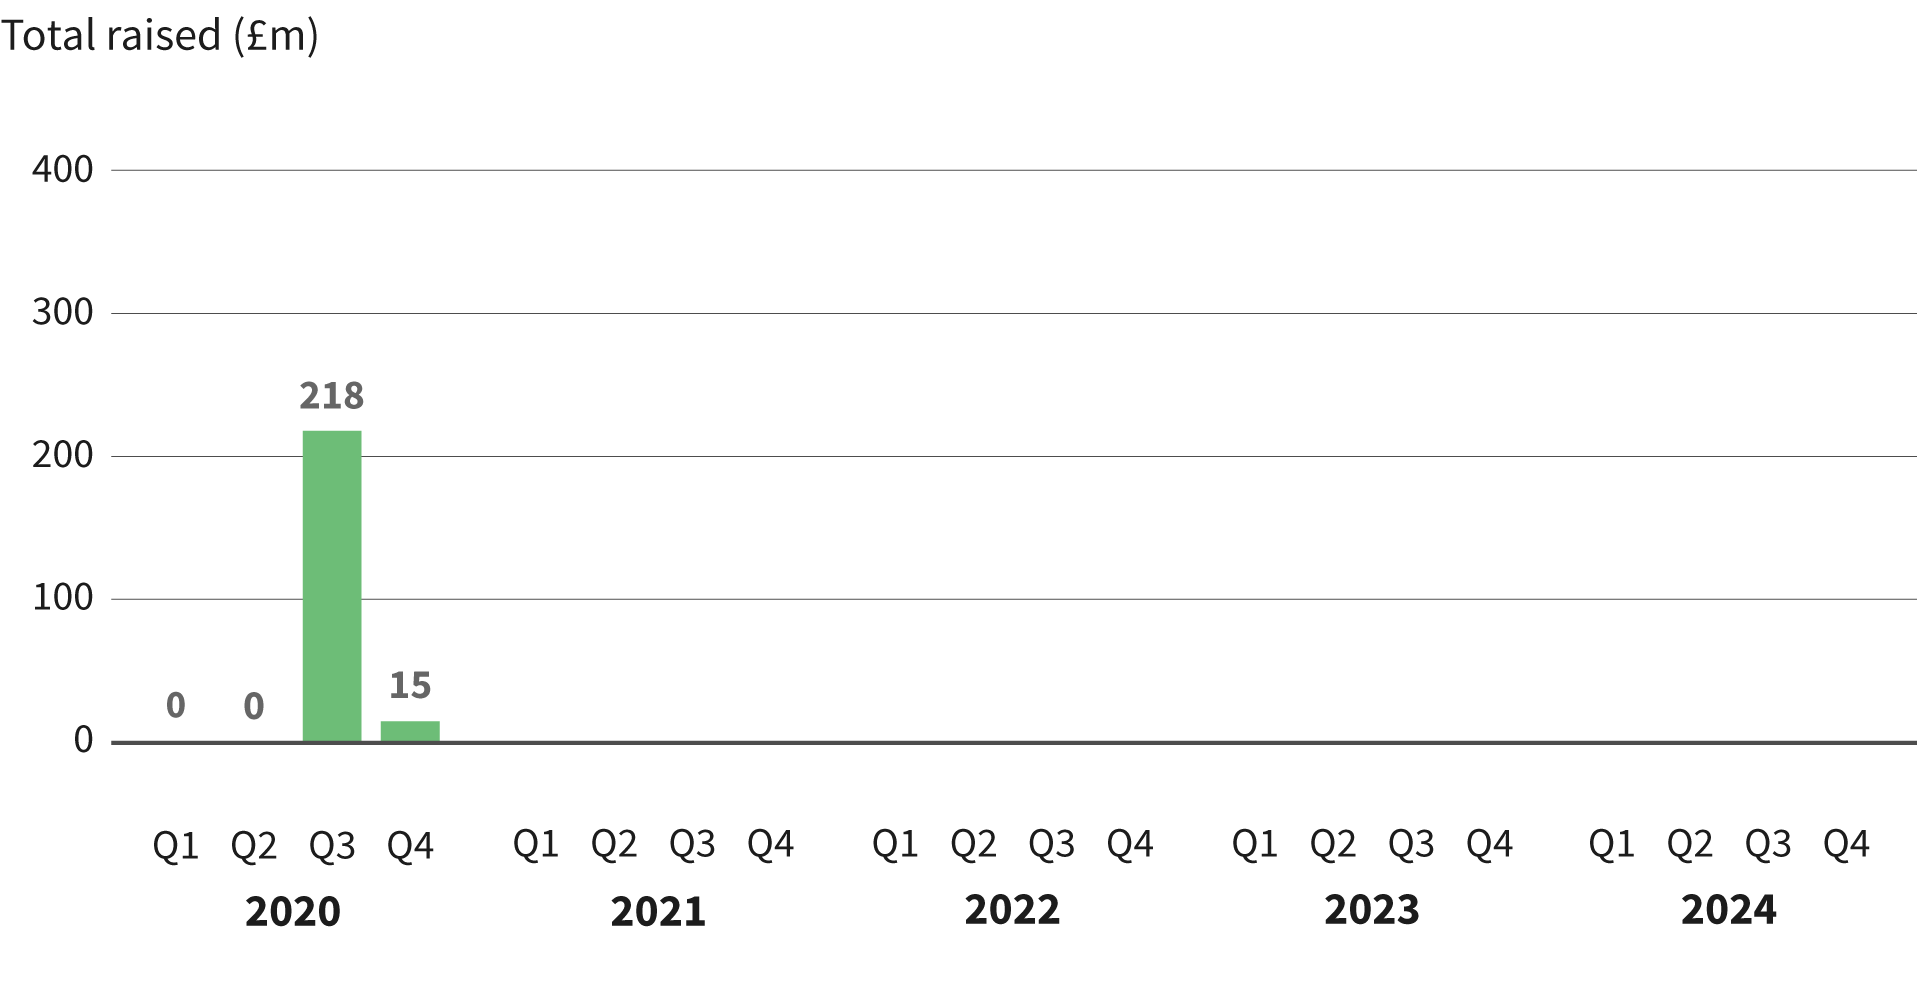
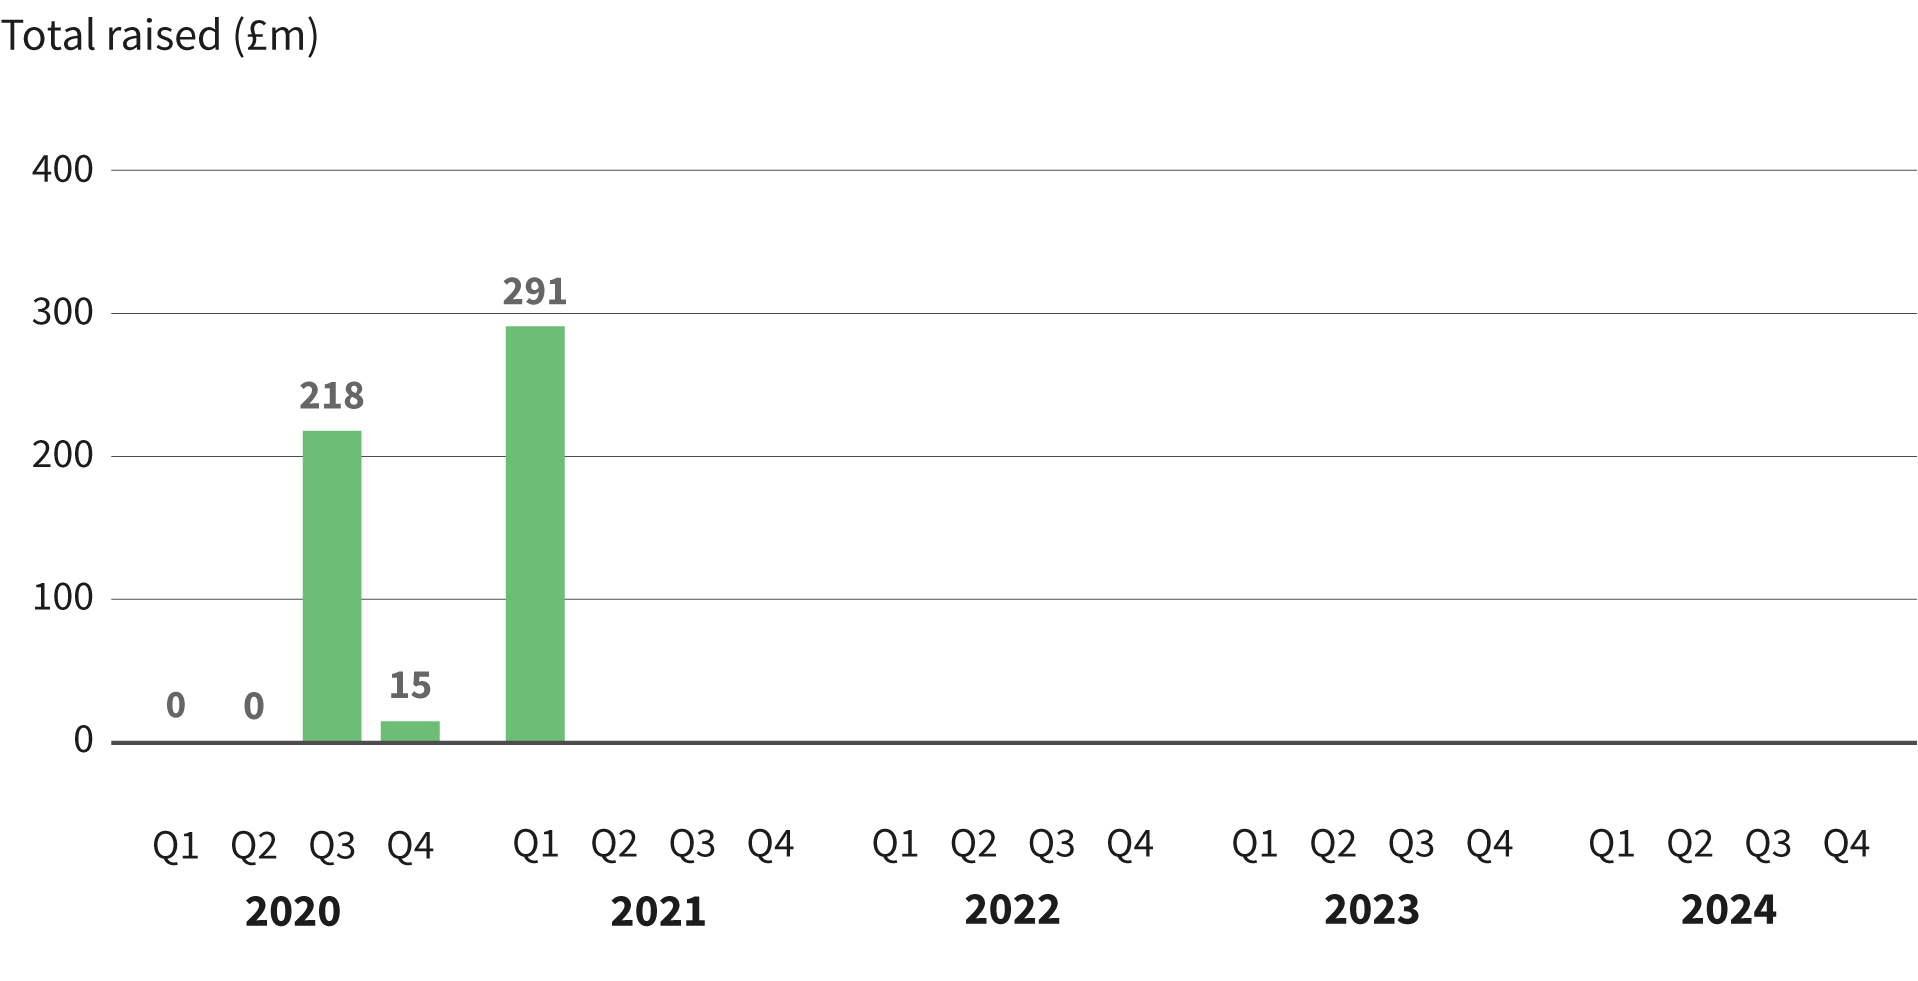
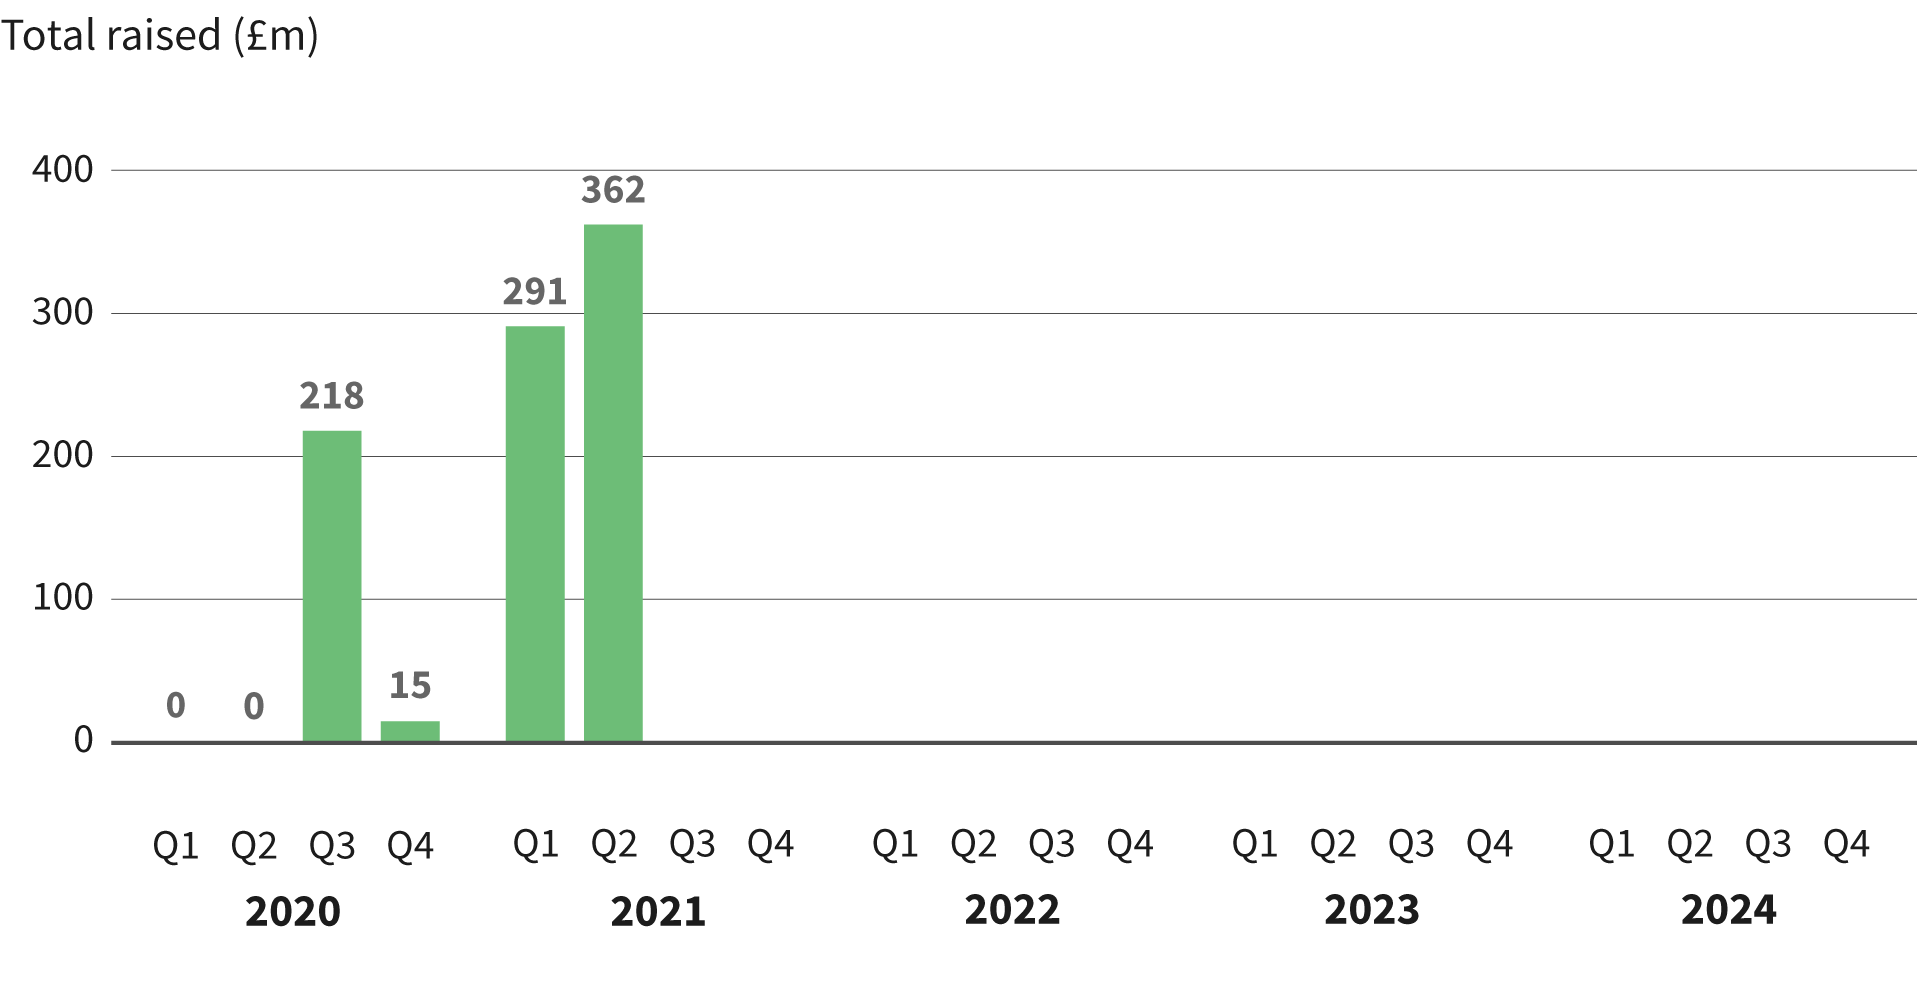
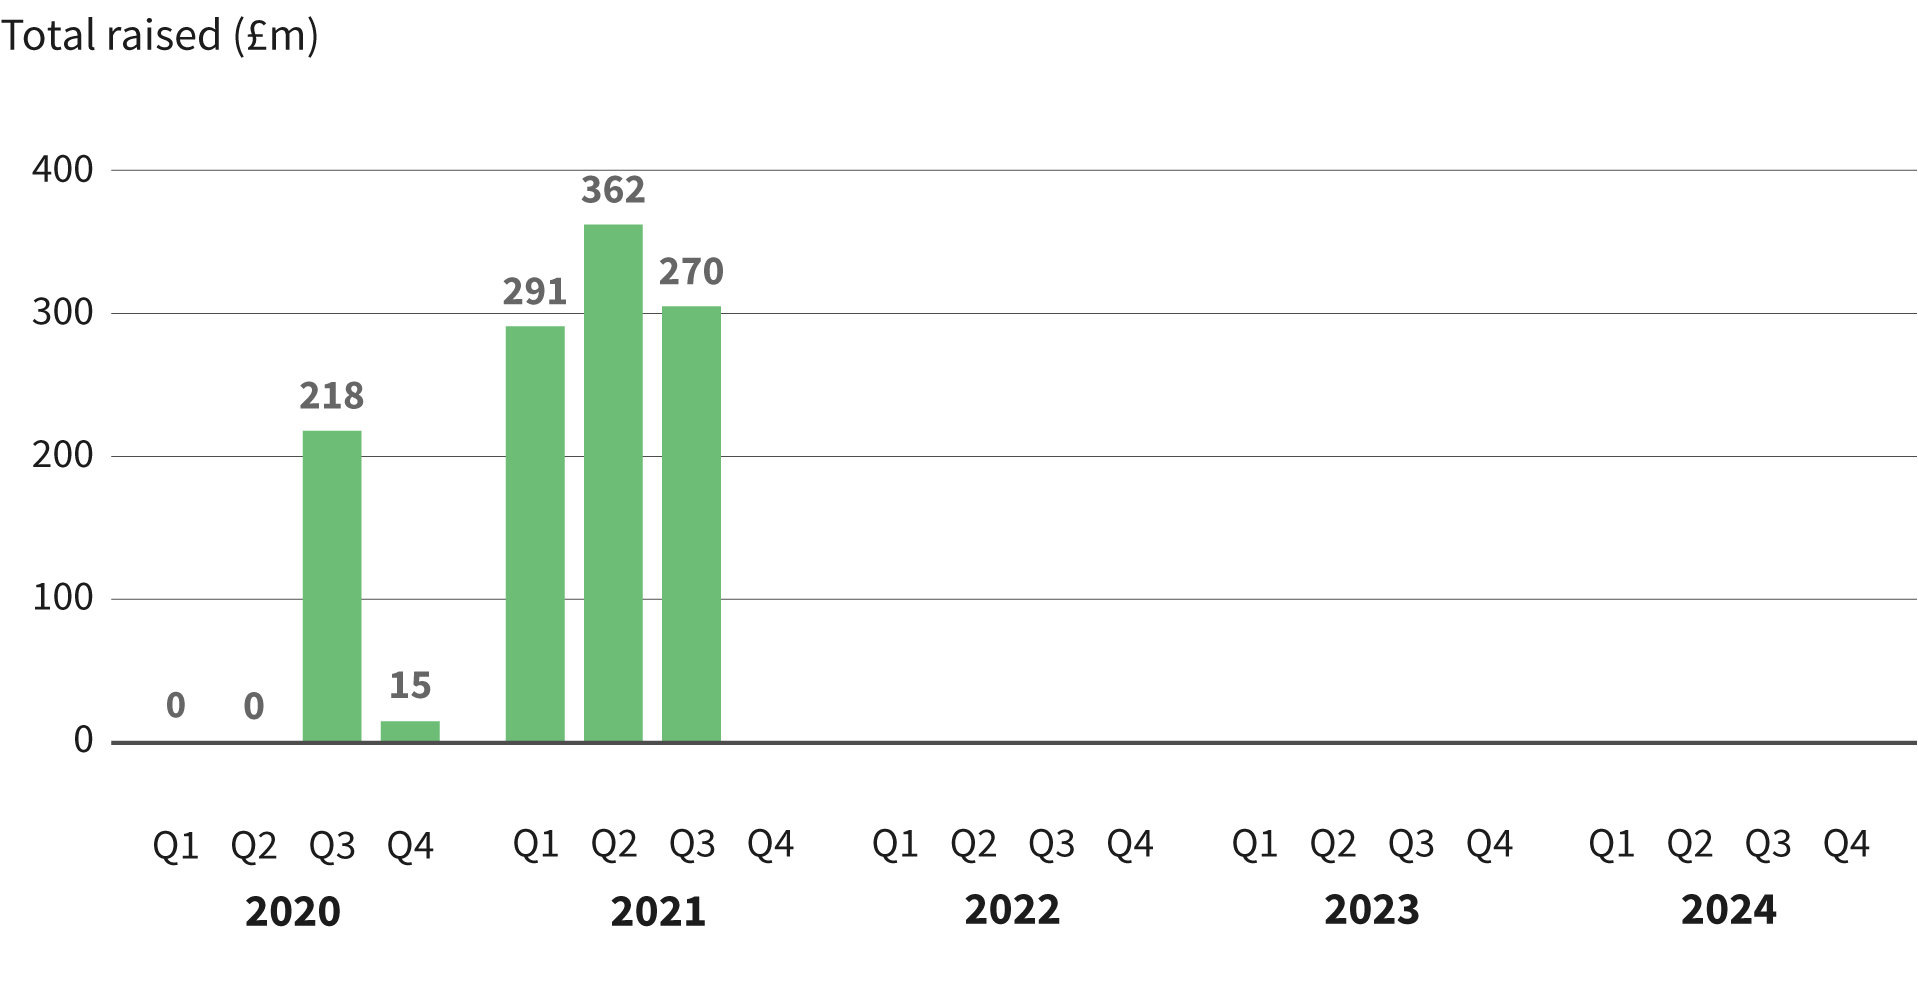
International IPOs
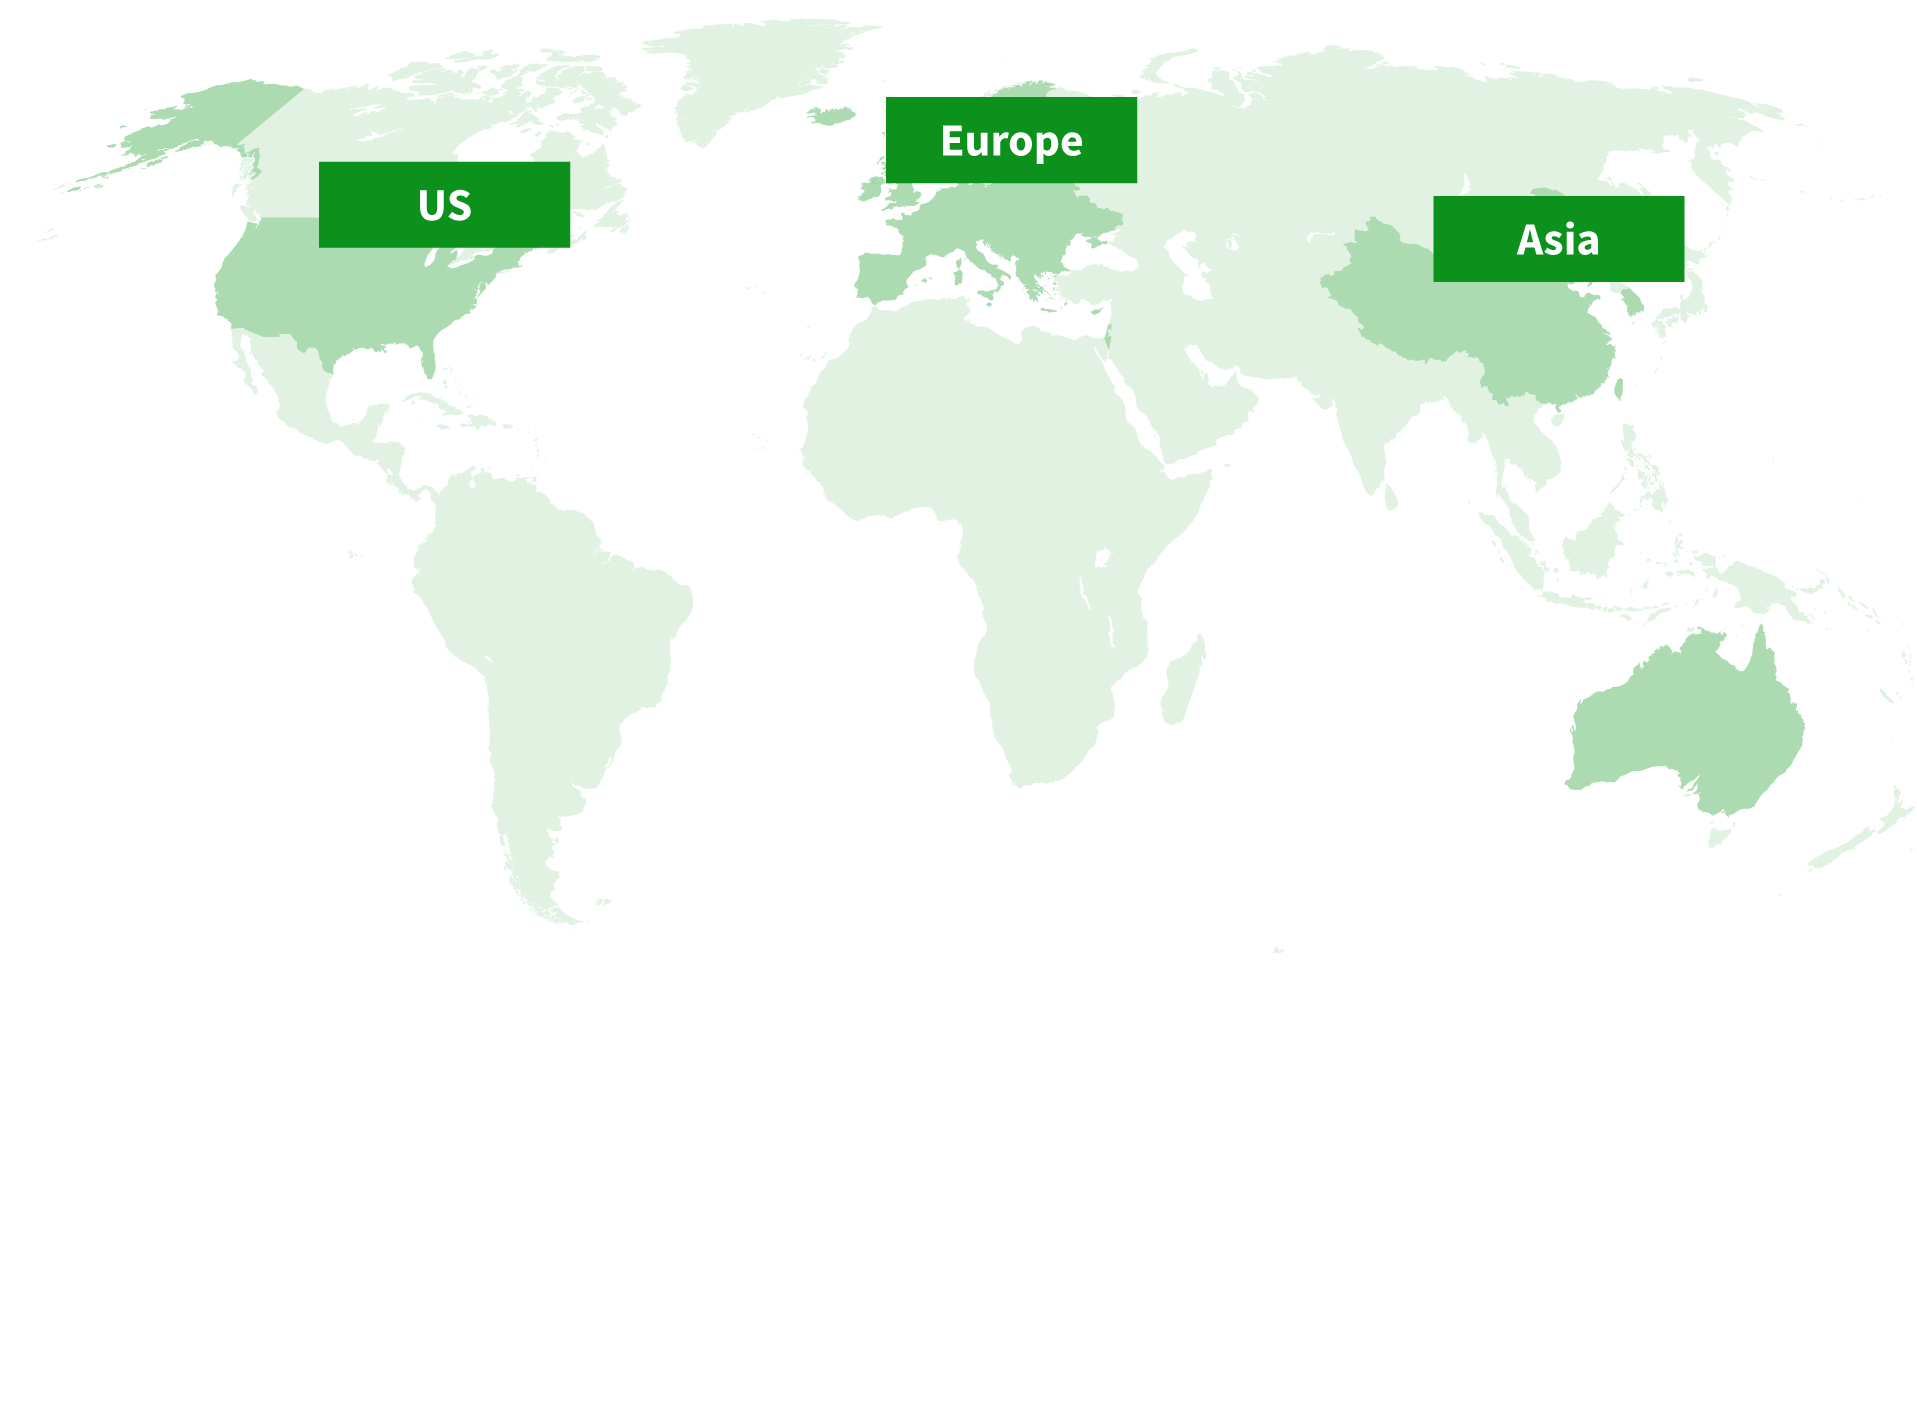
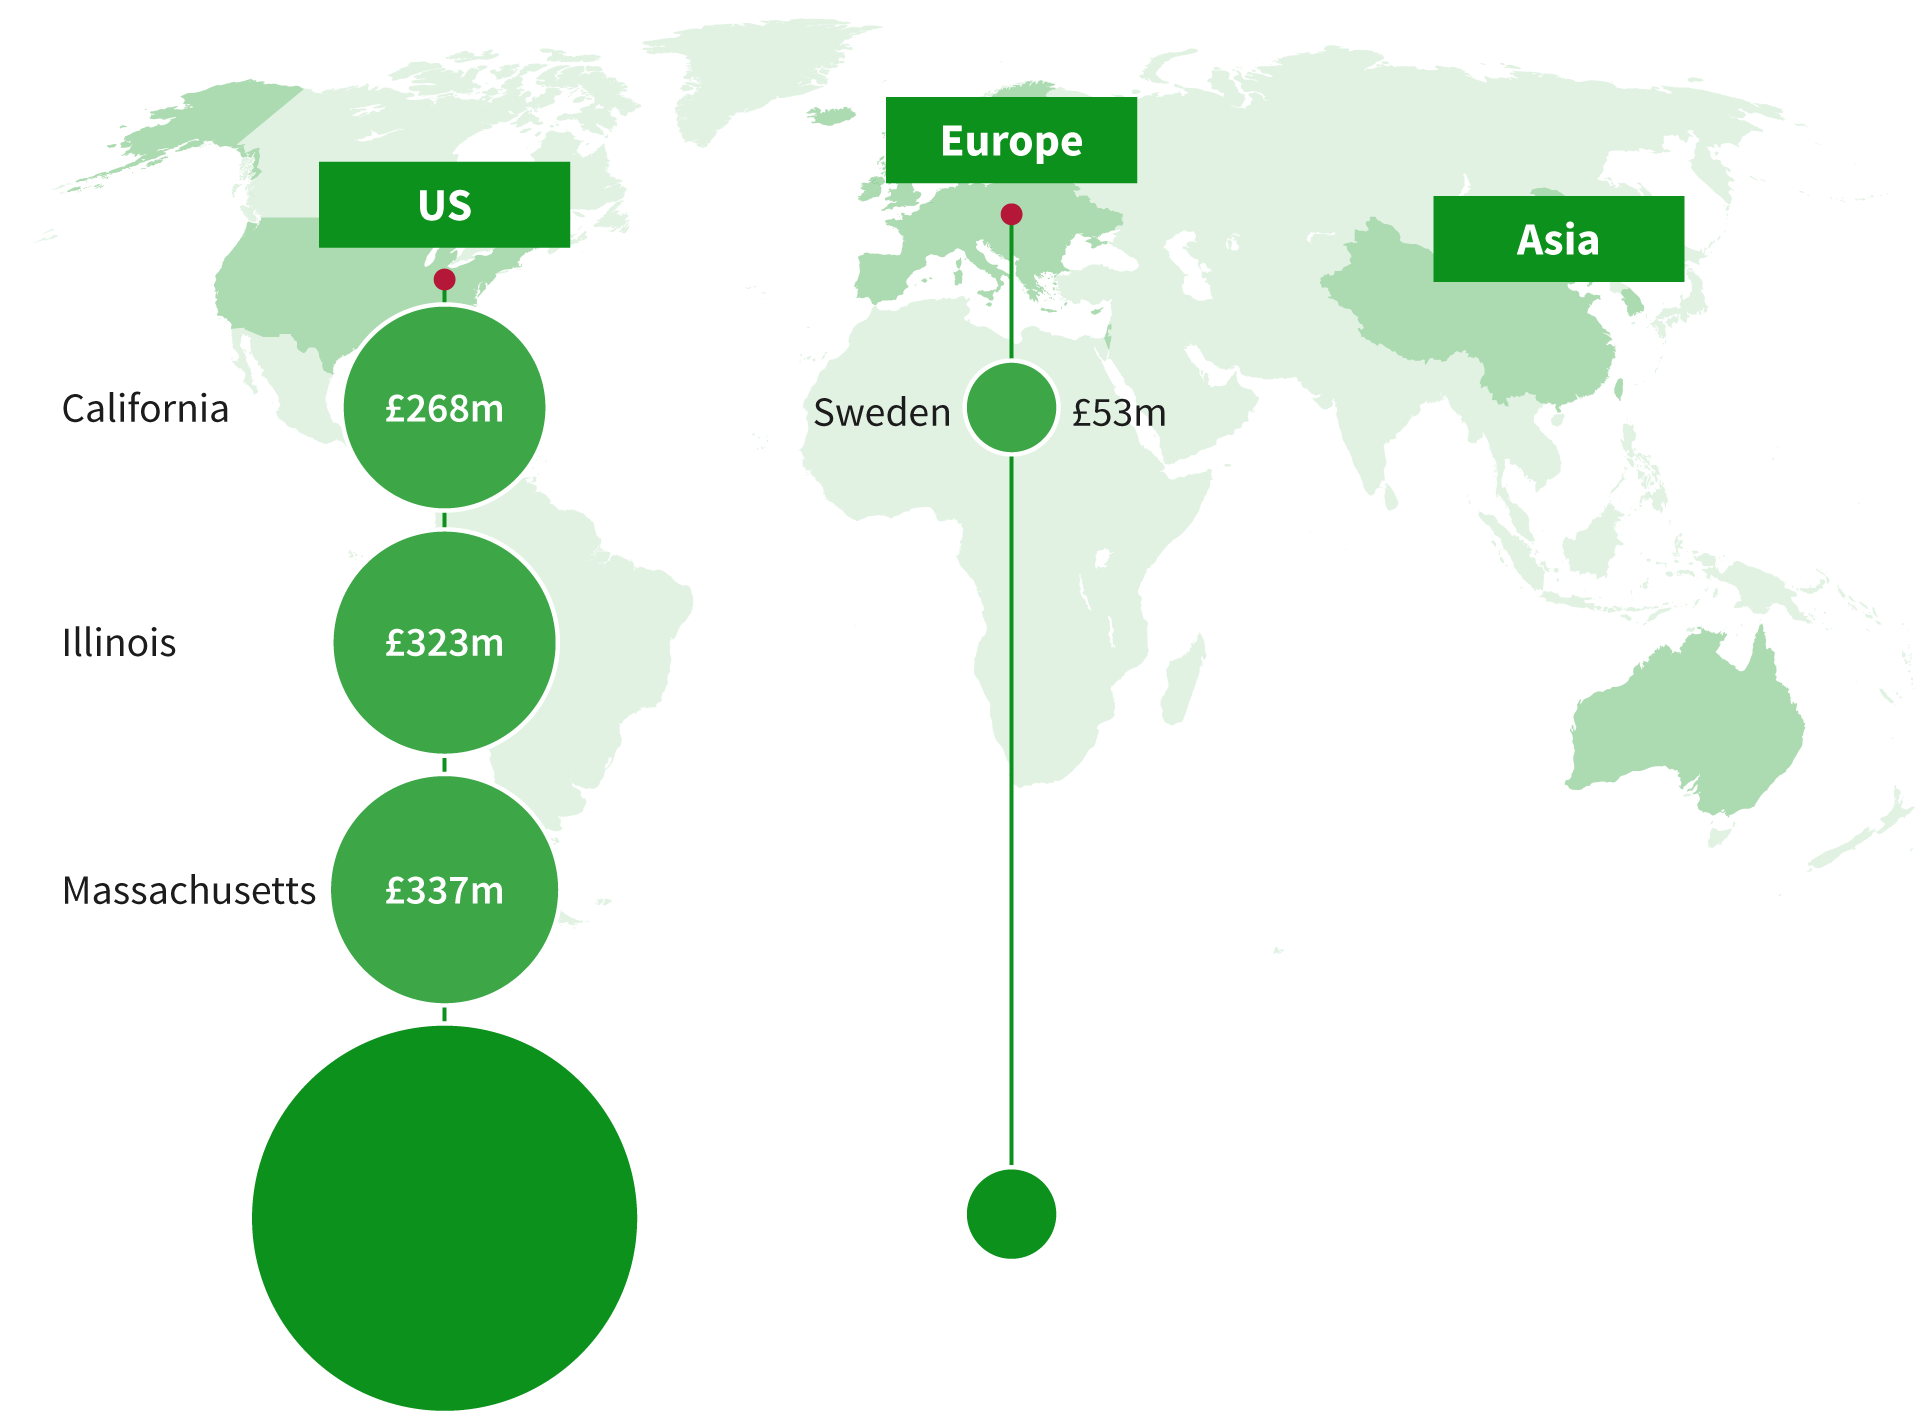
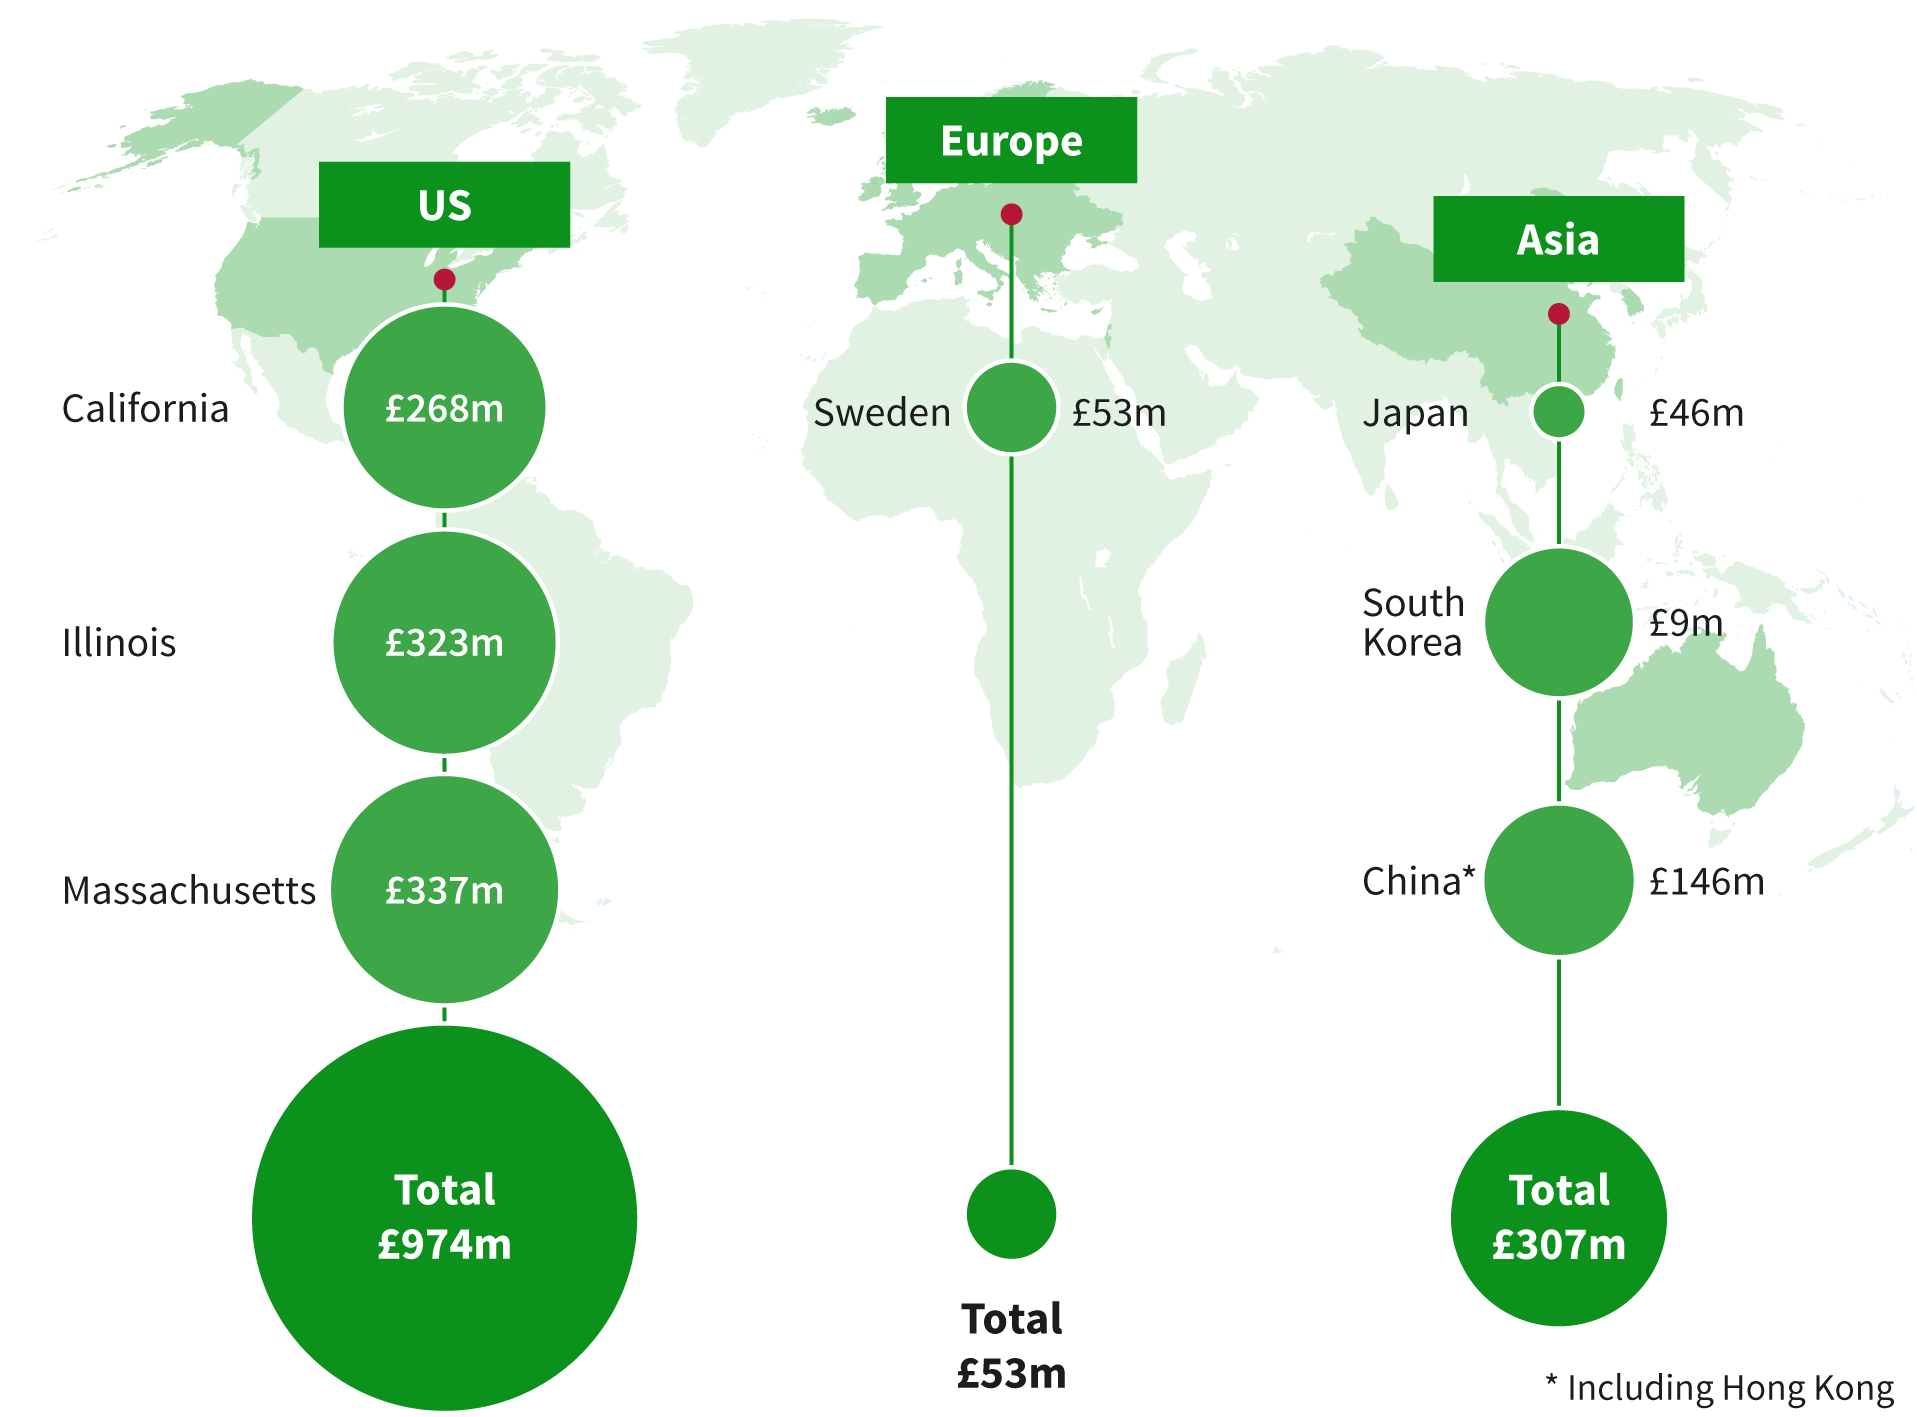
Low IPO activity has not just been a UK trend, with many countries also registering no new launches. The European IPO market only saw one in Q2 of this year, with Sweden’s Cinclus Pharma raising £53 million.
In the US, six launches collectively raised £974 million, a 110% decrease from the previous quarter. Asia saw a significant increase, with the market rising from £4 million to £307 million over the last quarter.
Follow-on financings
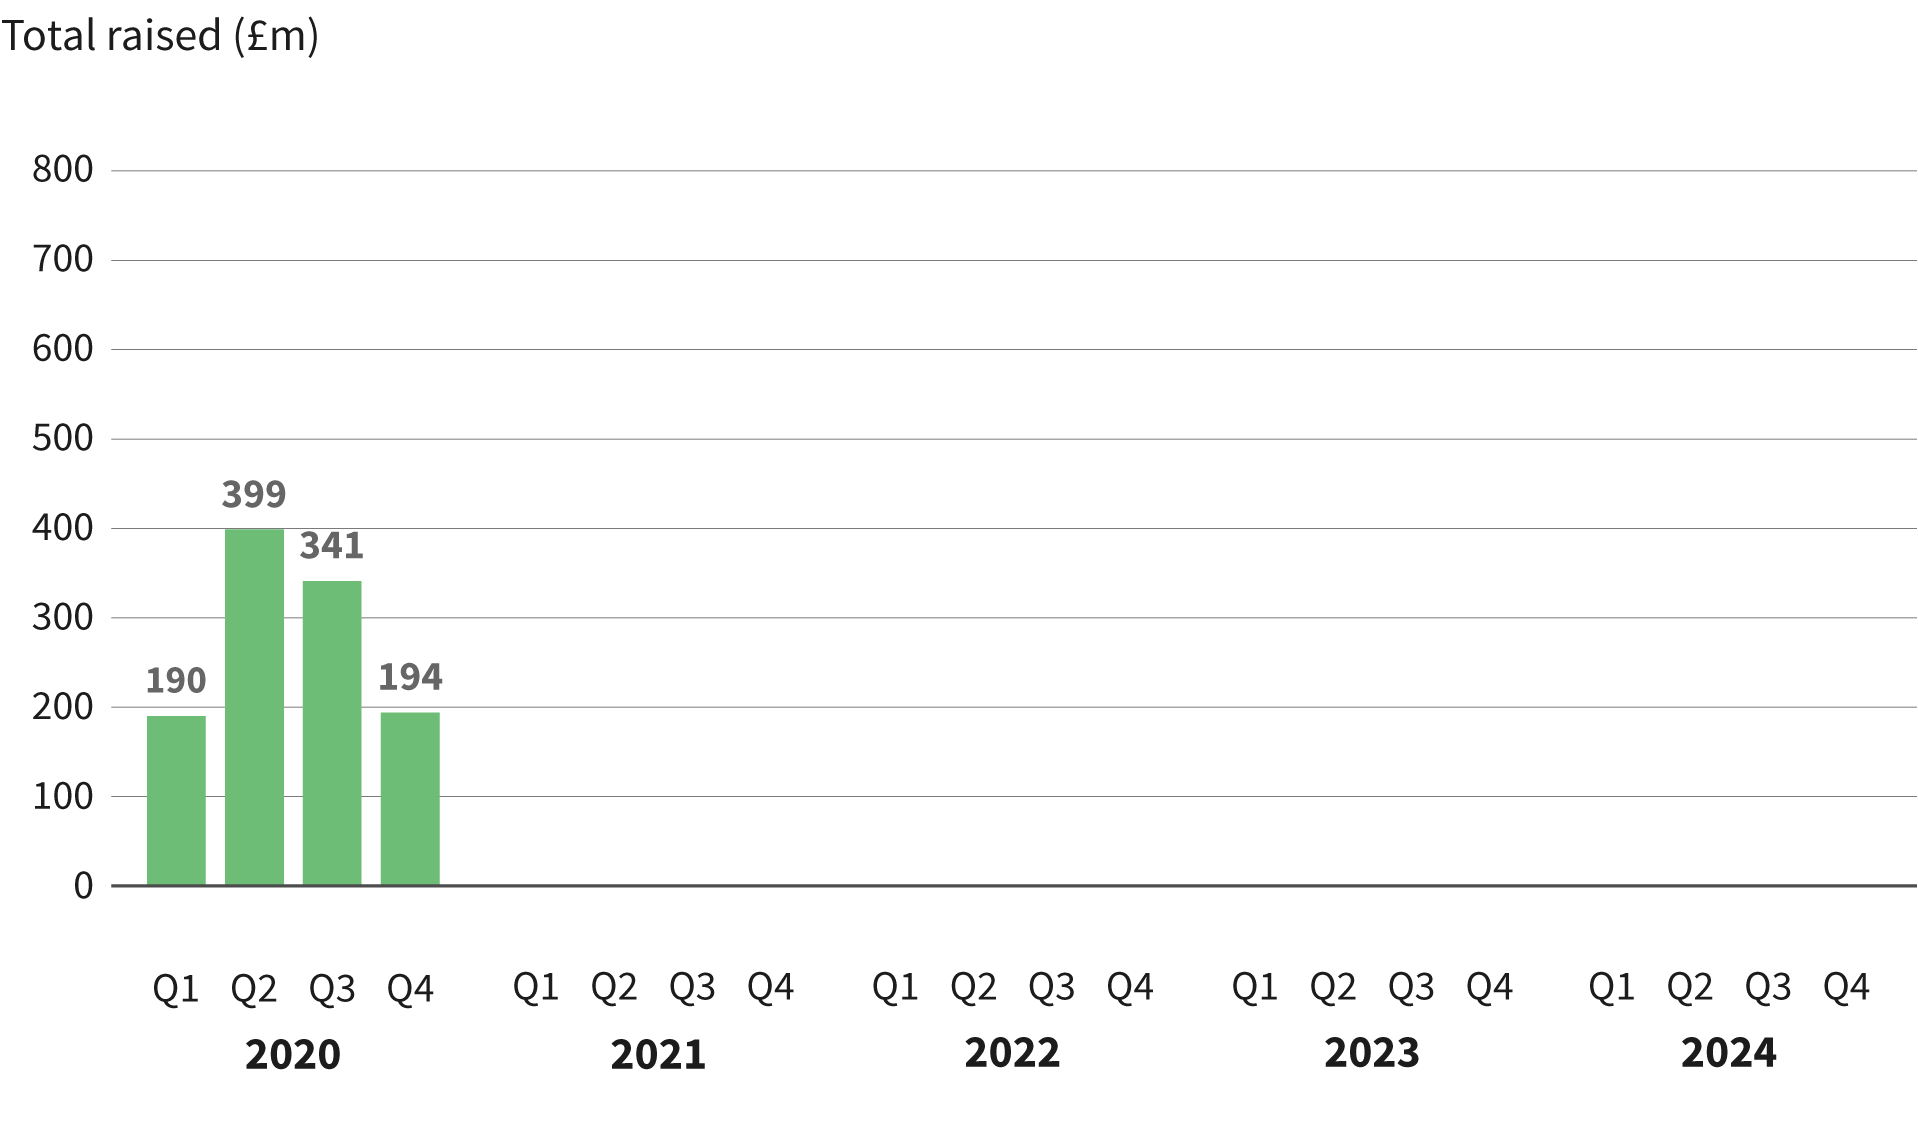
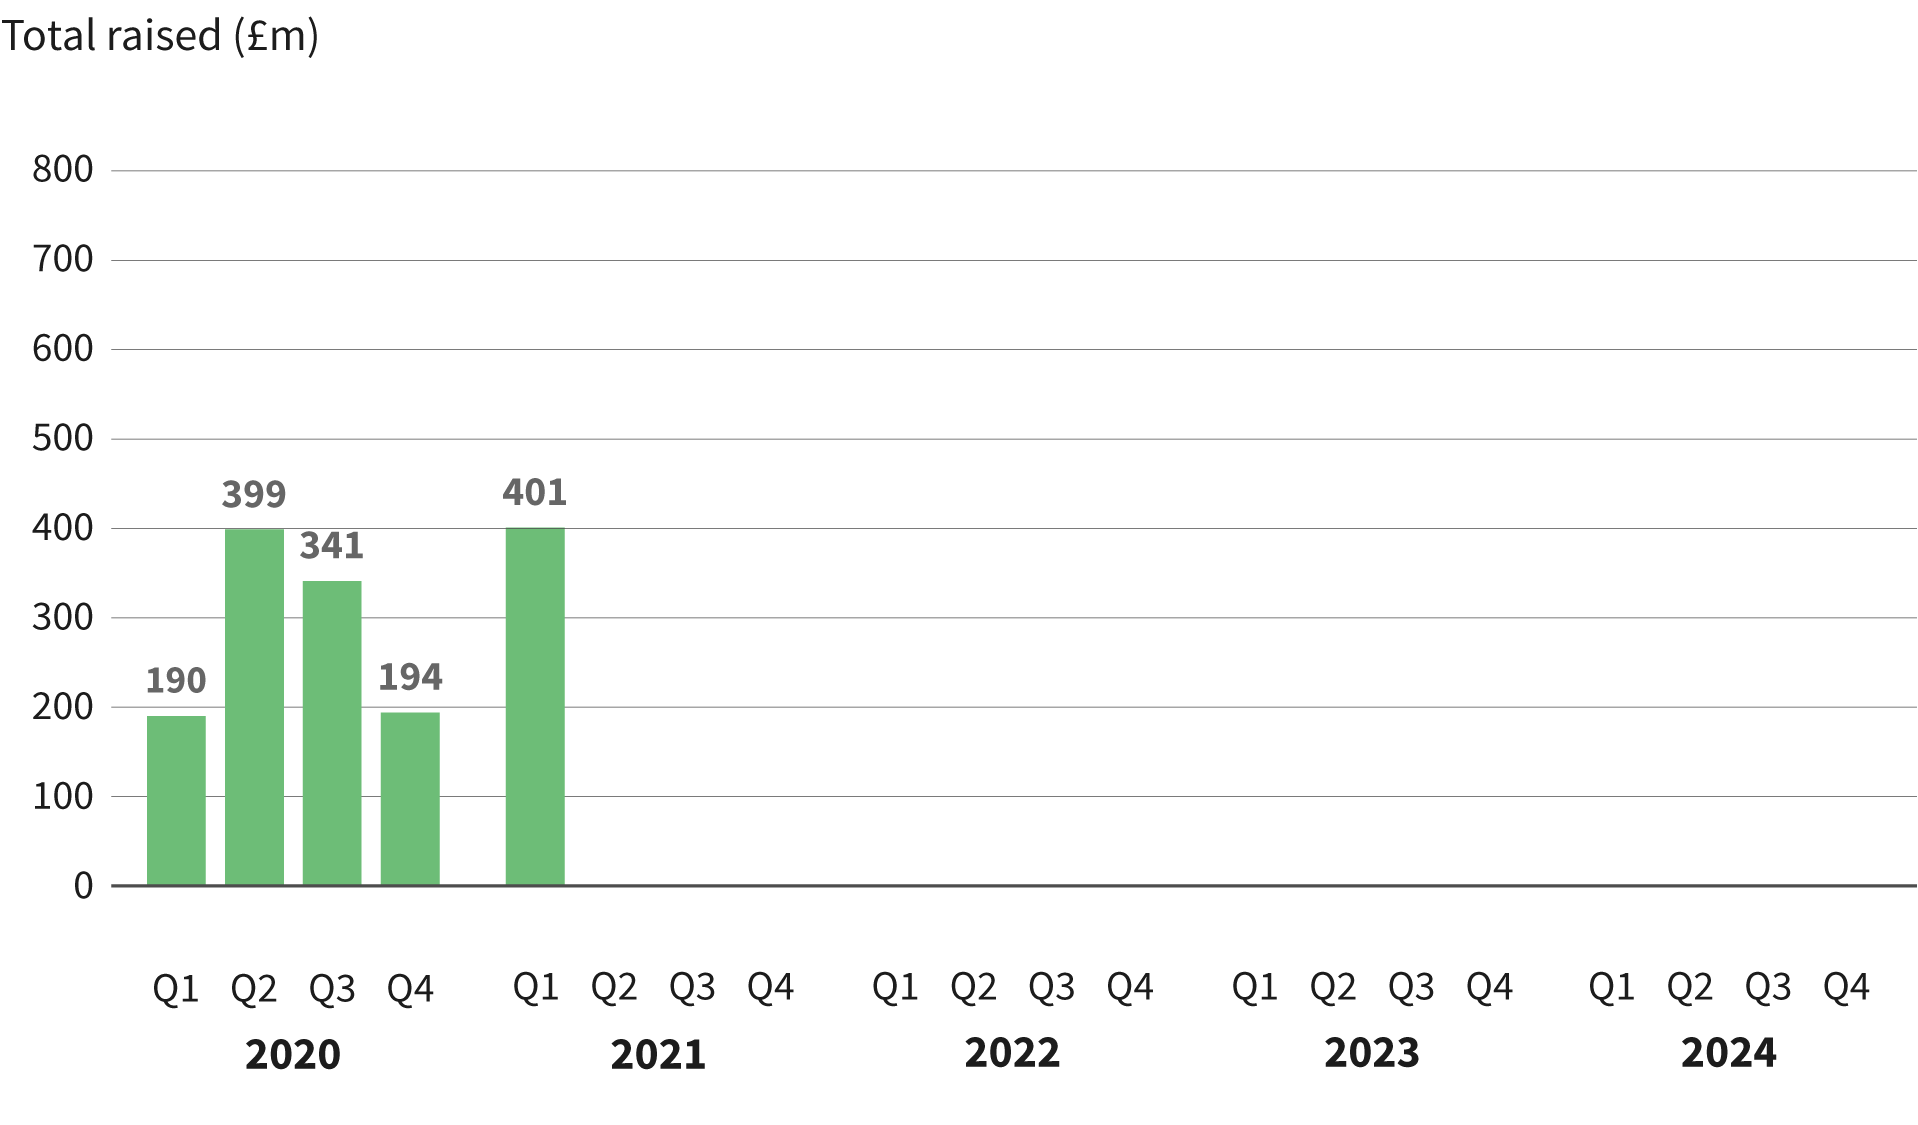
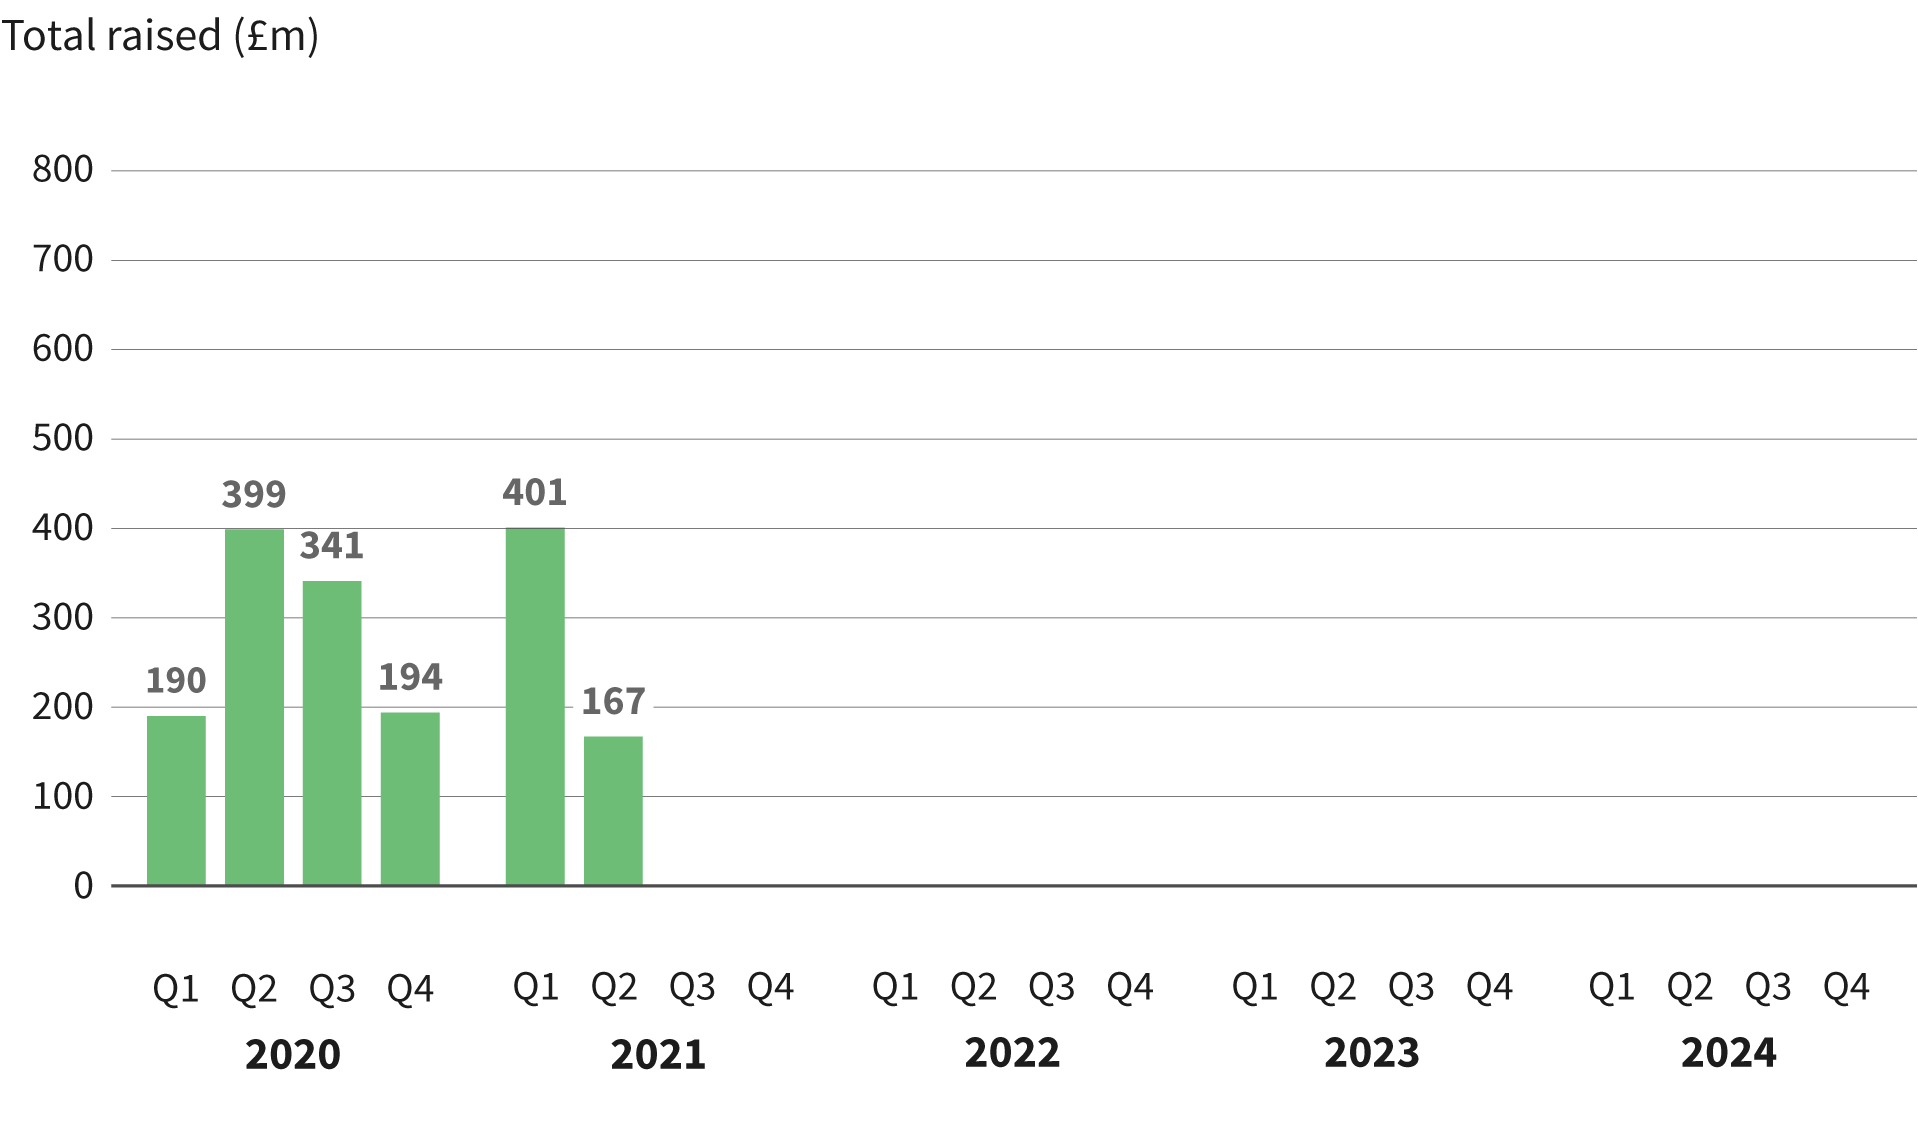
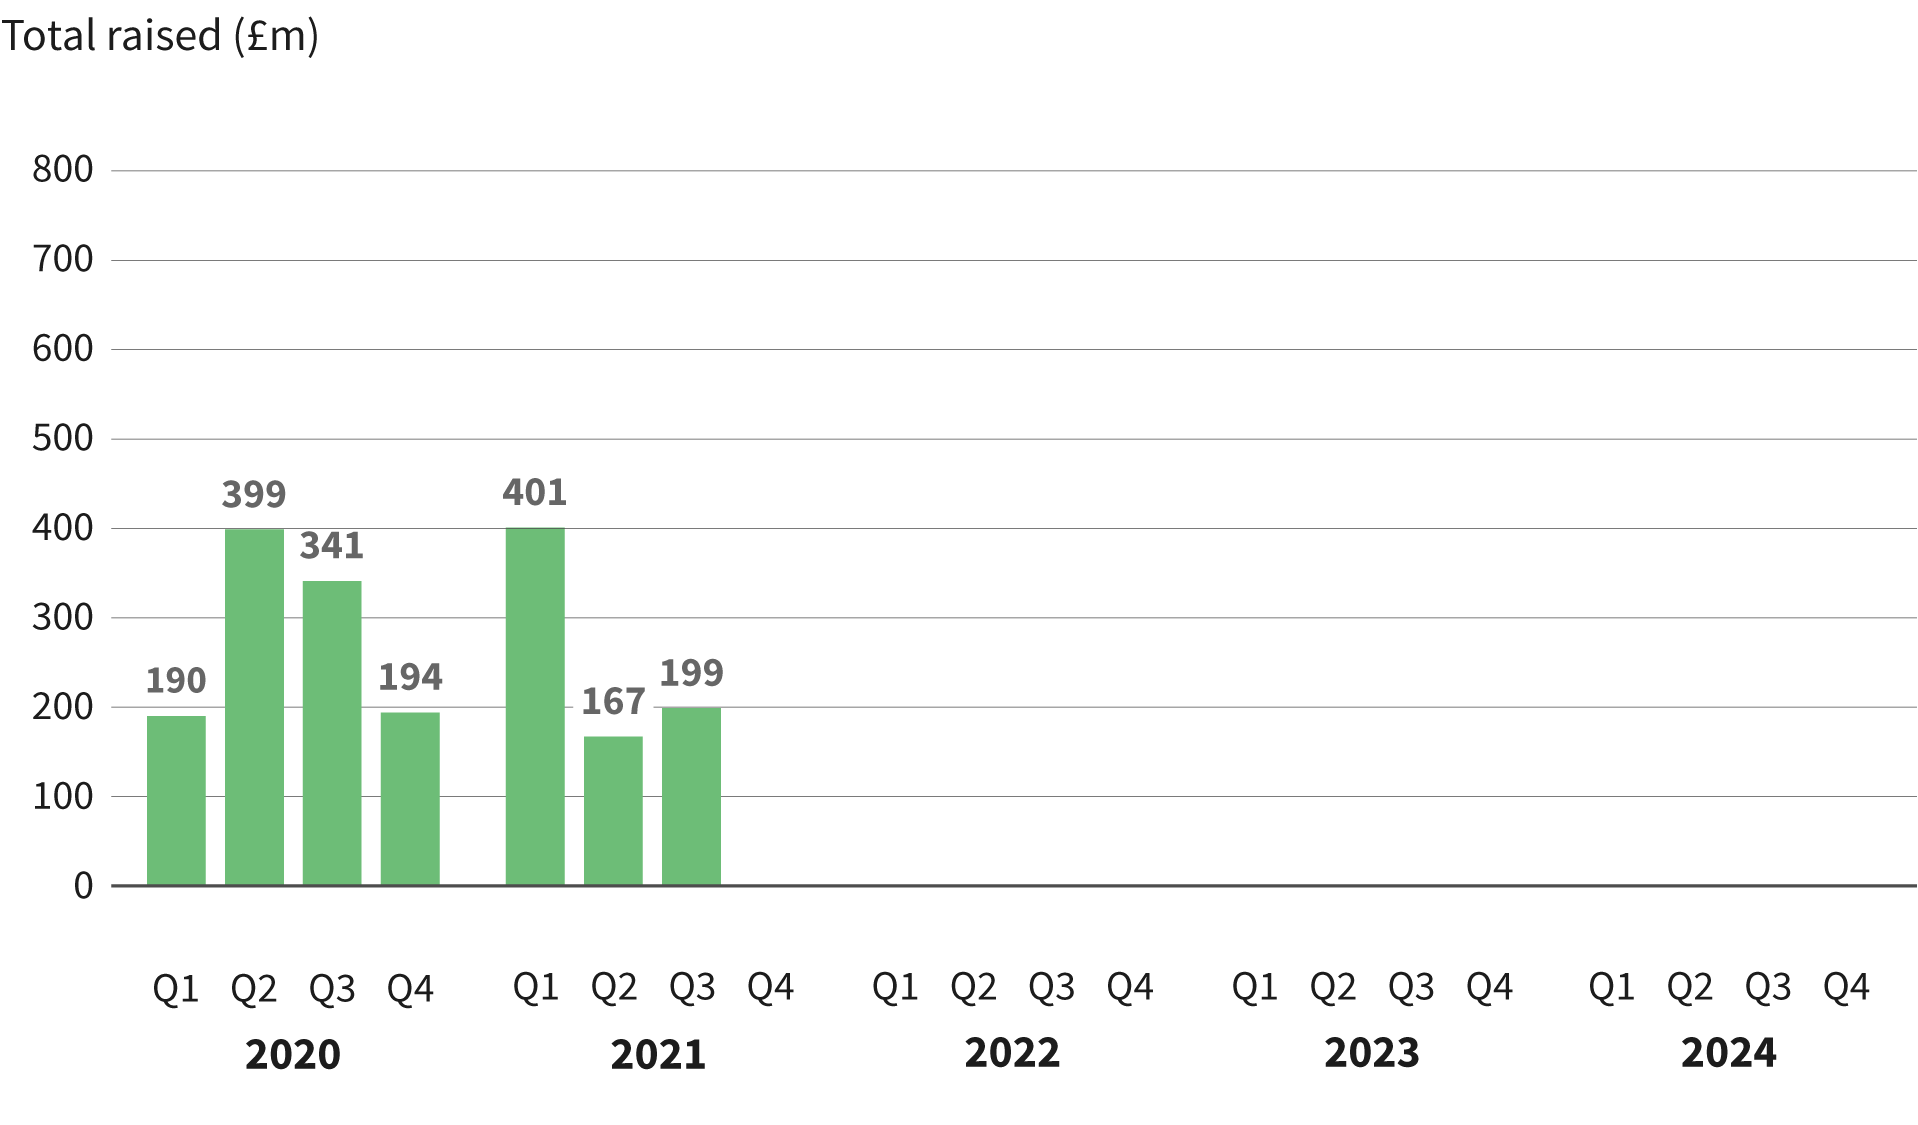
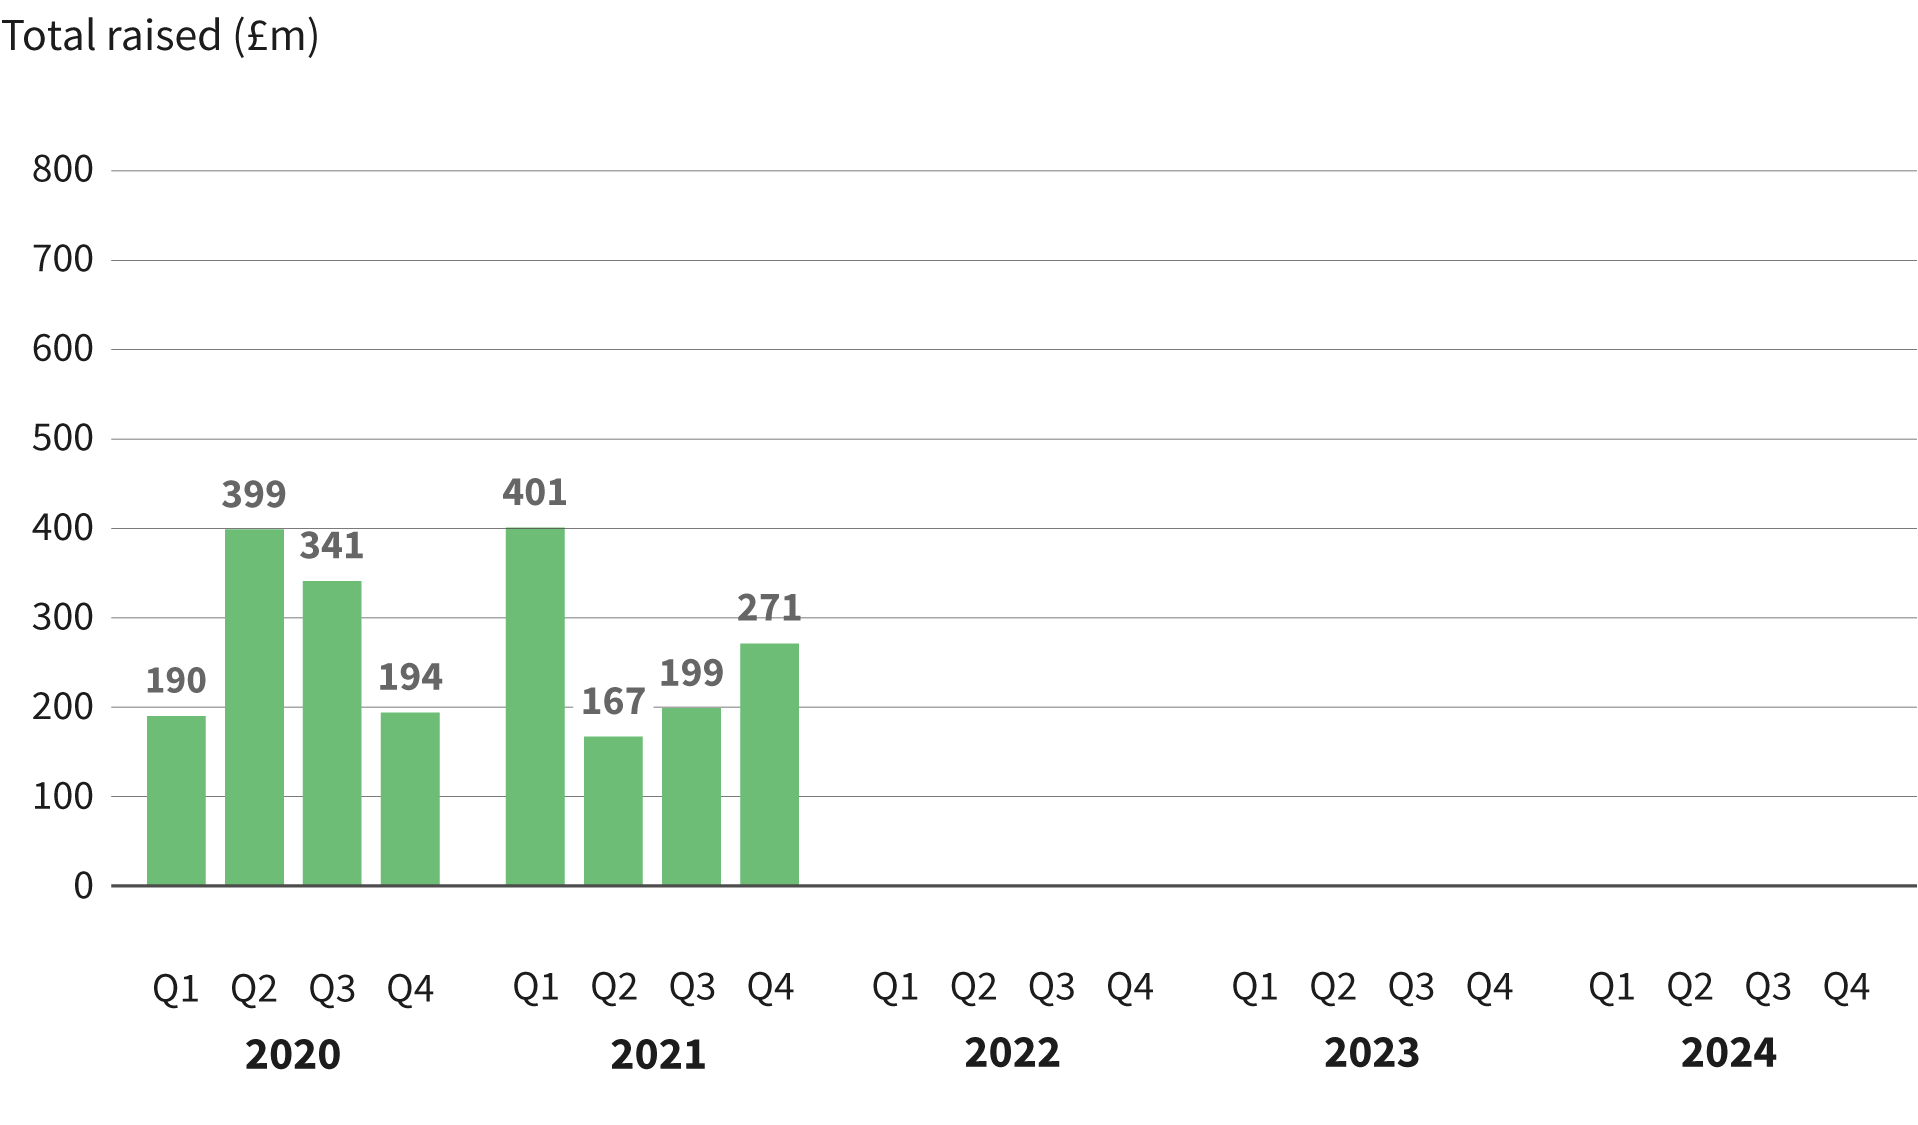
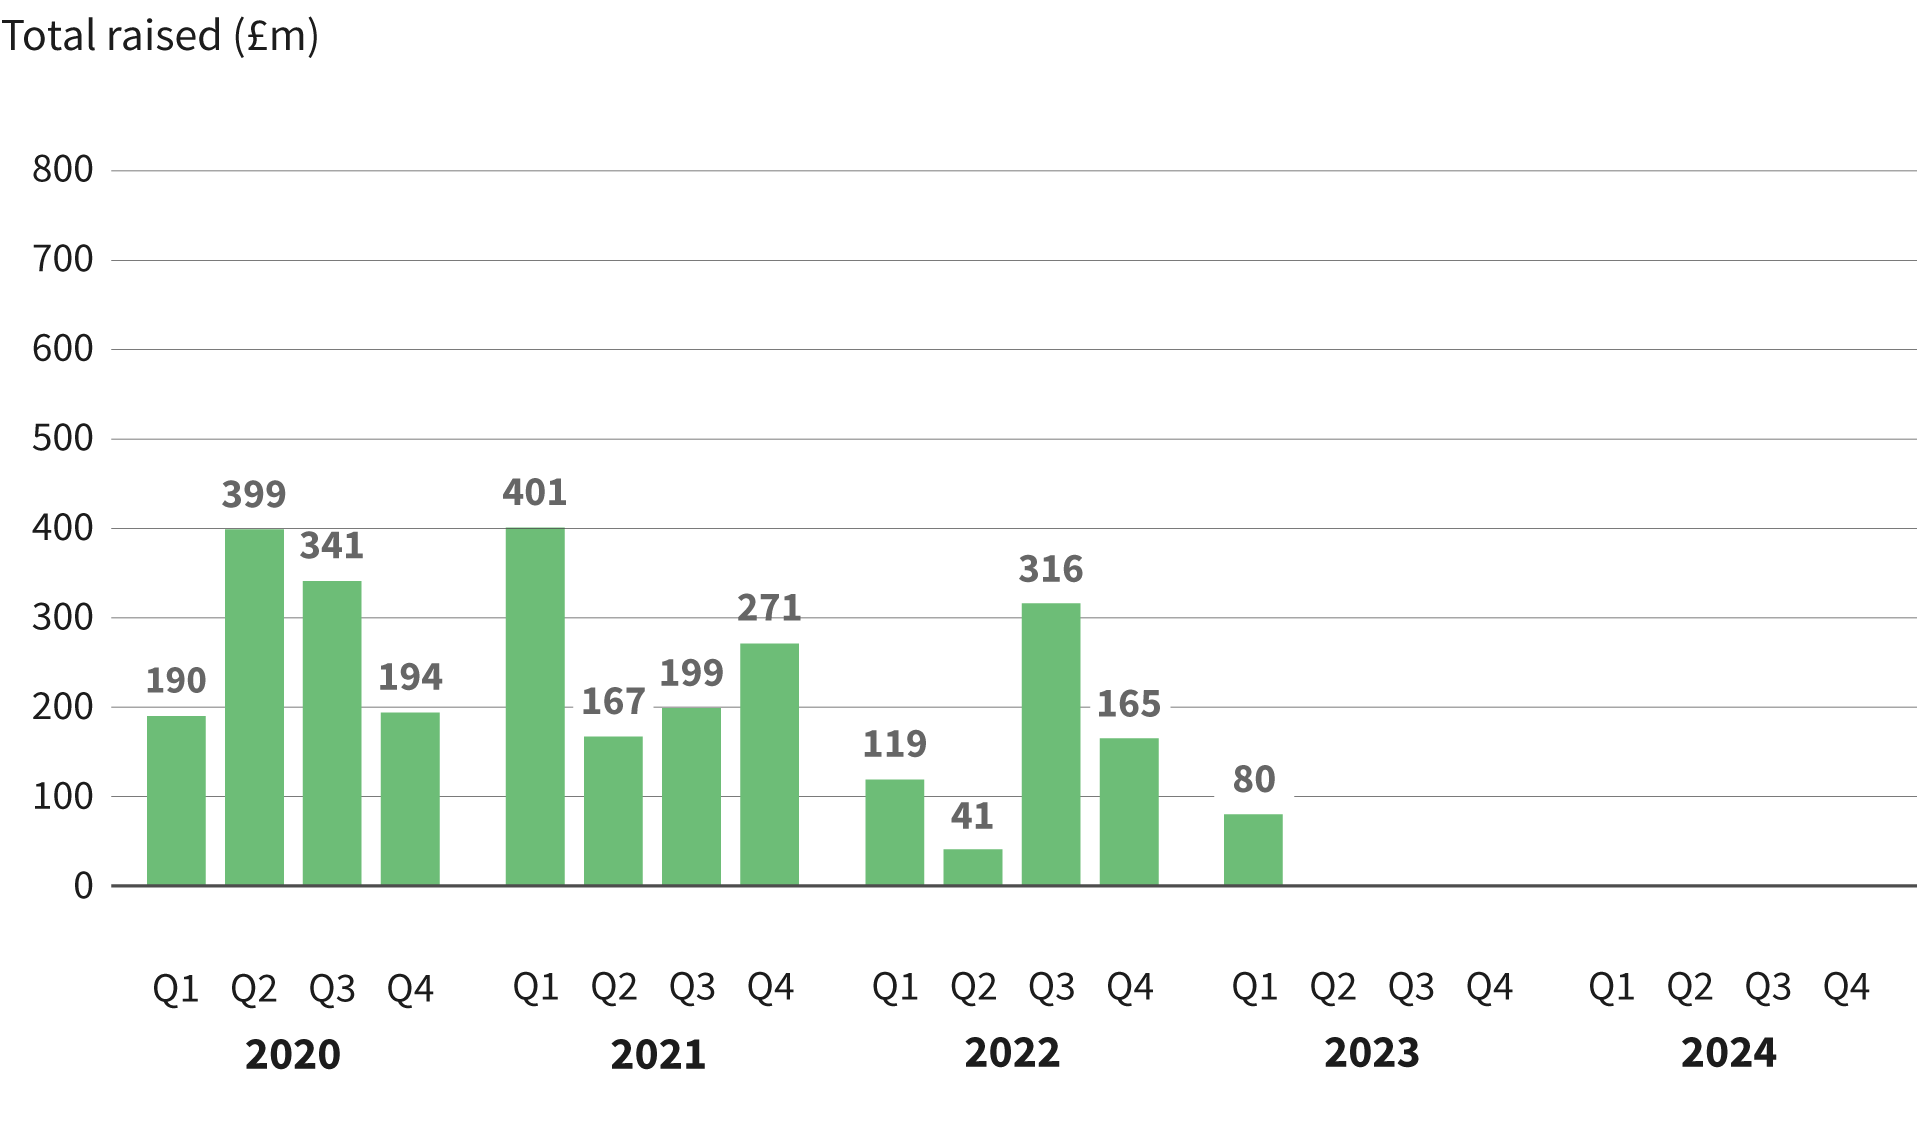
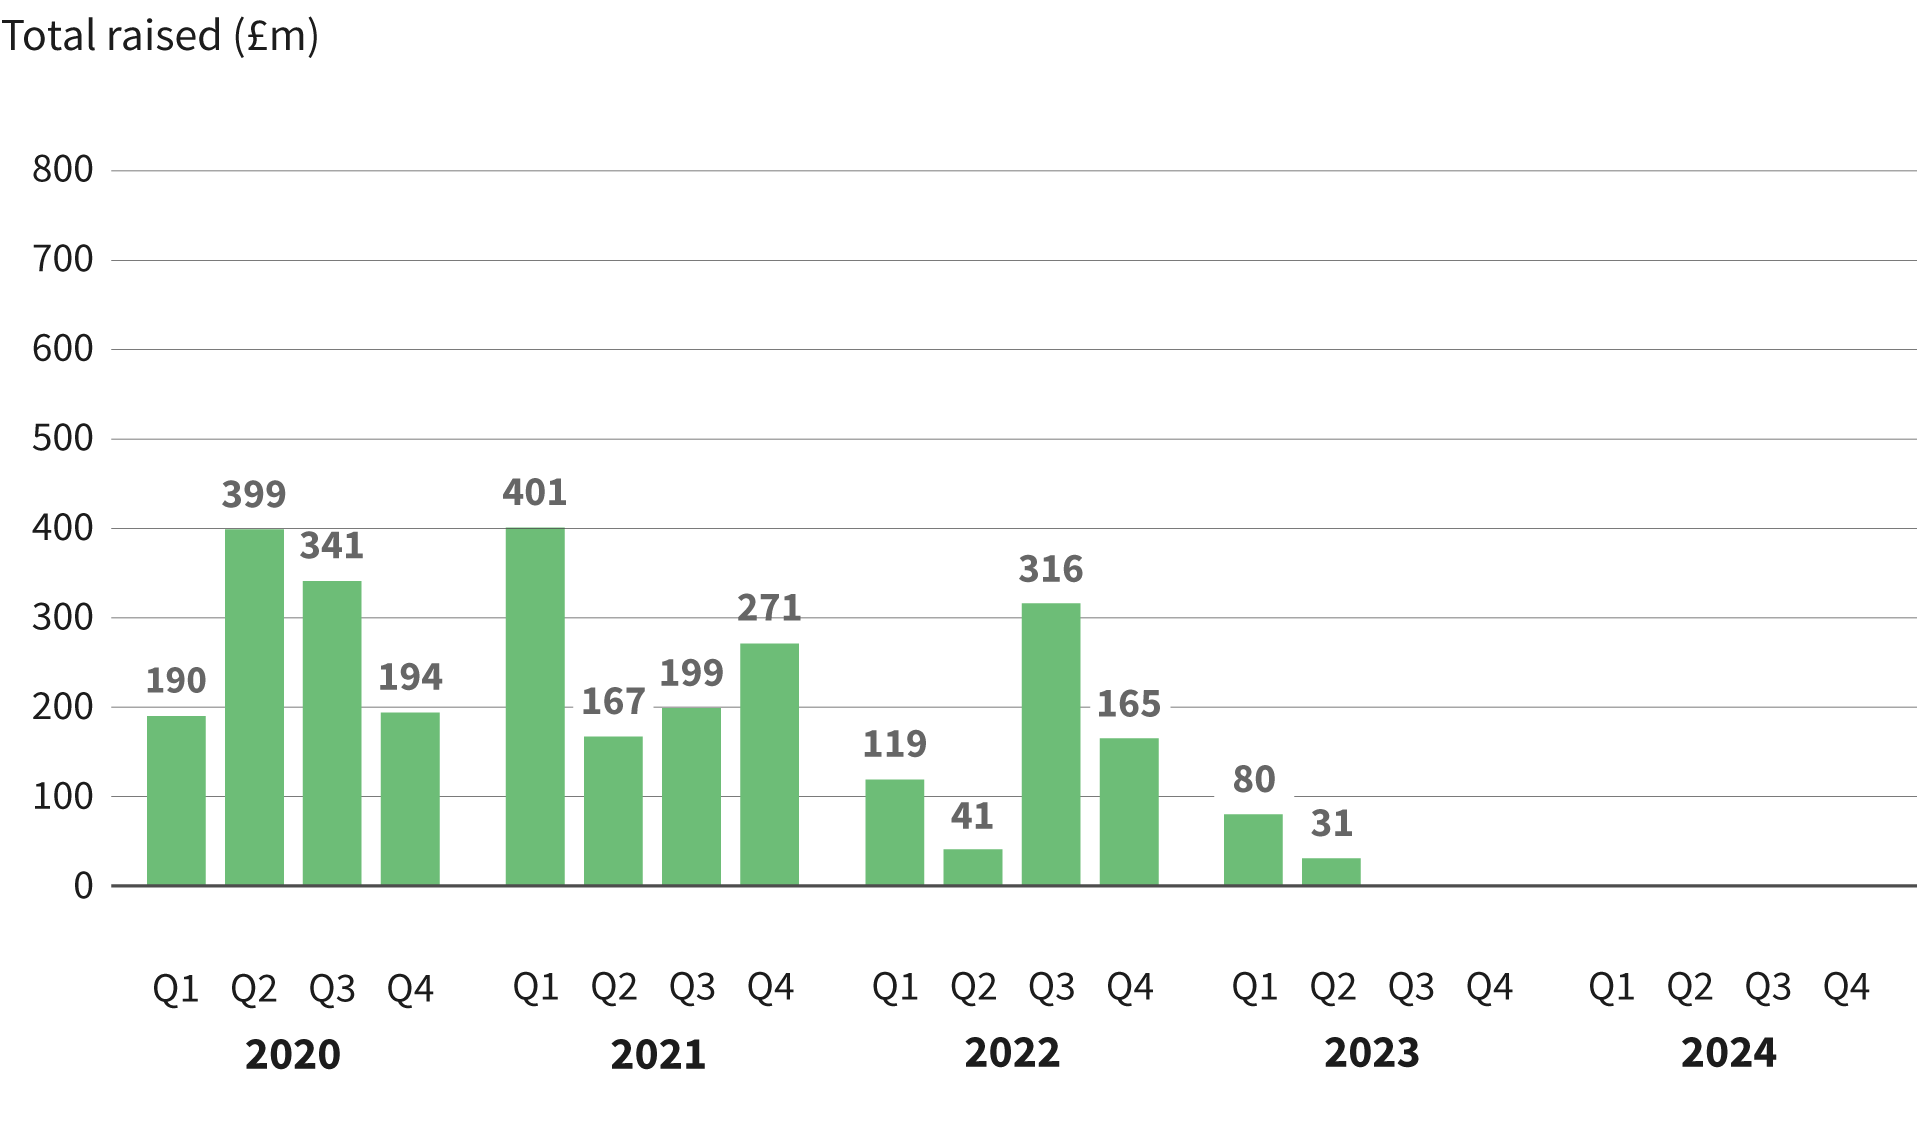
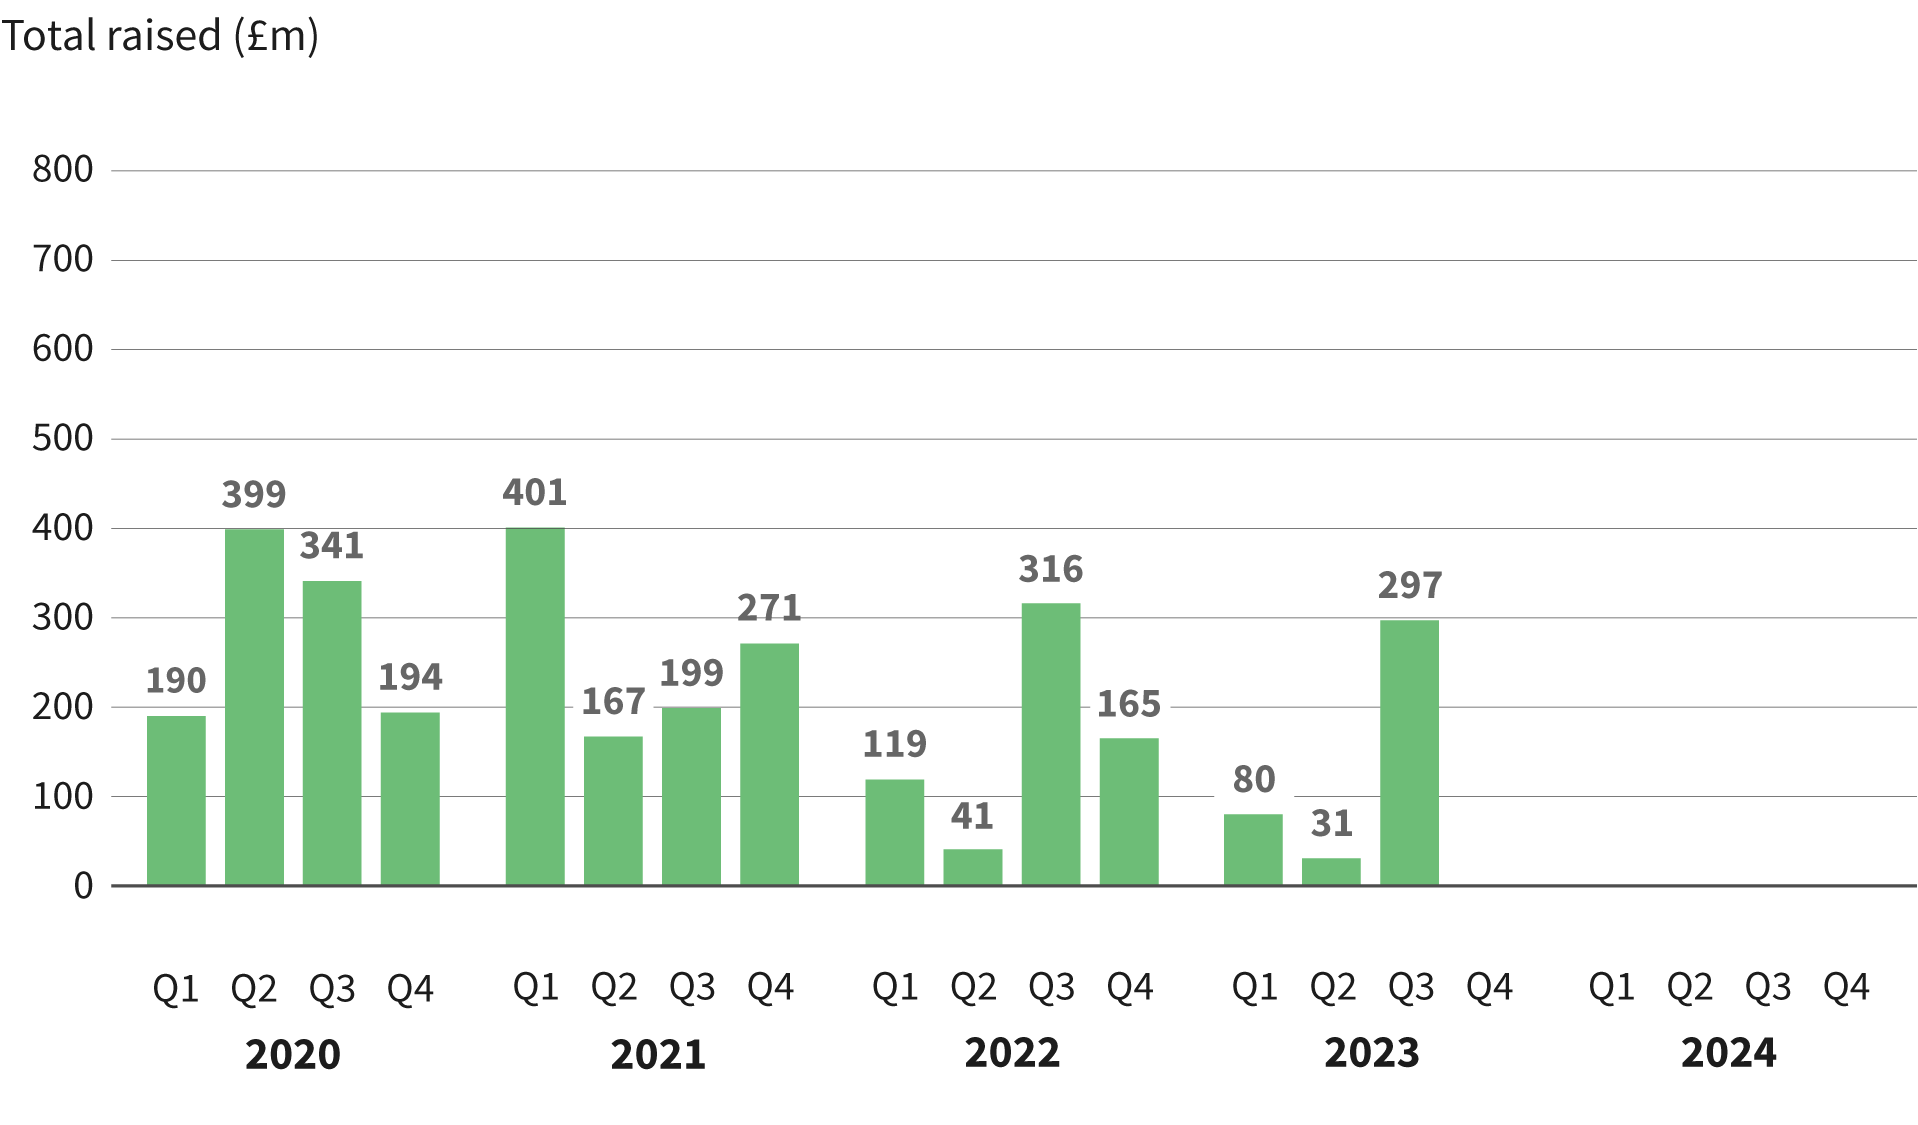
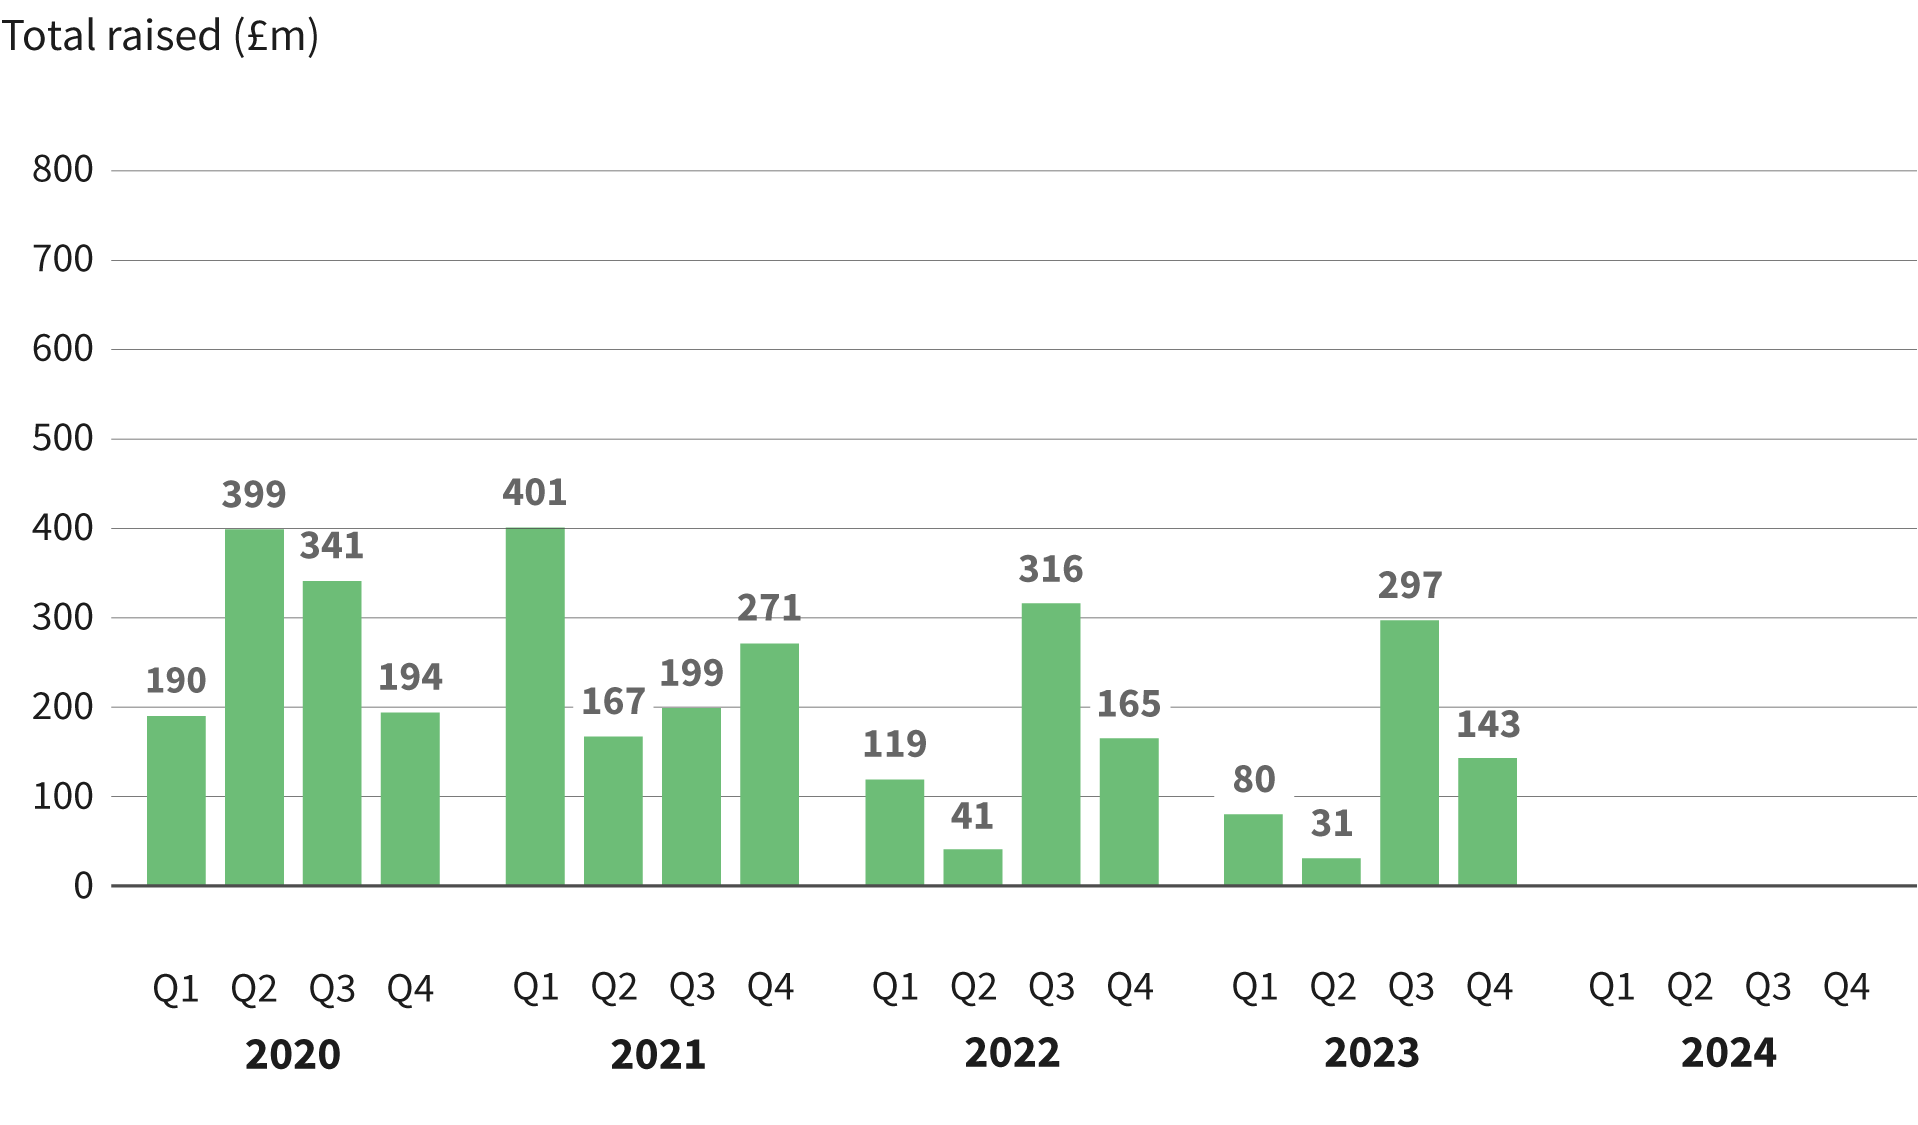
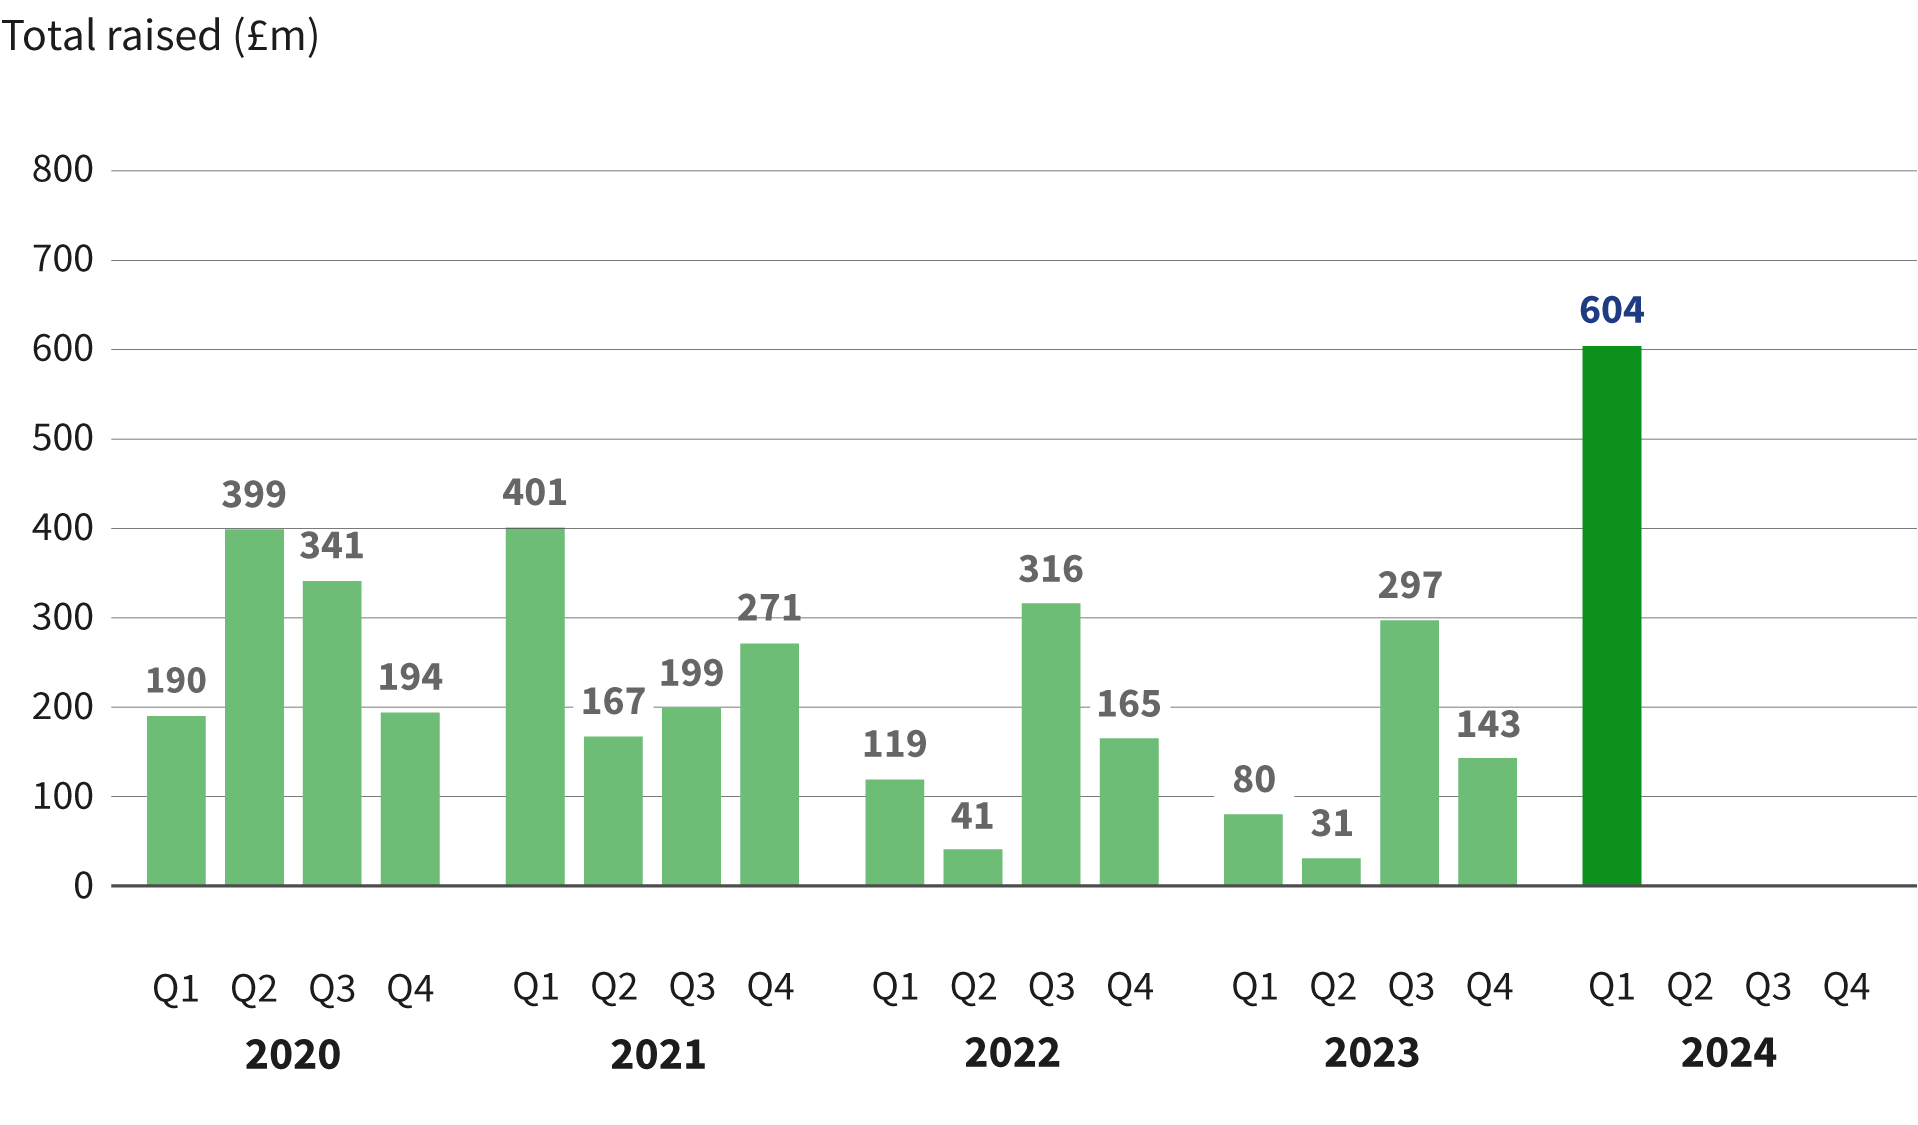
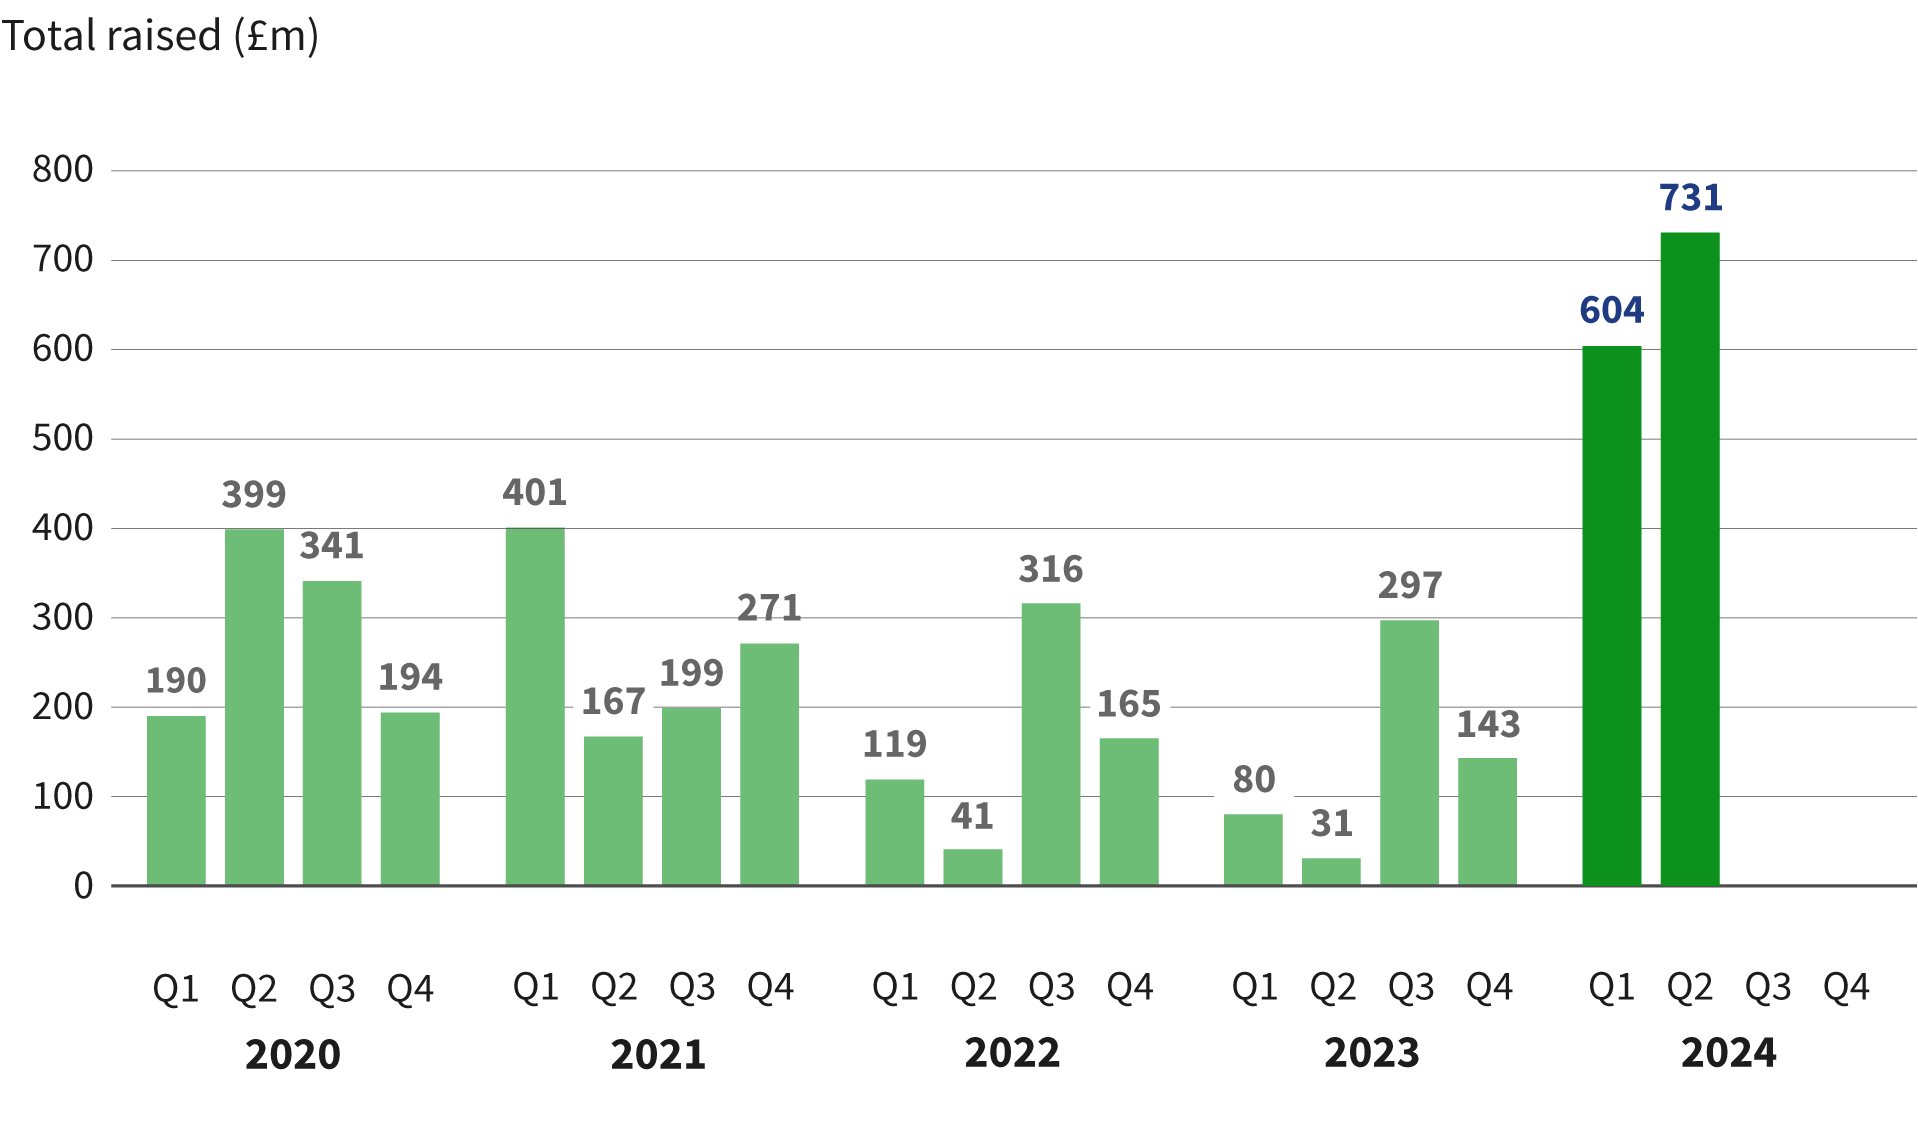
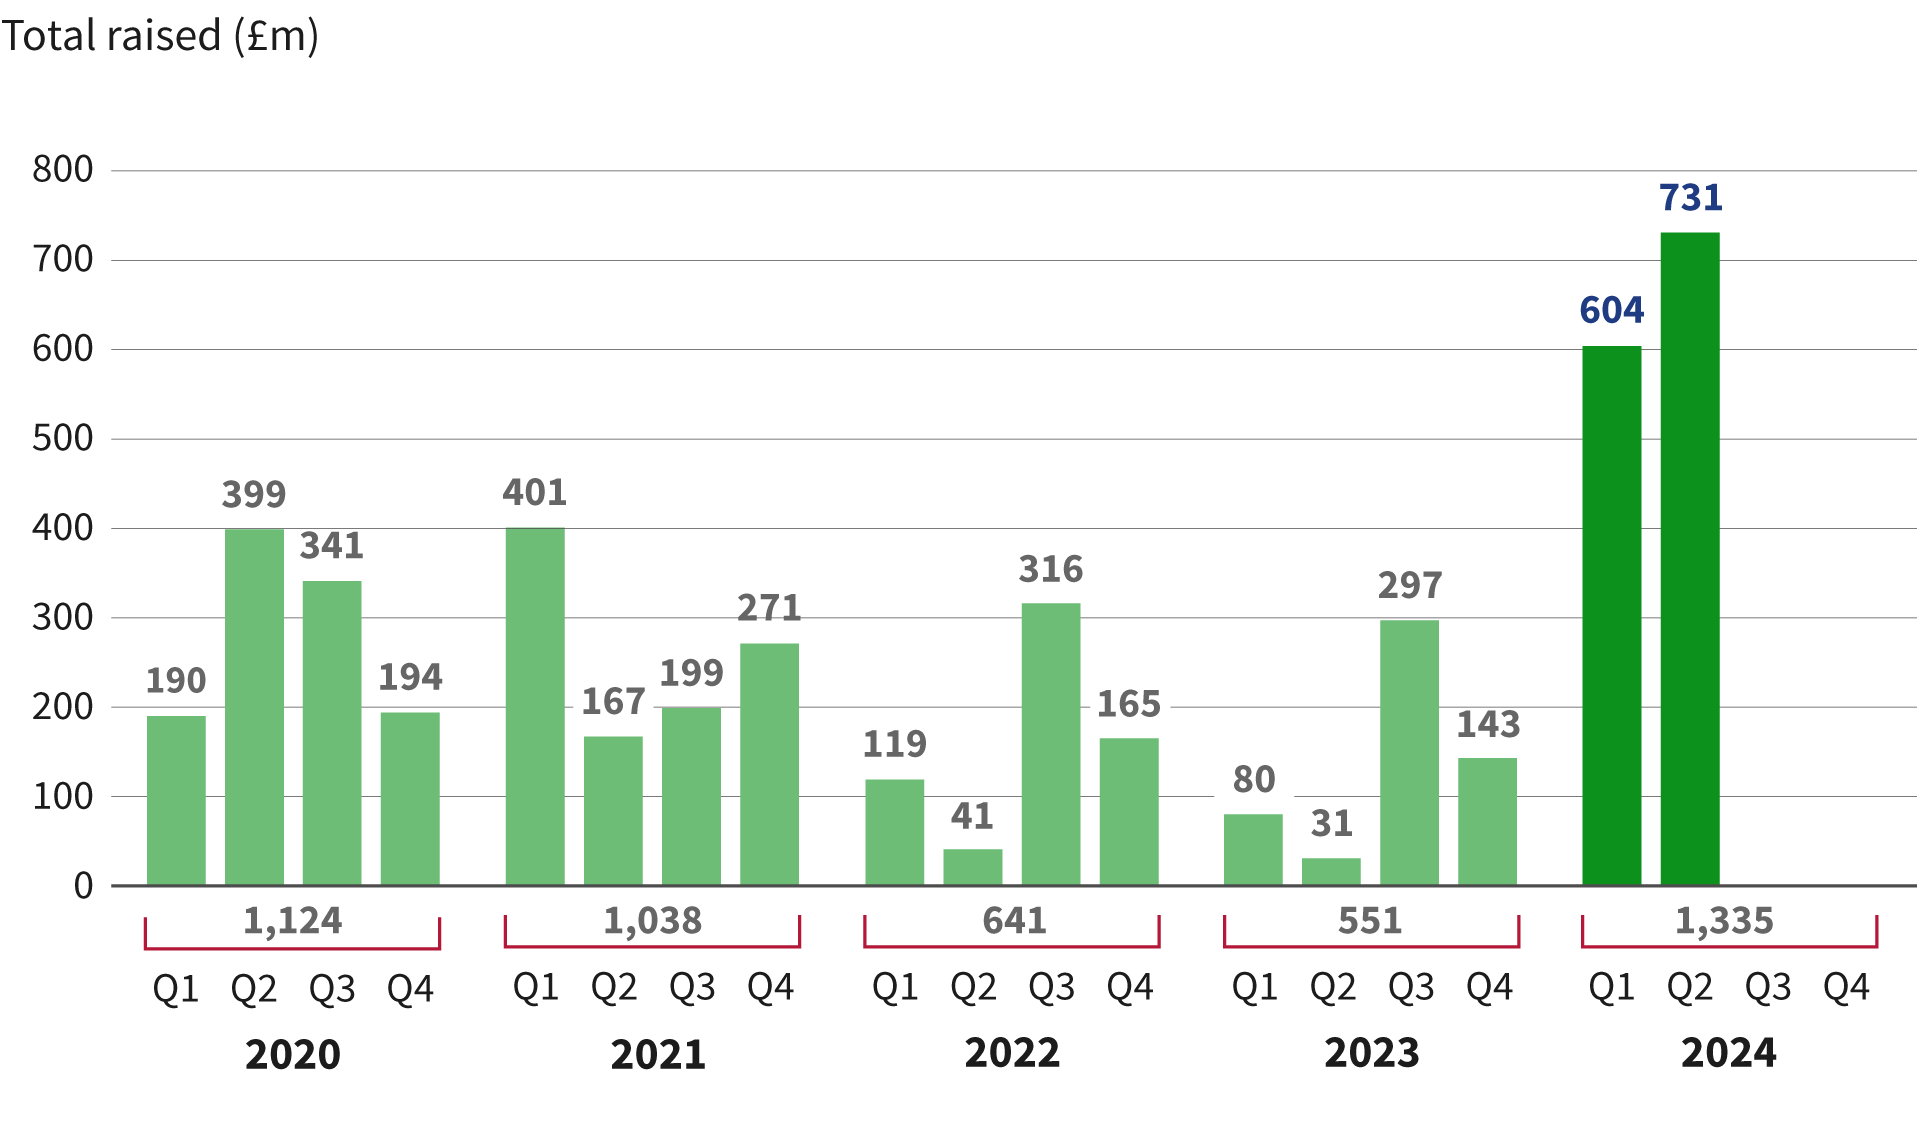
In this quarter, UK biotech companies continued to see a surge in follow-on financing activity, with publicly listed companies raising a total of £731 million, a 63% increase from the previous quarter.
Cambridge-based Bicycle Therapeutics raised a notable £442 million on NASDAQ, contributing significantly to this total. This private placement featured participation from both new and existing investors, supporting various high-value programs and an early discovery pipeline.
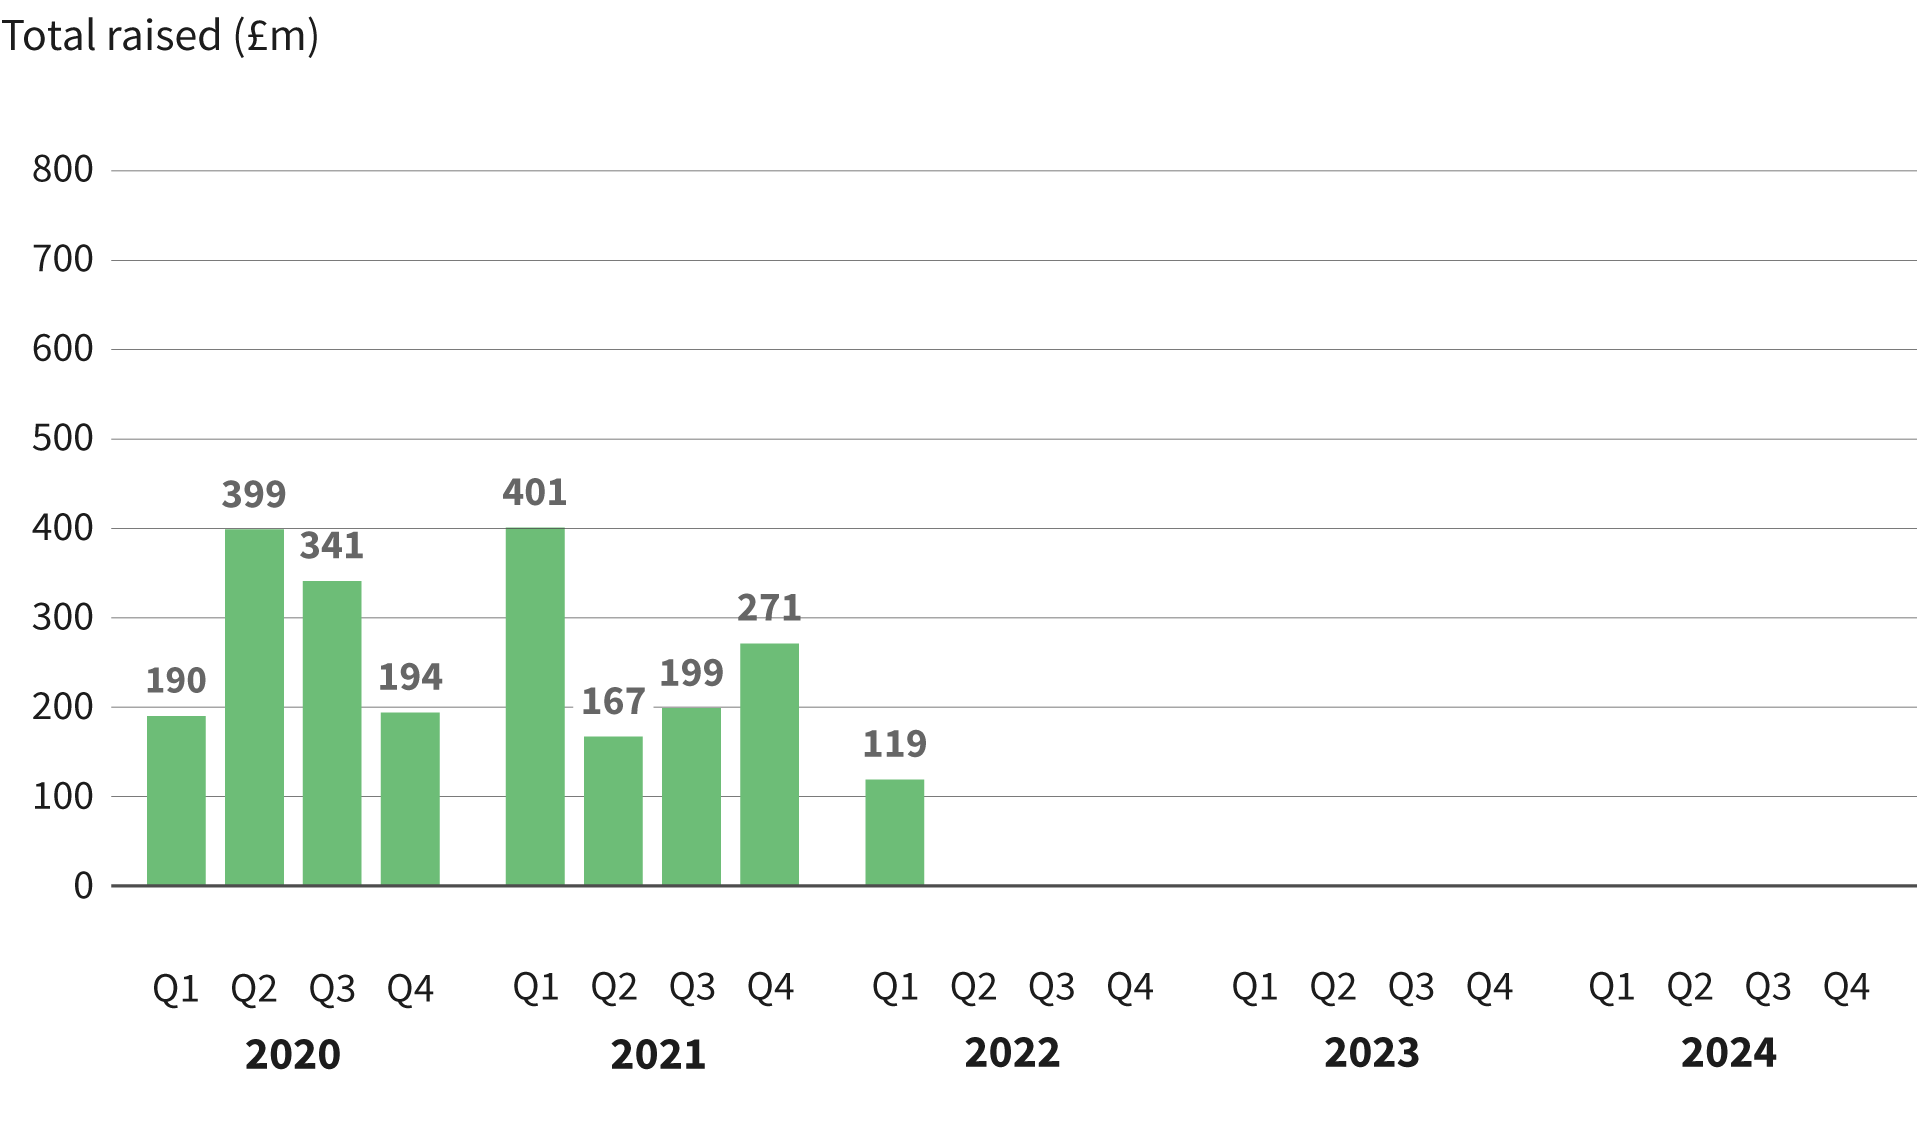
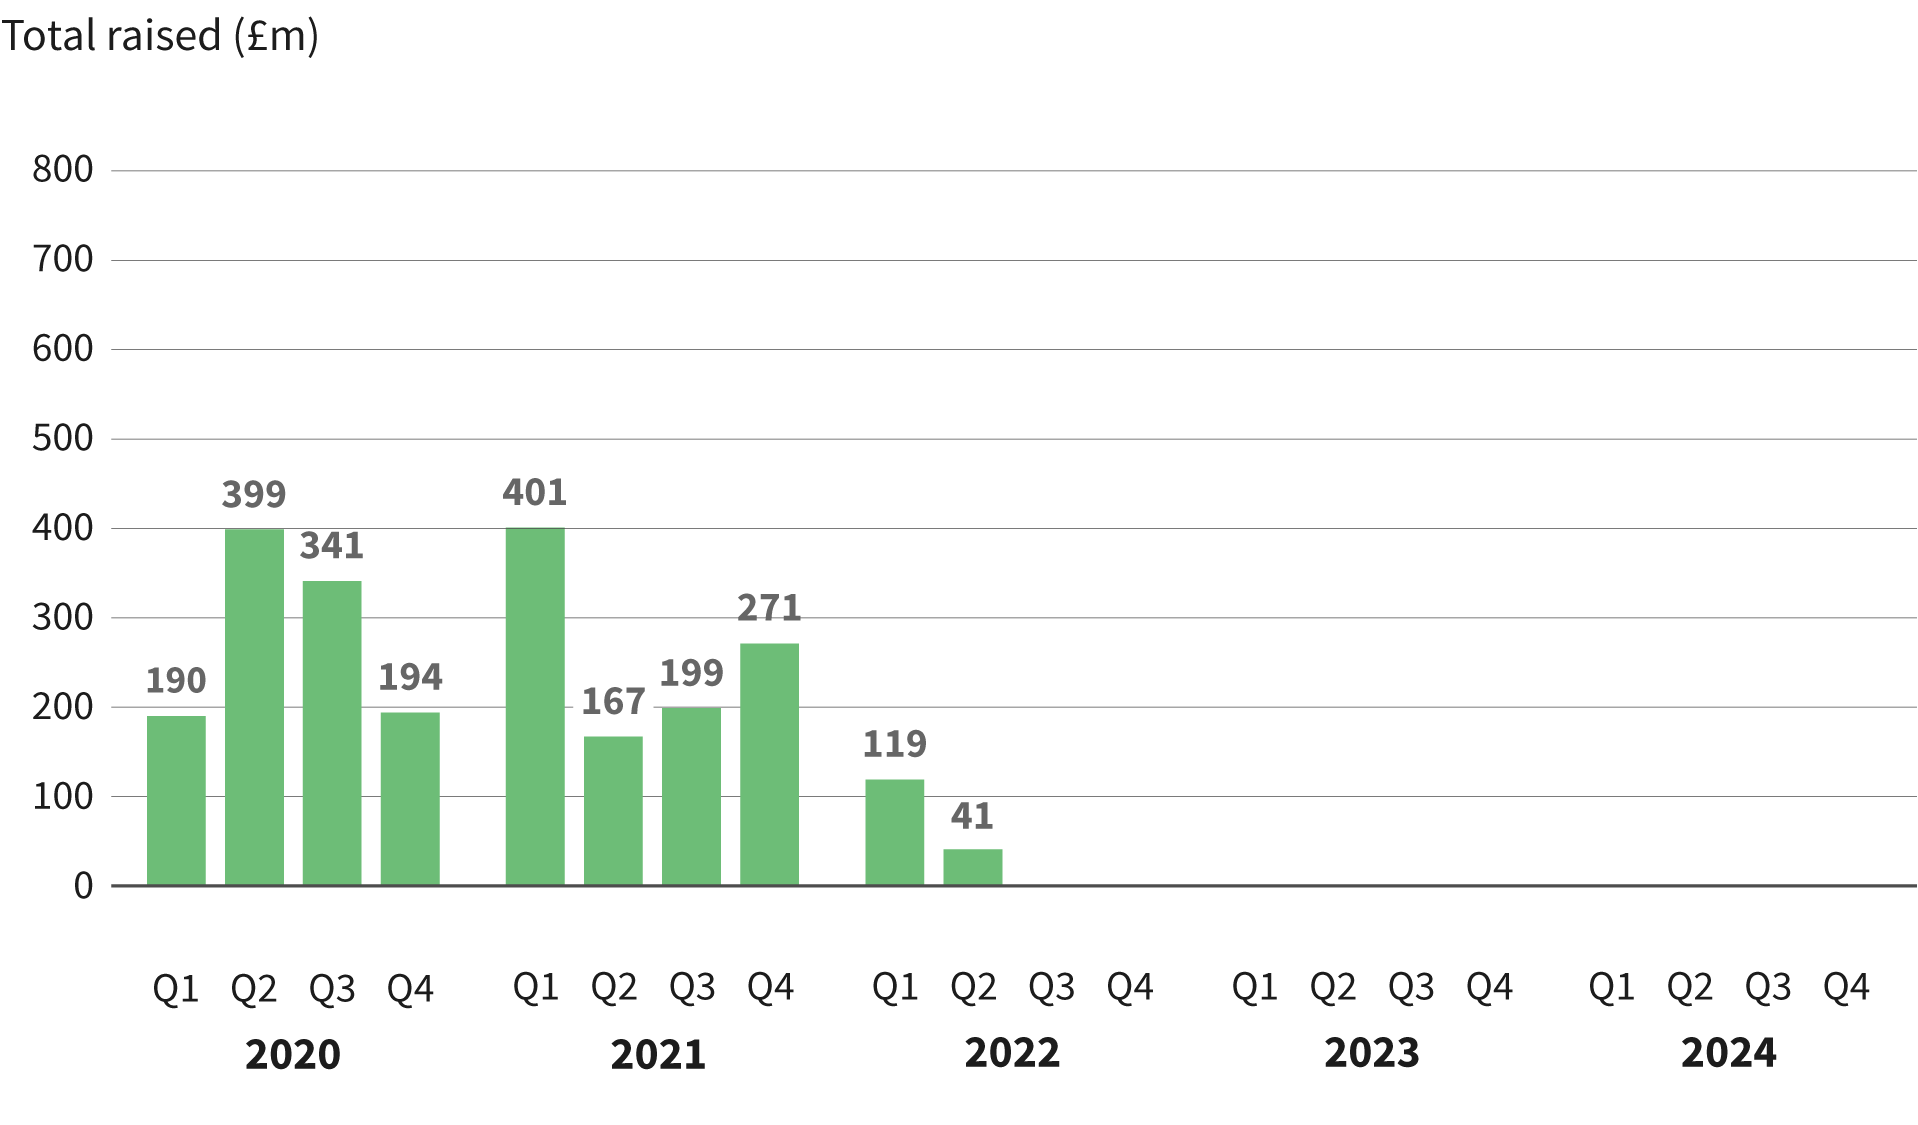
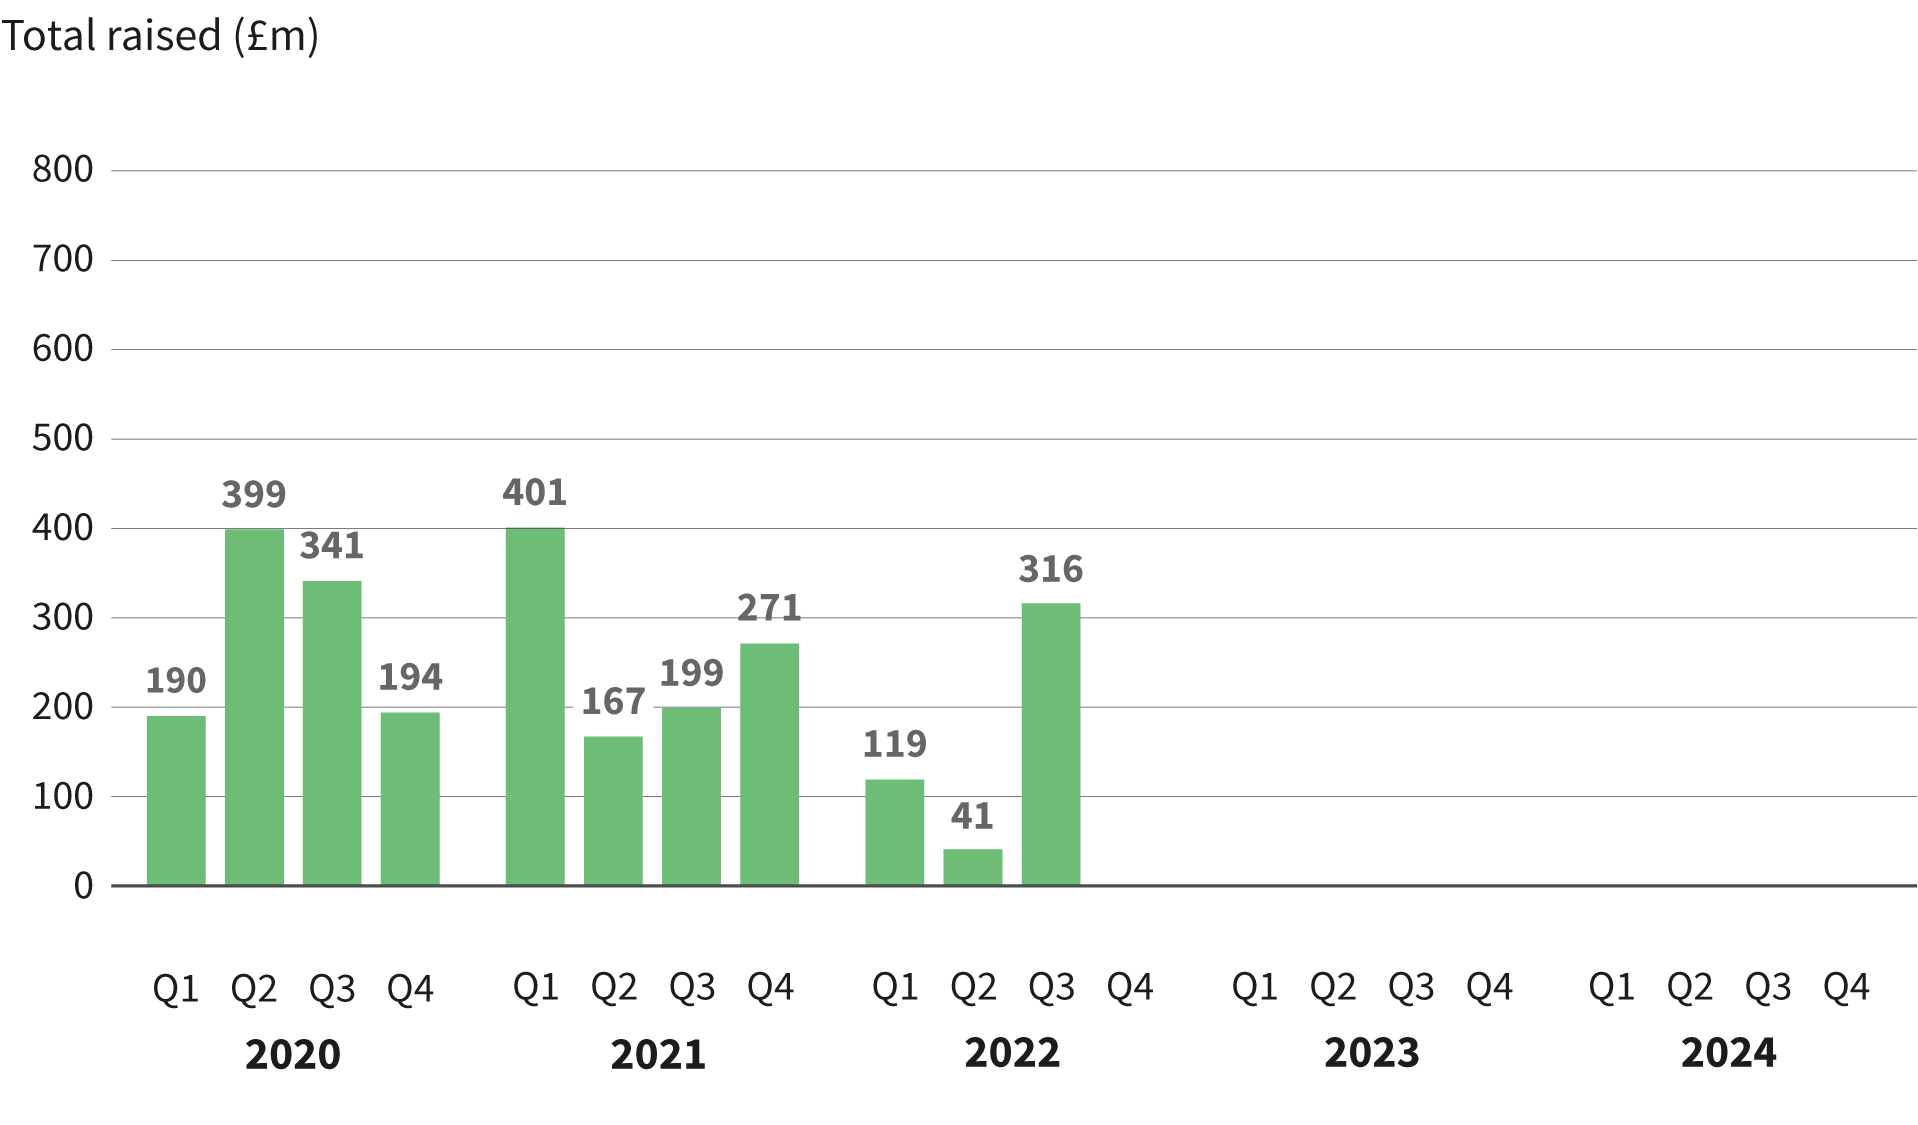
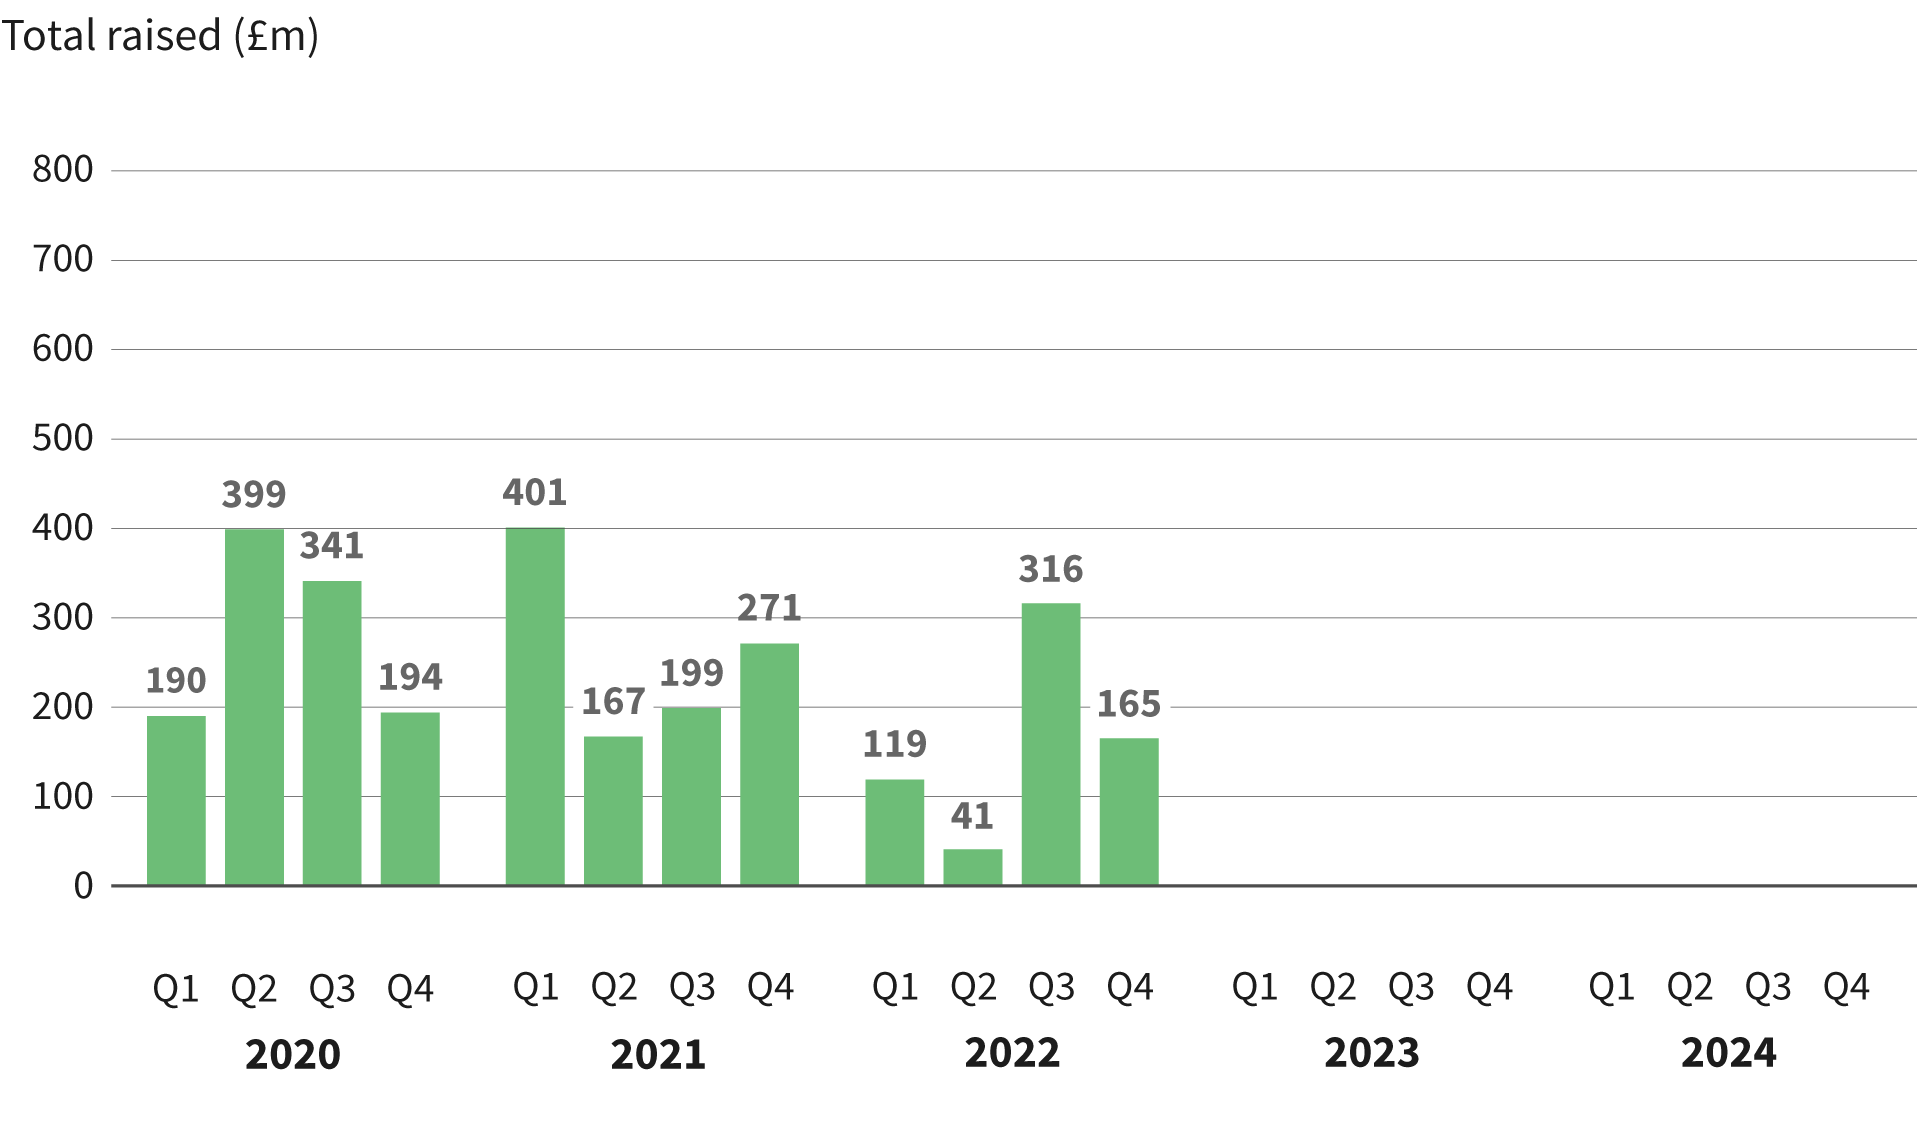
Total raised in follow-ons, shown by quarter in past five years
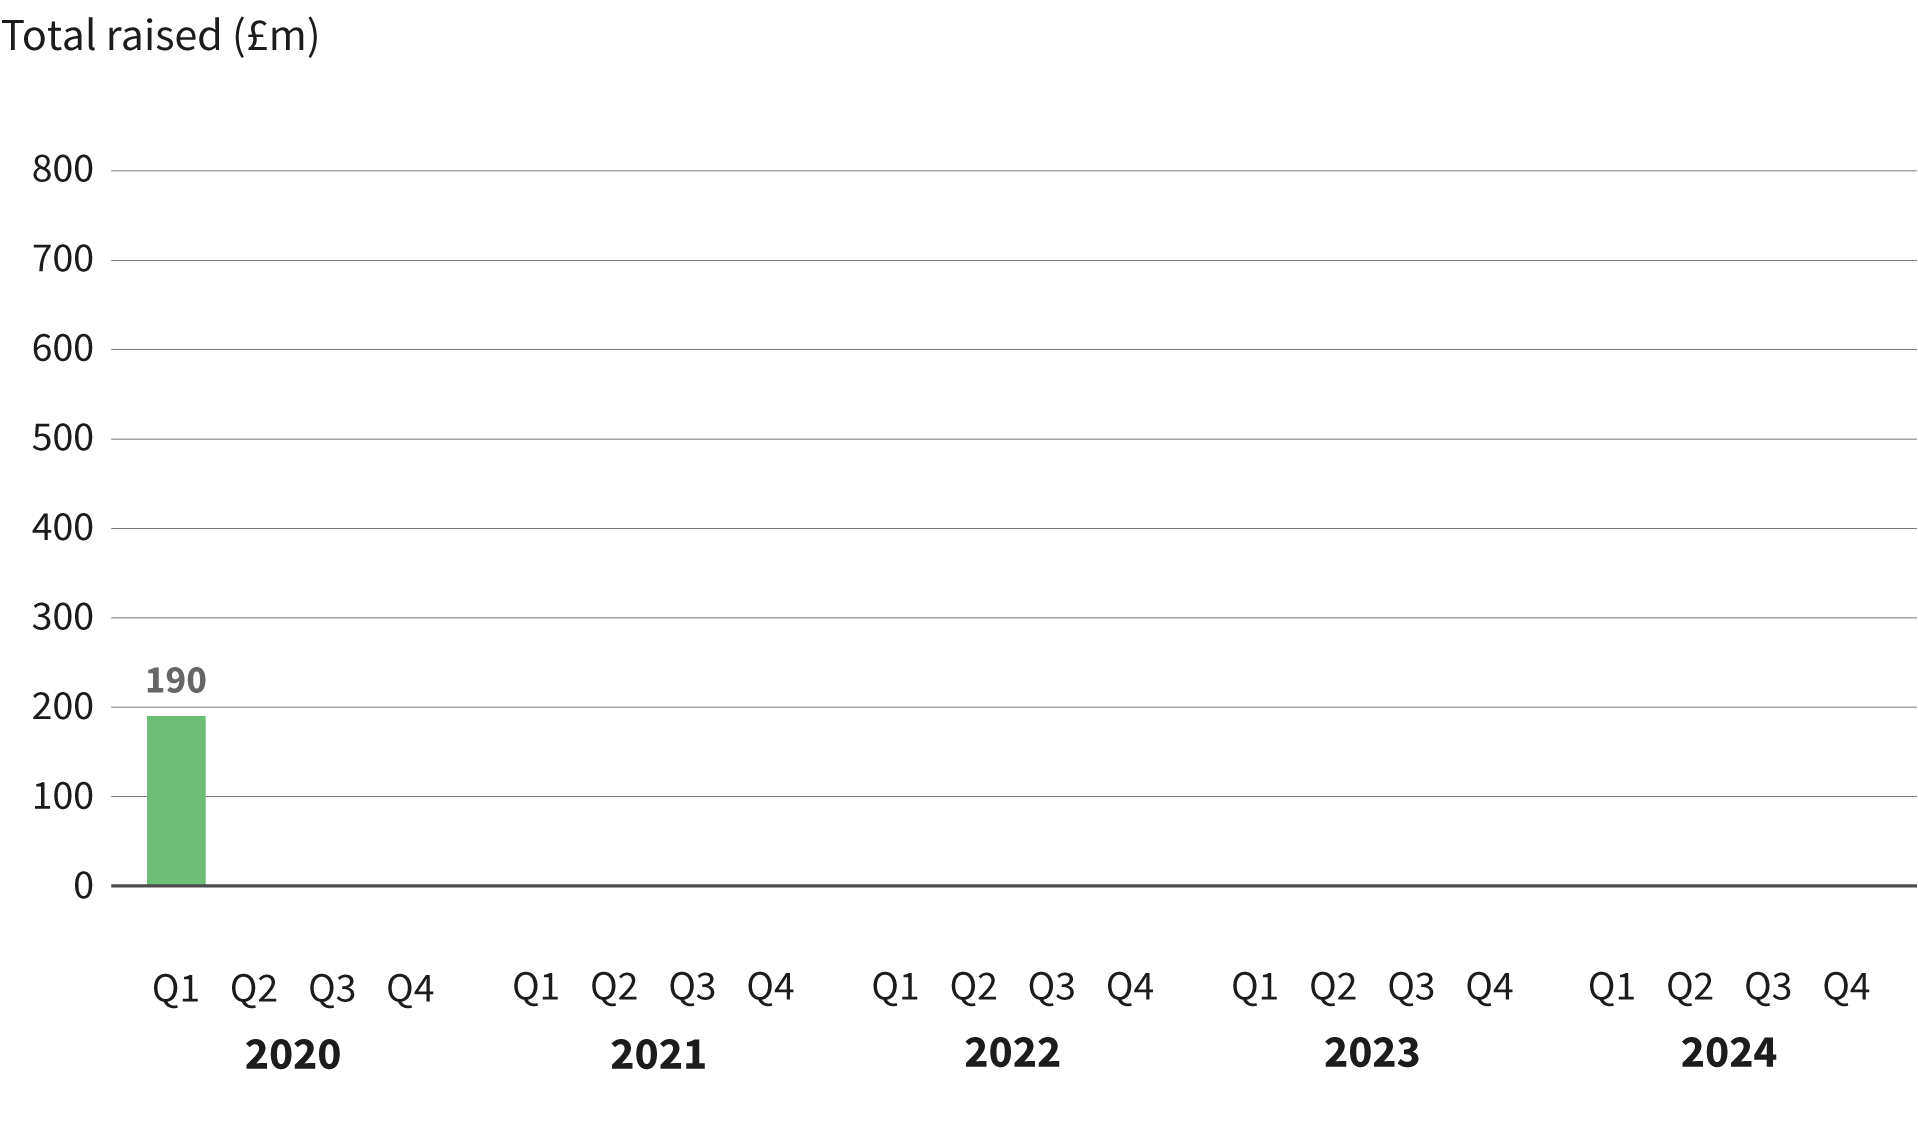
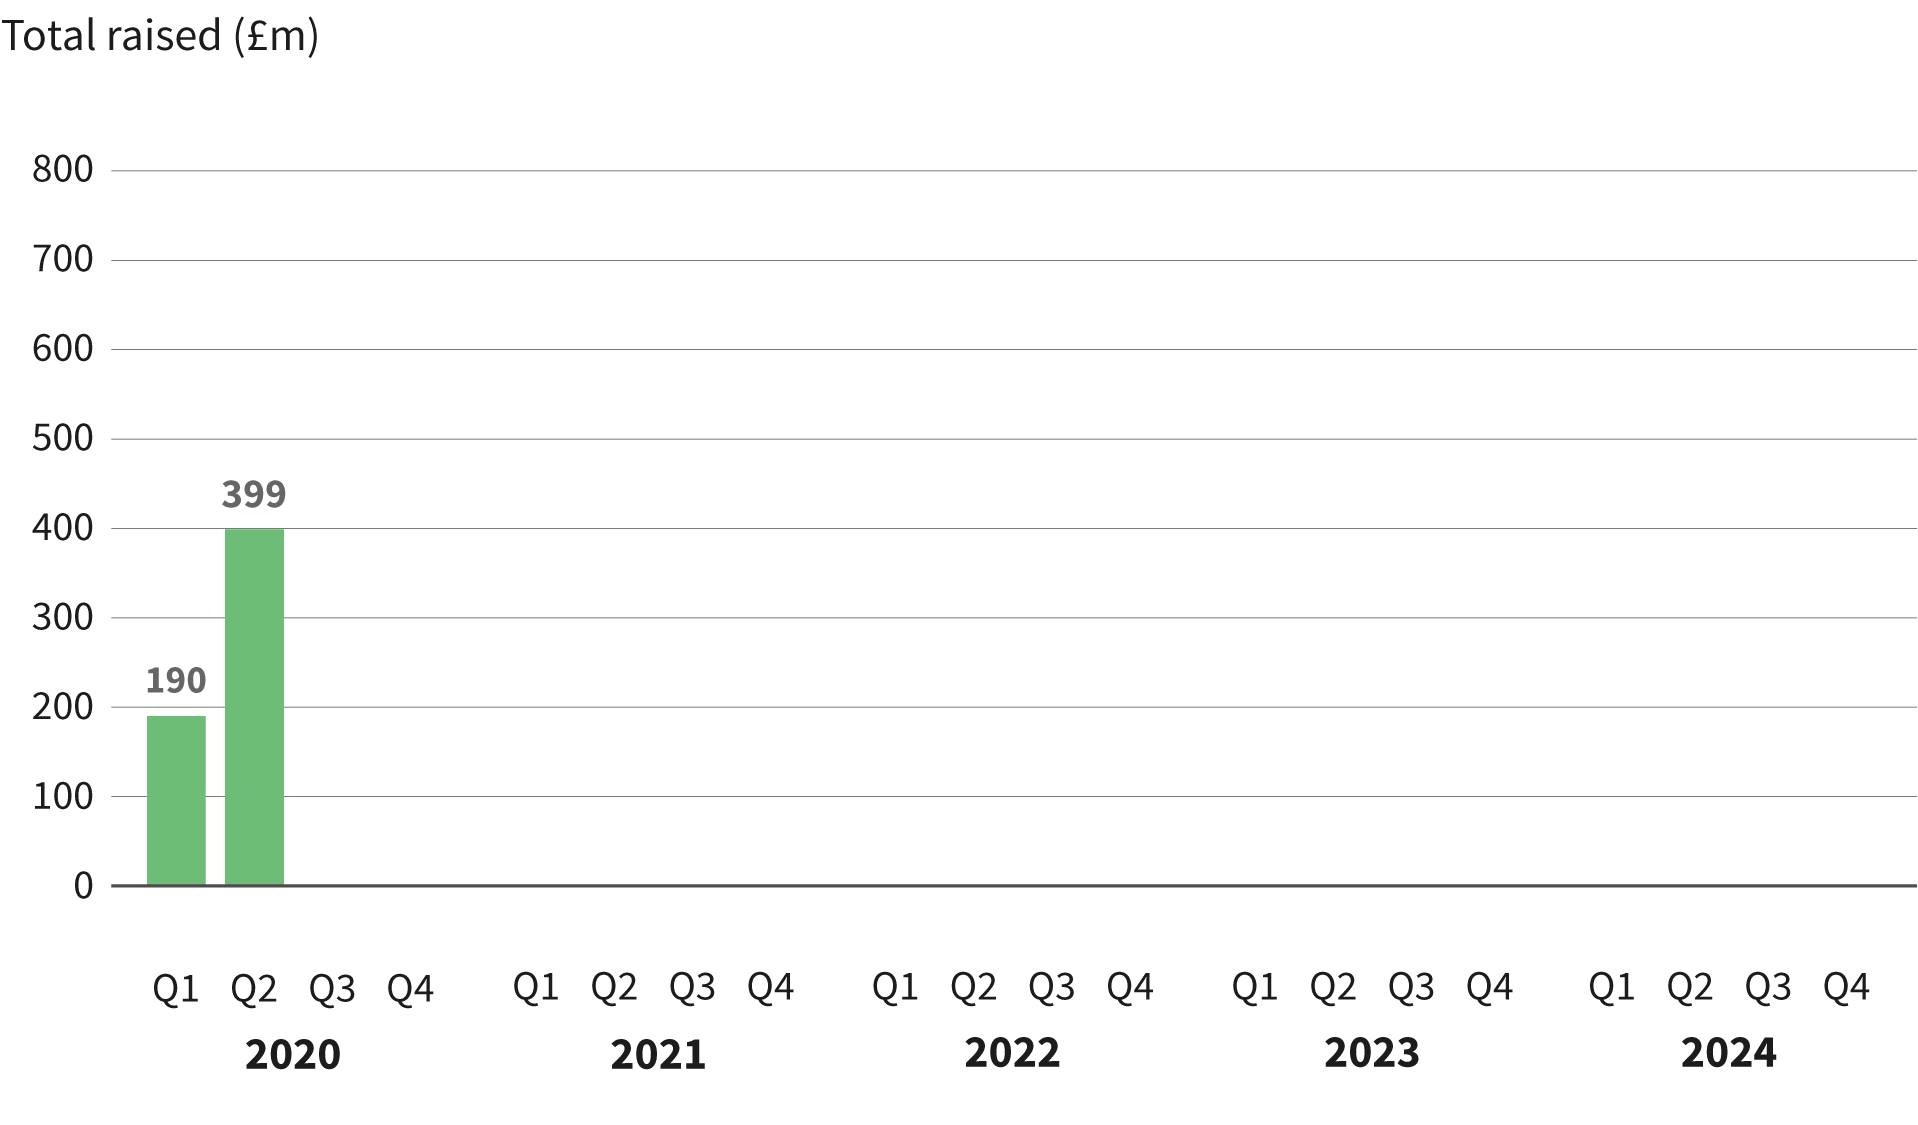
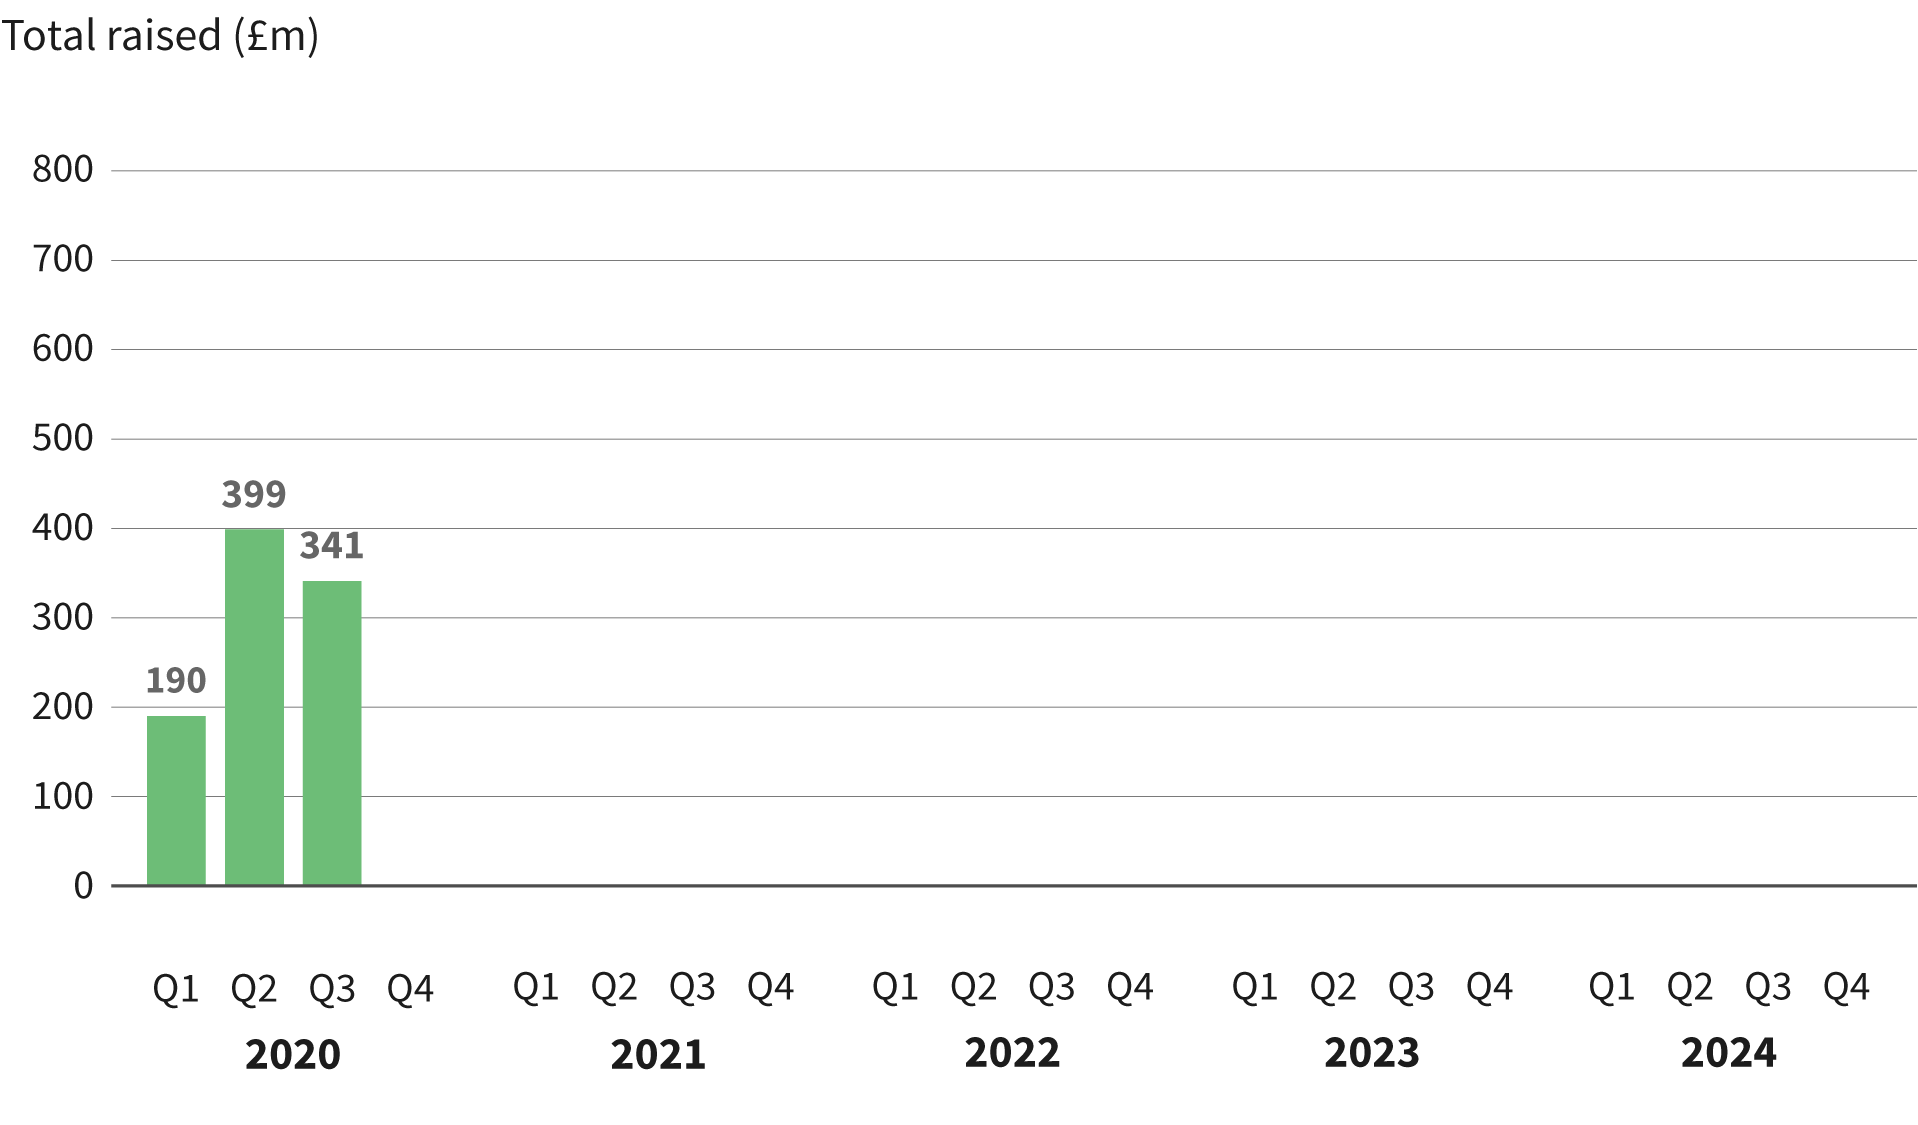
Top five UK biotech public follow-on deals
| Company | Date | Market | Amount (£m) |
|---|---|---|---|
| Bicycle Therapeutics | 23/05/2024 | NASDAQ | 442 |
| Summit Therapeutics | 03/06/2024 | NASDAQ | 154 |
| Centessa Pharmaceuticals | 25/04/2024 | NASDAQ | 80 |
| Mereo Biopharma | 14/06/2024 | NASDAQ | 39 |
| Sareum Holdings | 05/04/2024 | AIM | 2 |
International follow-ons
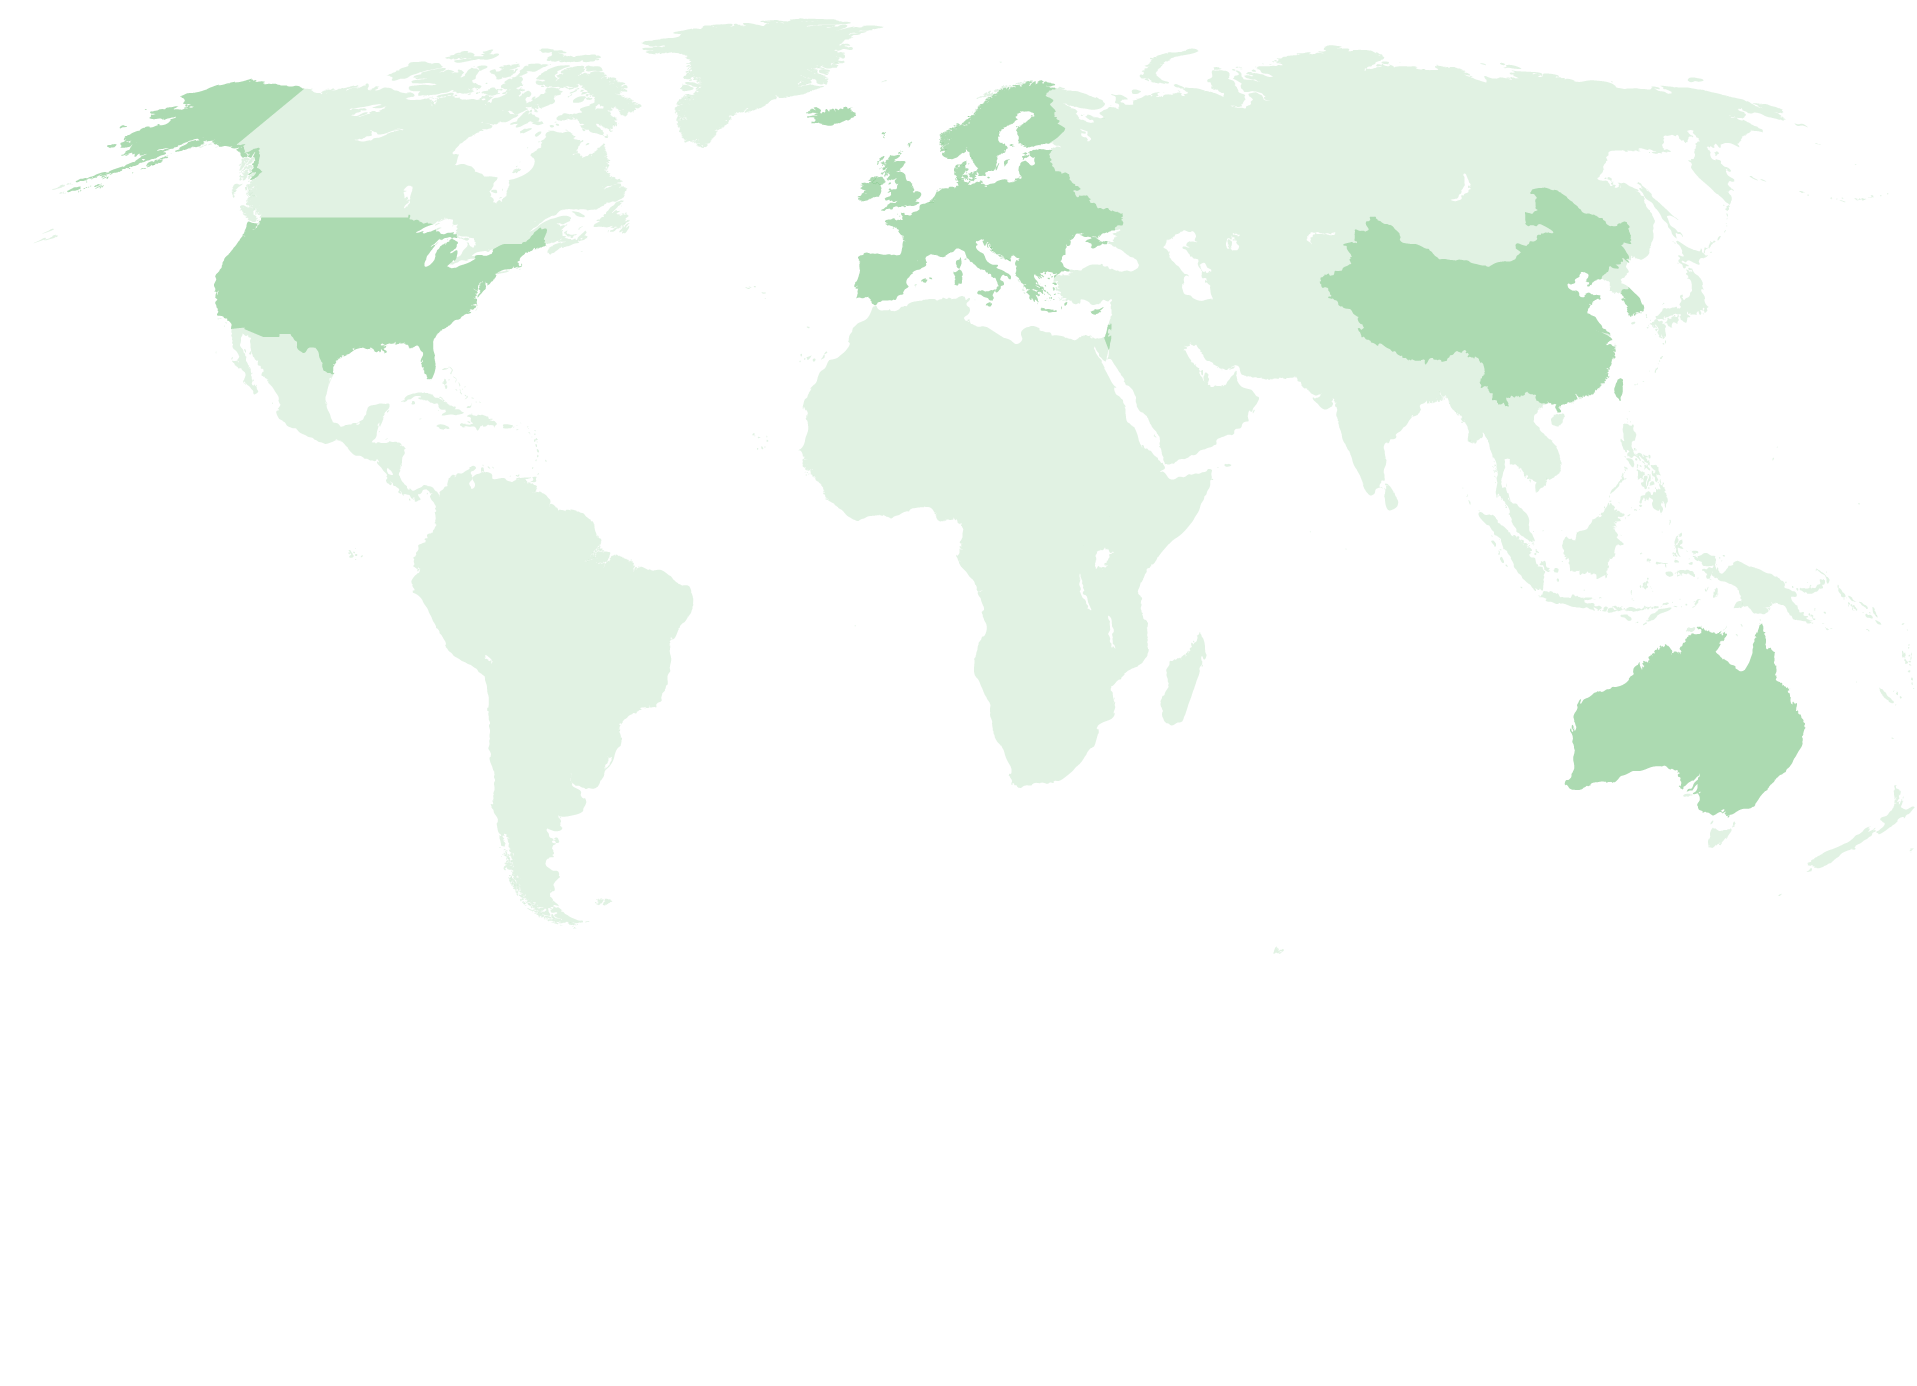
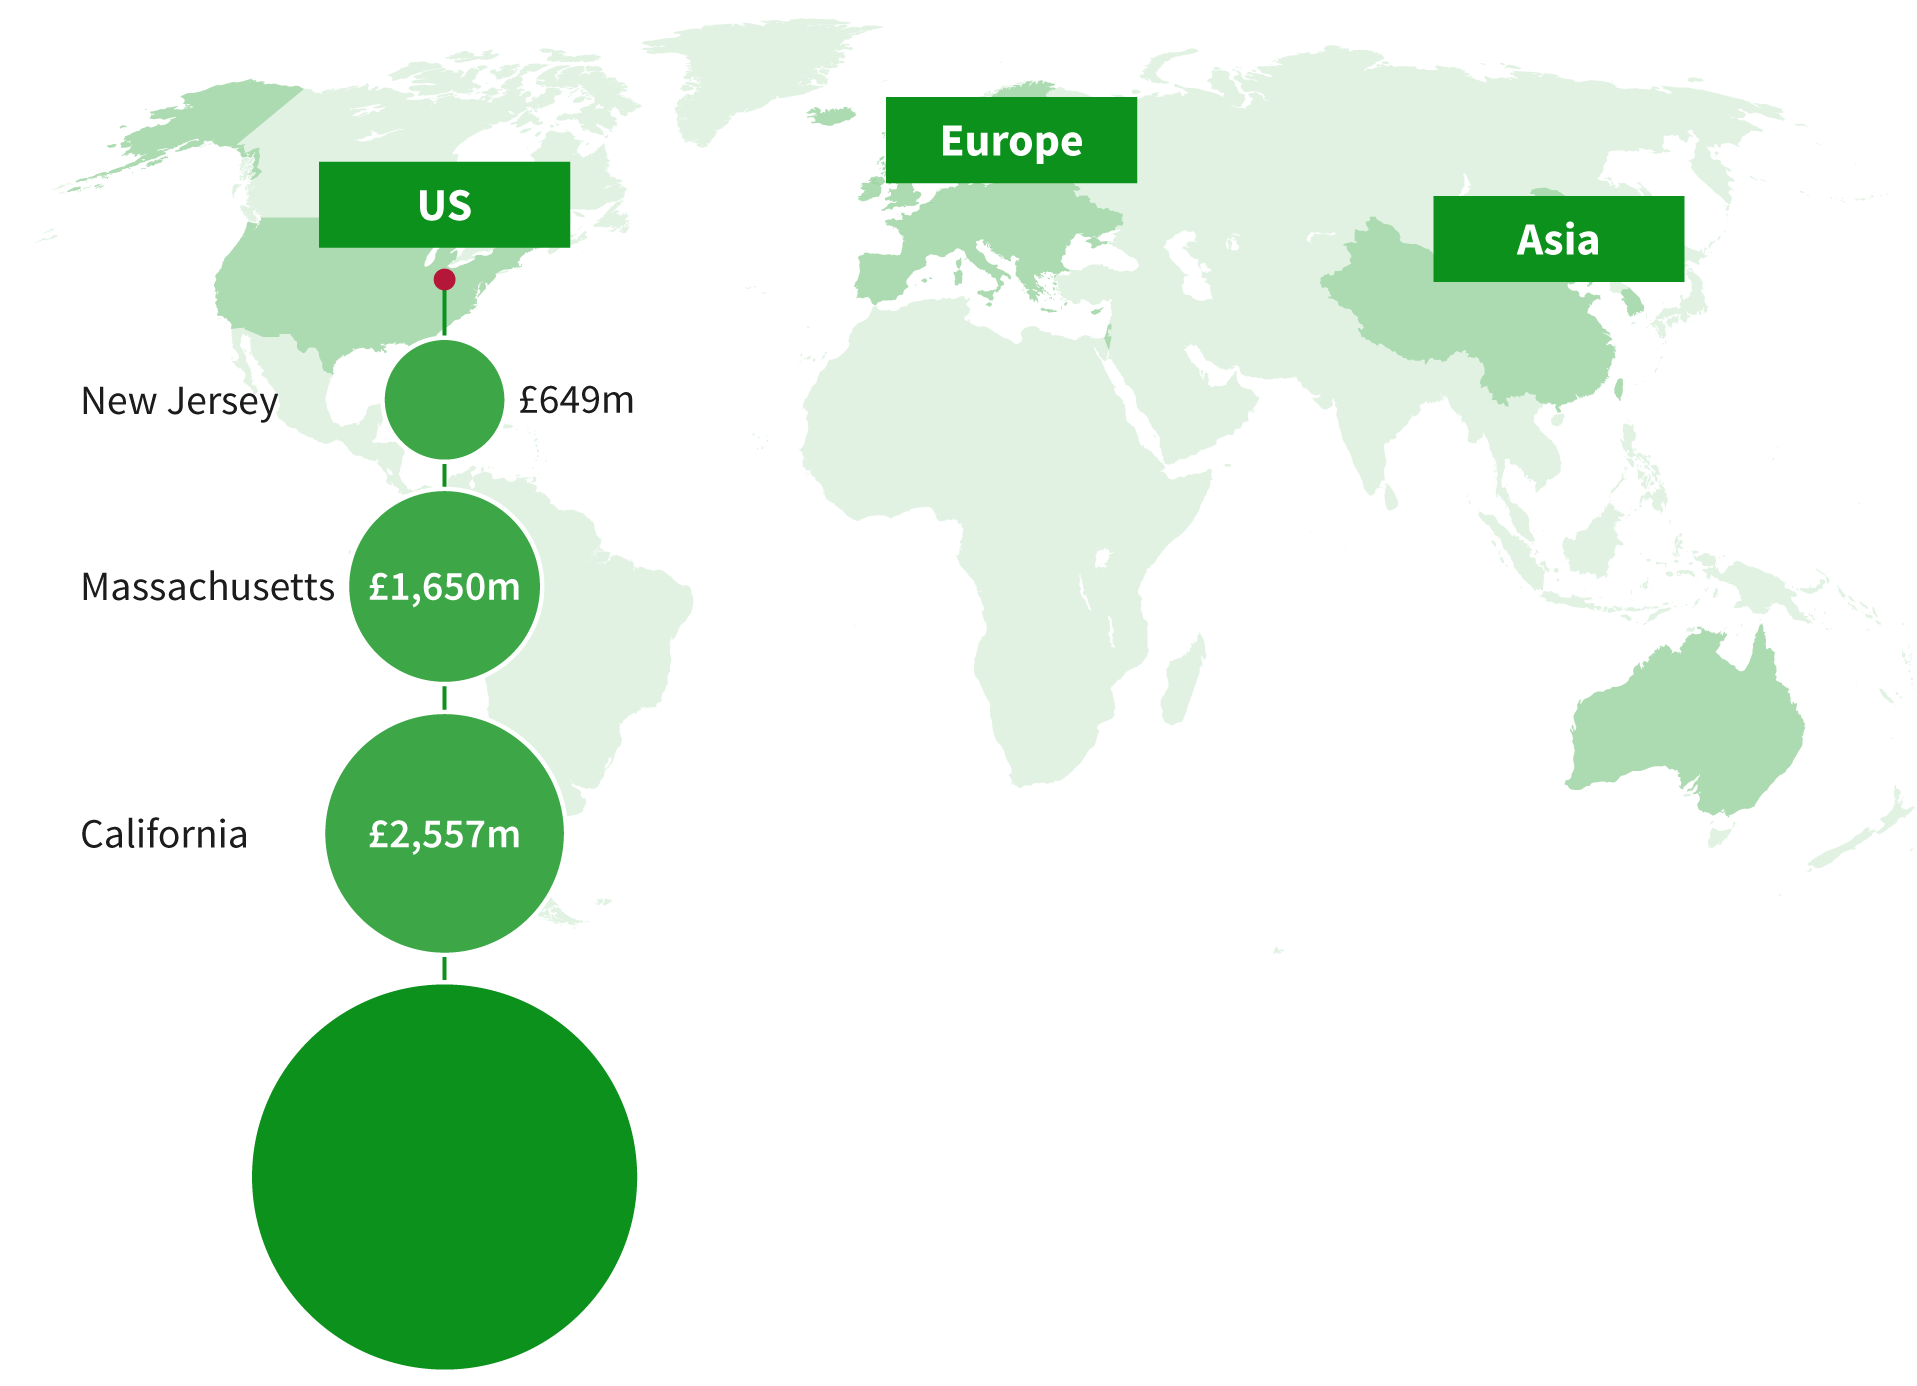
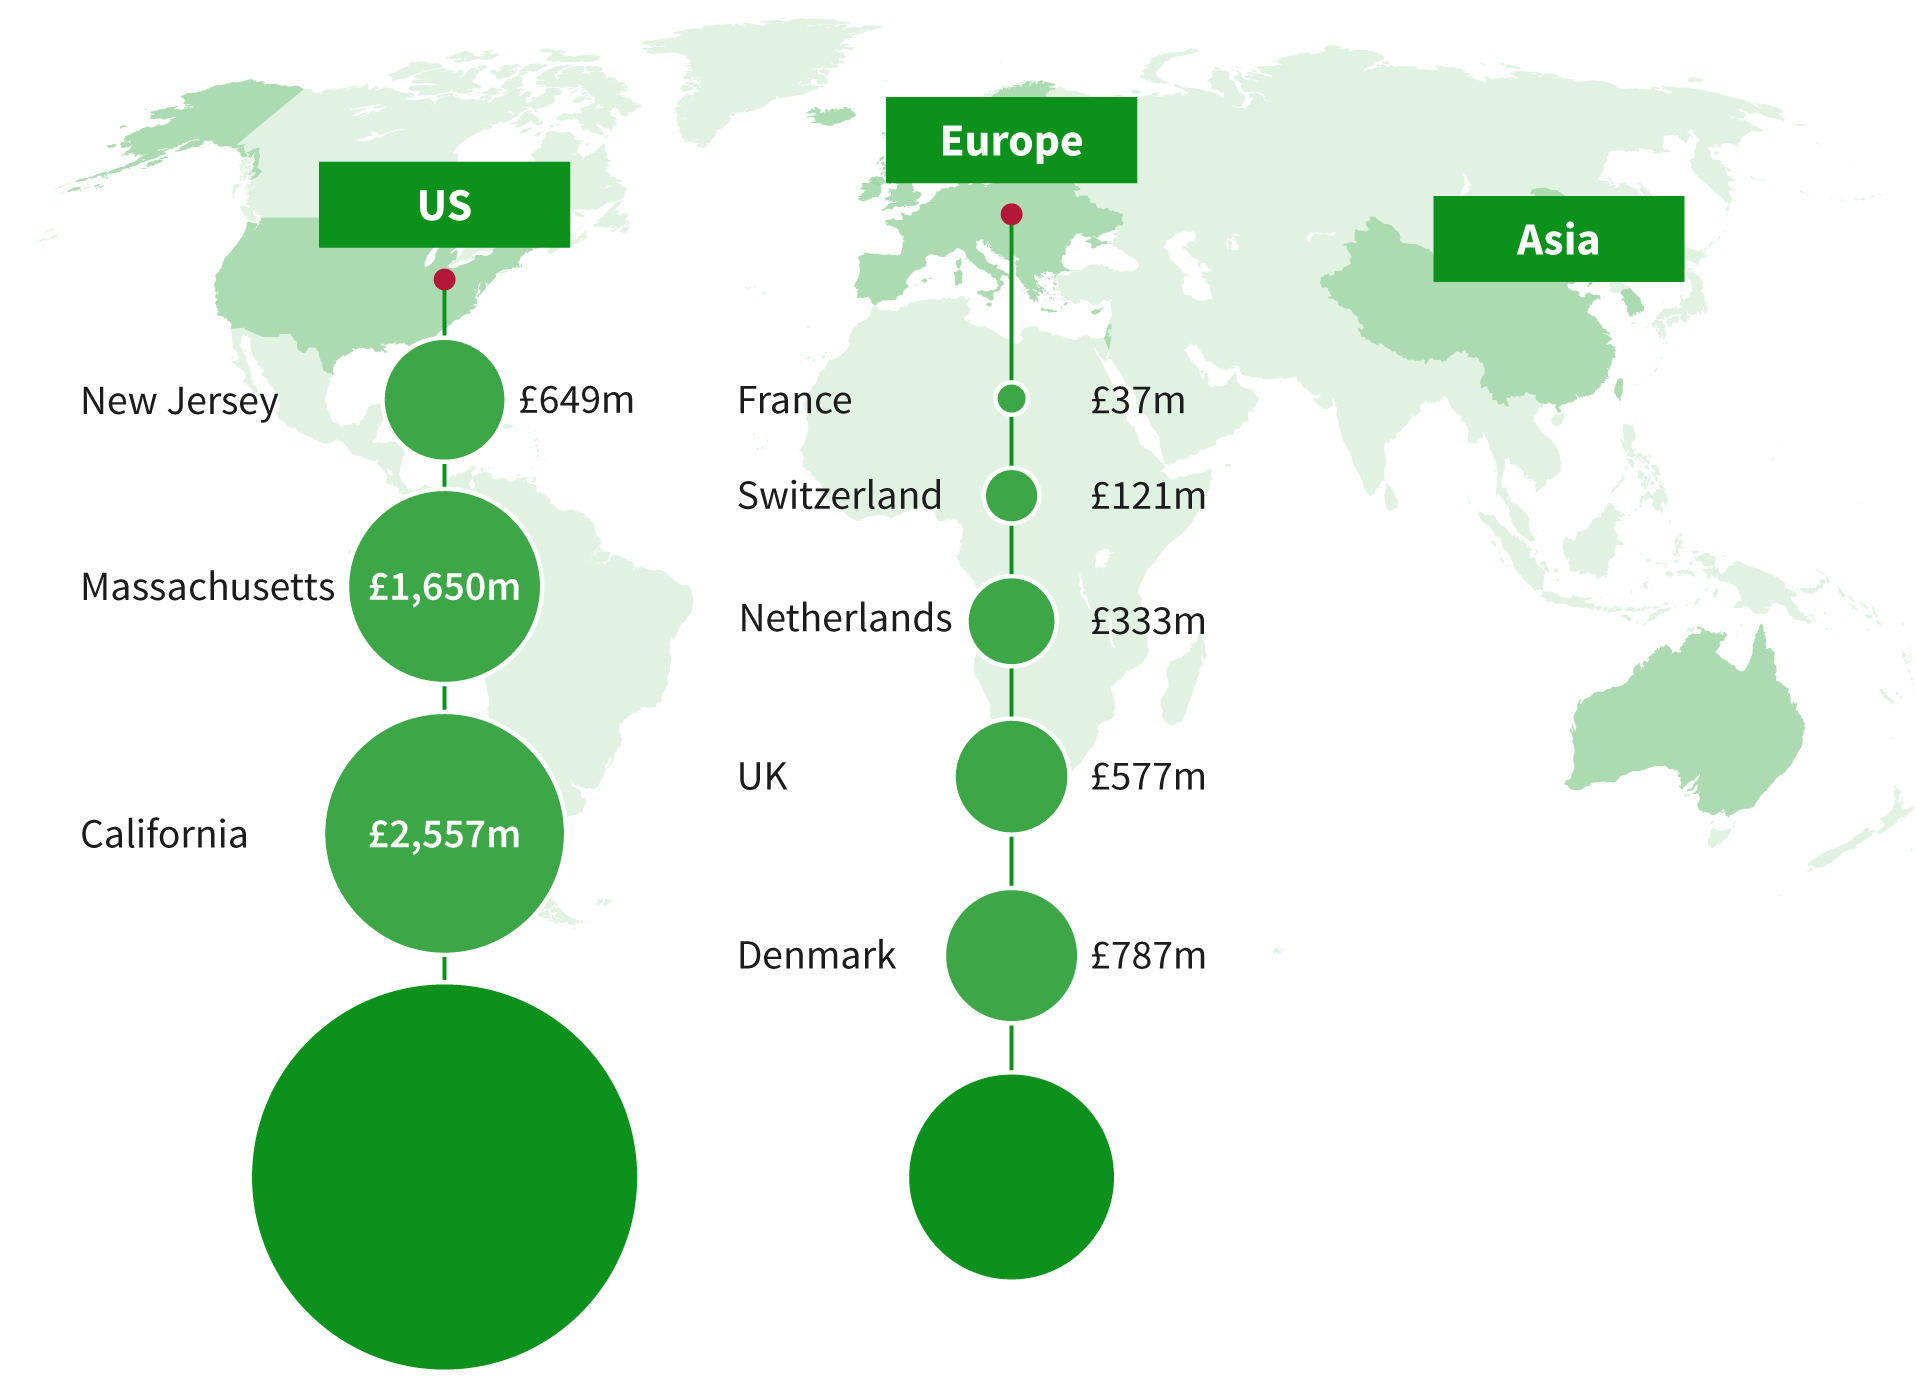
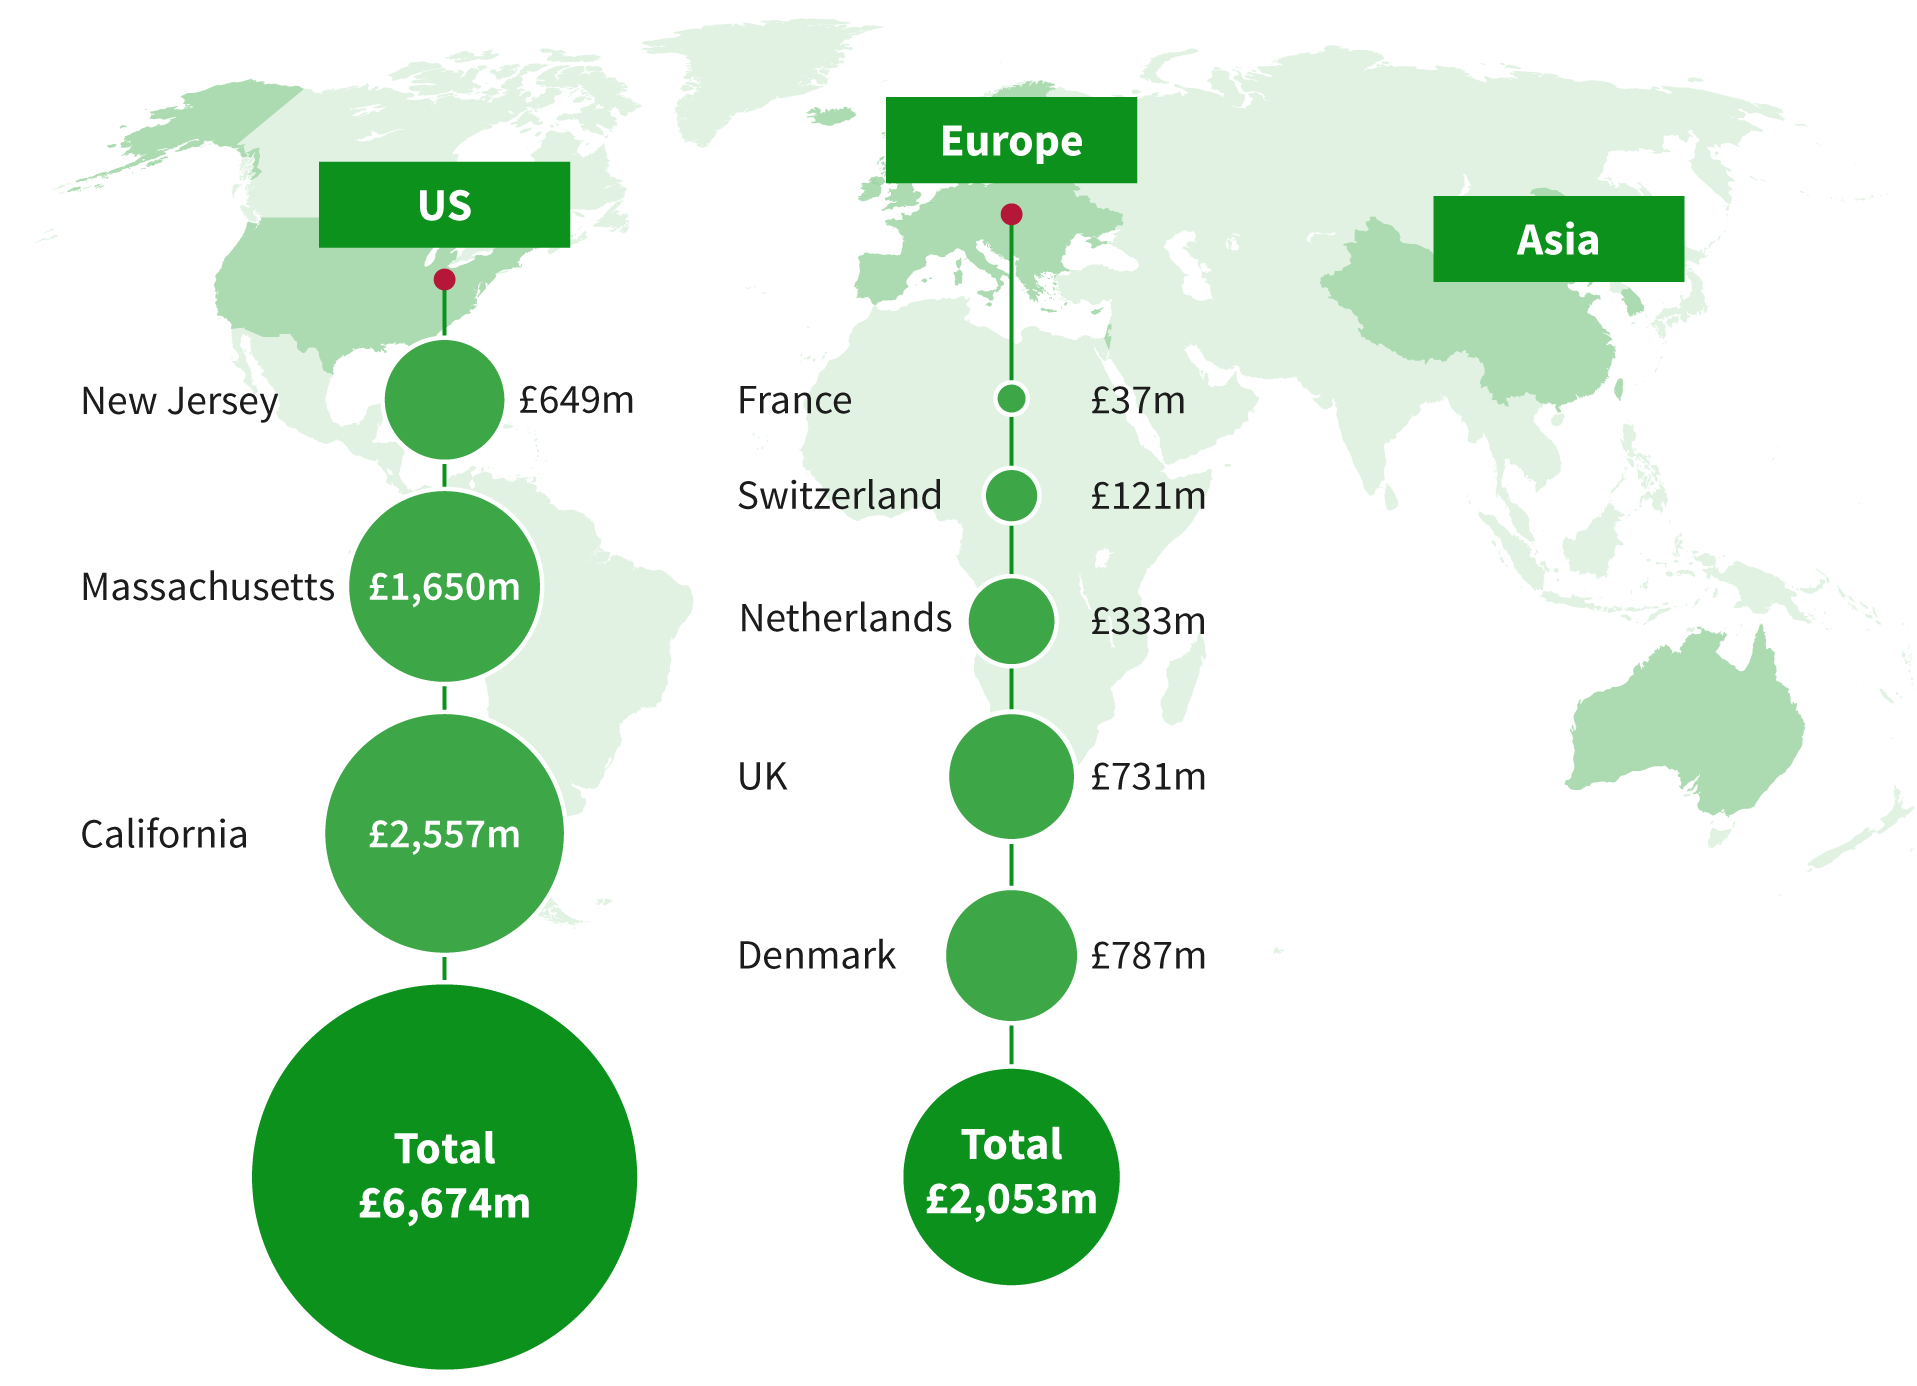
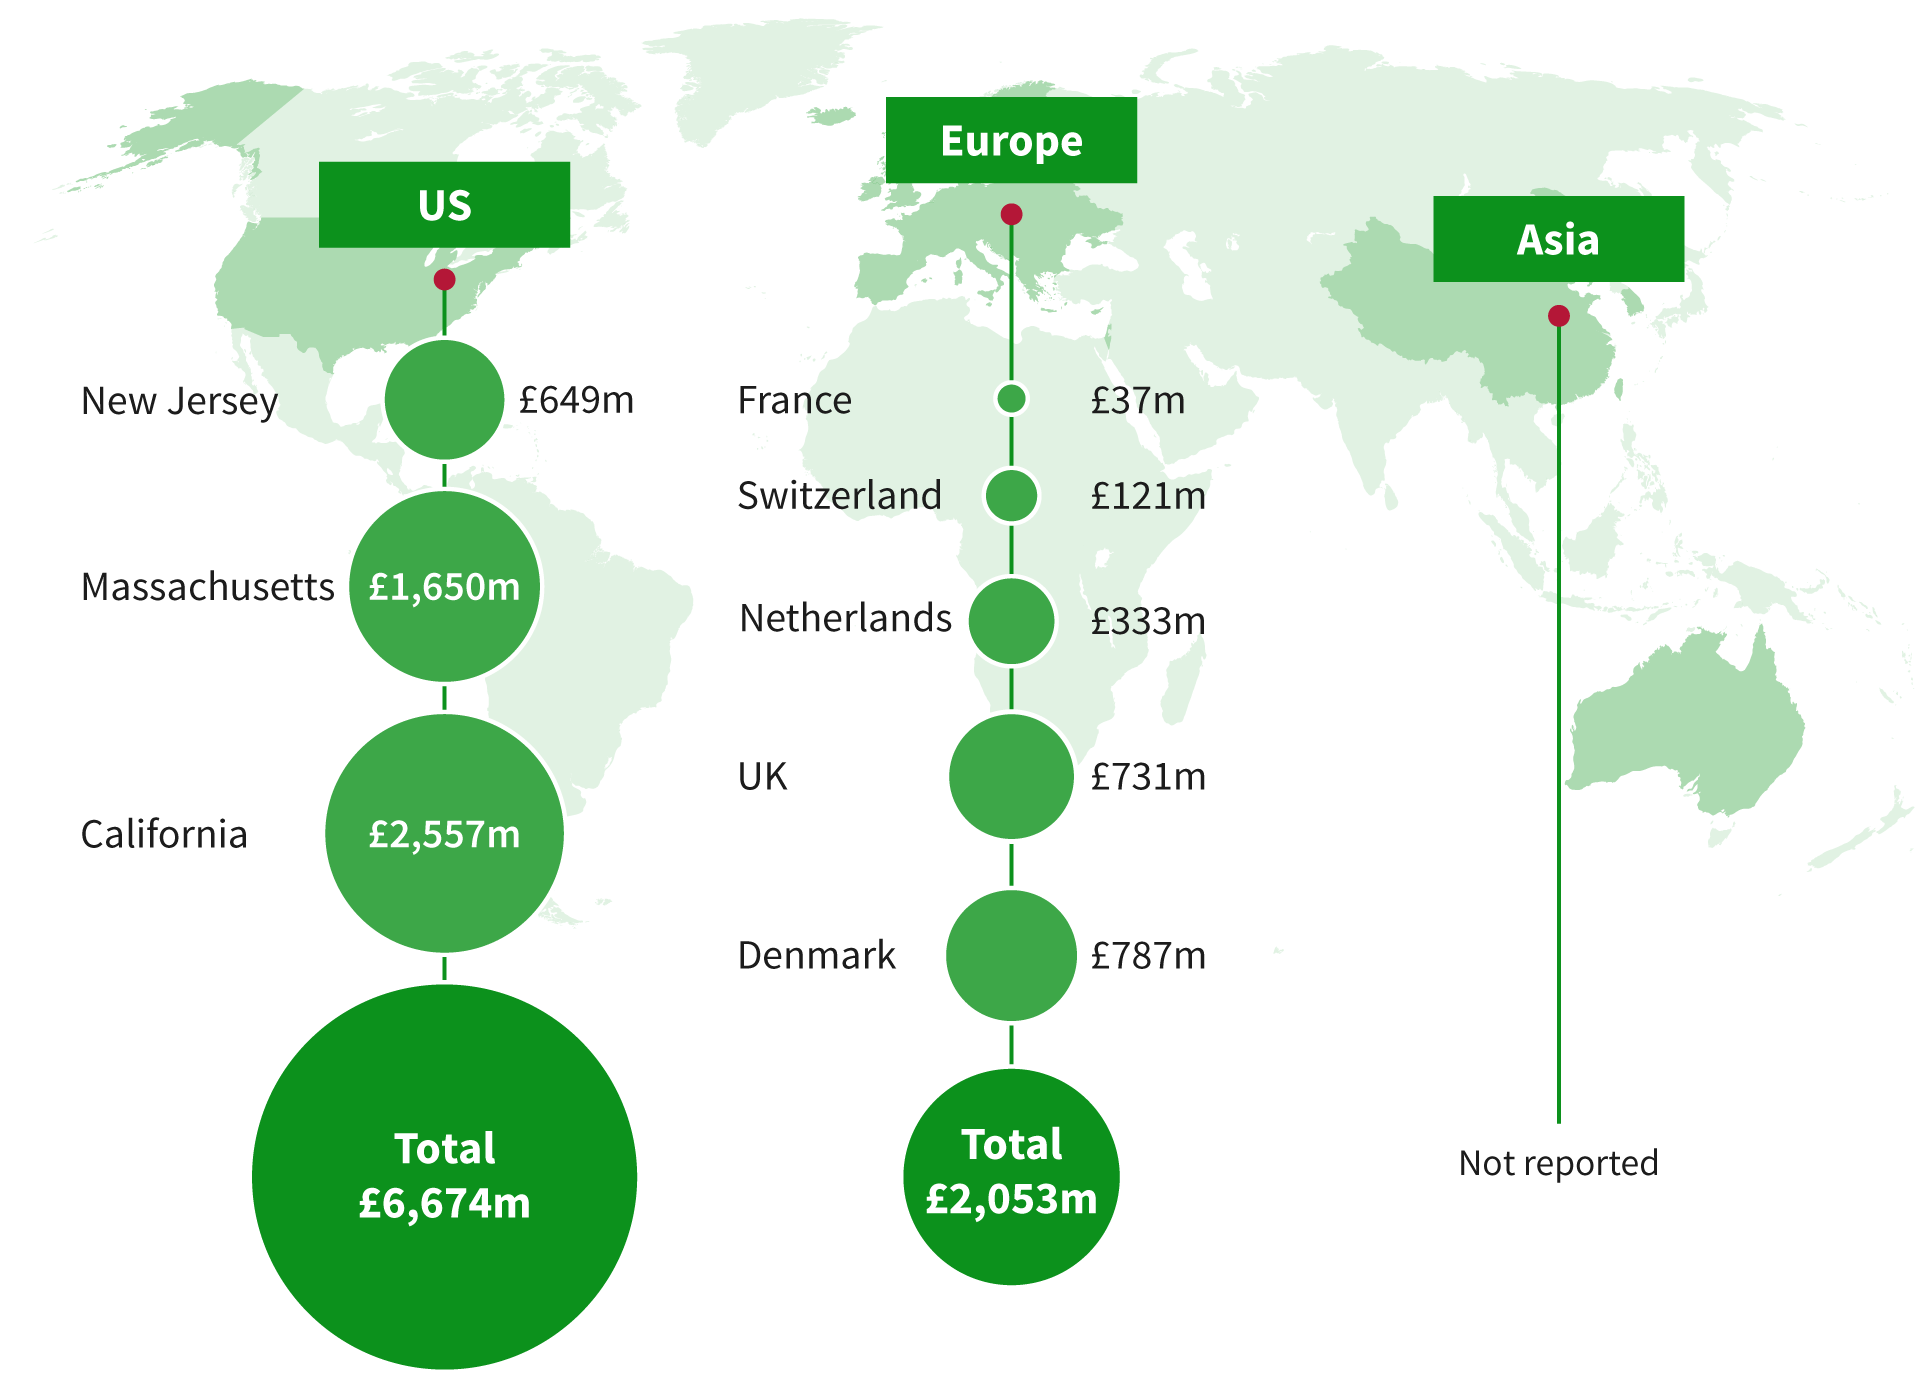
Global follow-on financing efforts saw substantial growth this quarter, marked by a significant upswing across various regions. The European markets exhibited a remarkable 115% increase compared to the previous quarter. Denmark made a notable contribution to this surge, adding an impressive £787 million to the total.
In parallel, the US markets continued to assert their dominance in the sector, raising a substantial £6.7 billion. This robust performance highlights the enduring strength and attractiveness of the US market for biotech investments.
The resurgence of European biotech companies has been a key driver of the positive trend in global public financing. This recovery has significantly contributed to the overall increase in worldwide fundraising activities, with the global total rising by 15% from £7.4 billion in the previous quarter to £8.5 billion this quarter. This upward momentum underscores the growing investor confidence and the vibrant health of the biotech sector on a global scale.

Charts, maps and tables are based on BIA analysis of data from Beauhurst, Biomedtracker, h2Radnor, LSE and Pitchbook, 2024.