
UK biotech financing 2026
July – September 2026
 Overall figures
Venture capital
Public markets
Finance Report 2023
Finance Report 2026 Q2
Finance Report 2026 Q1
Finance Report 2025
Finance Report 2024
 Overview
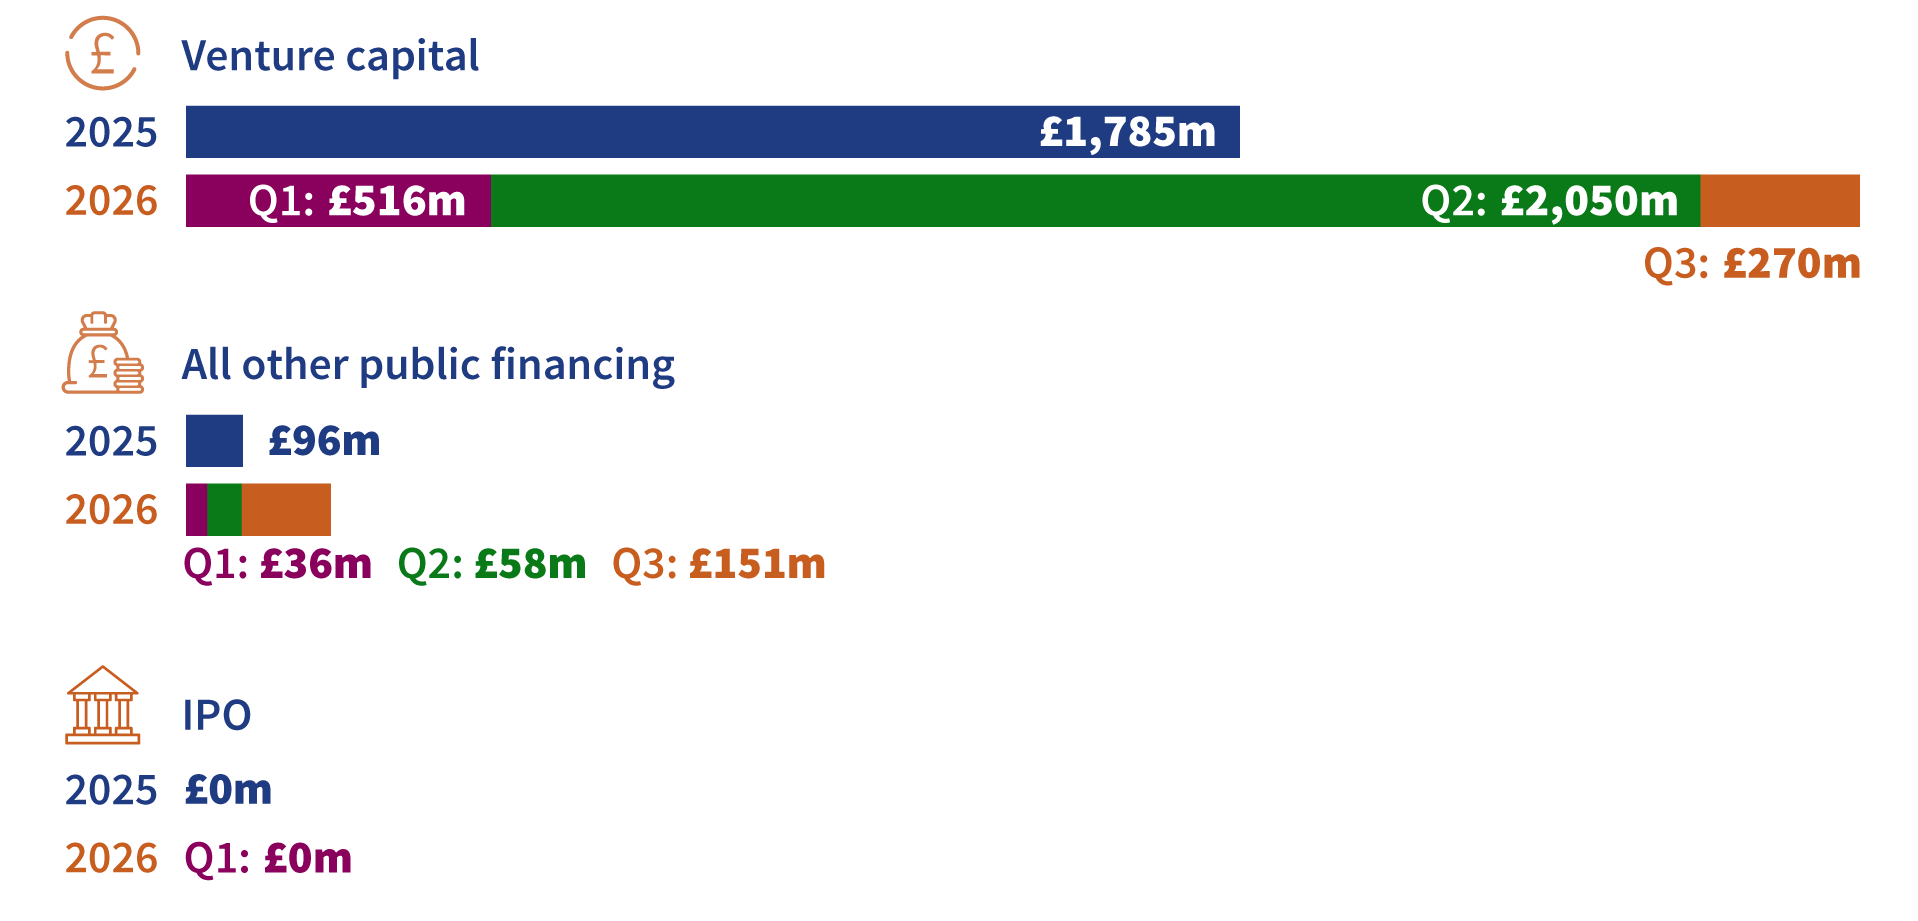
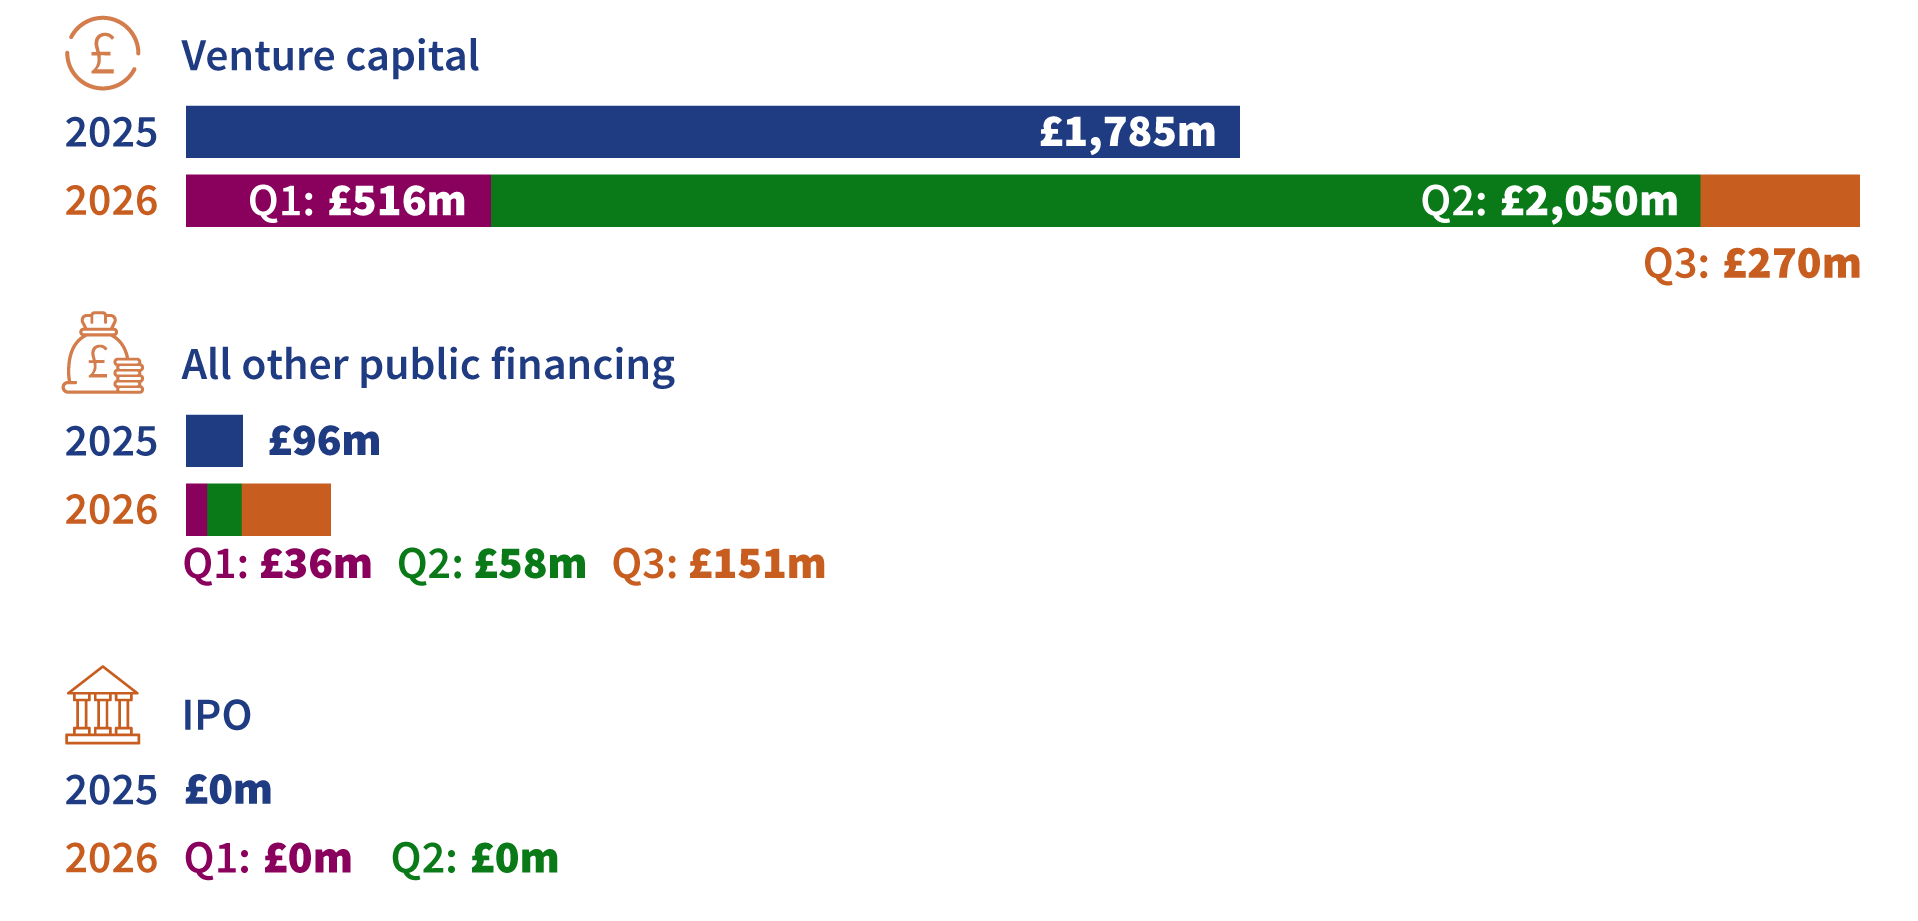
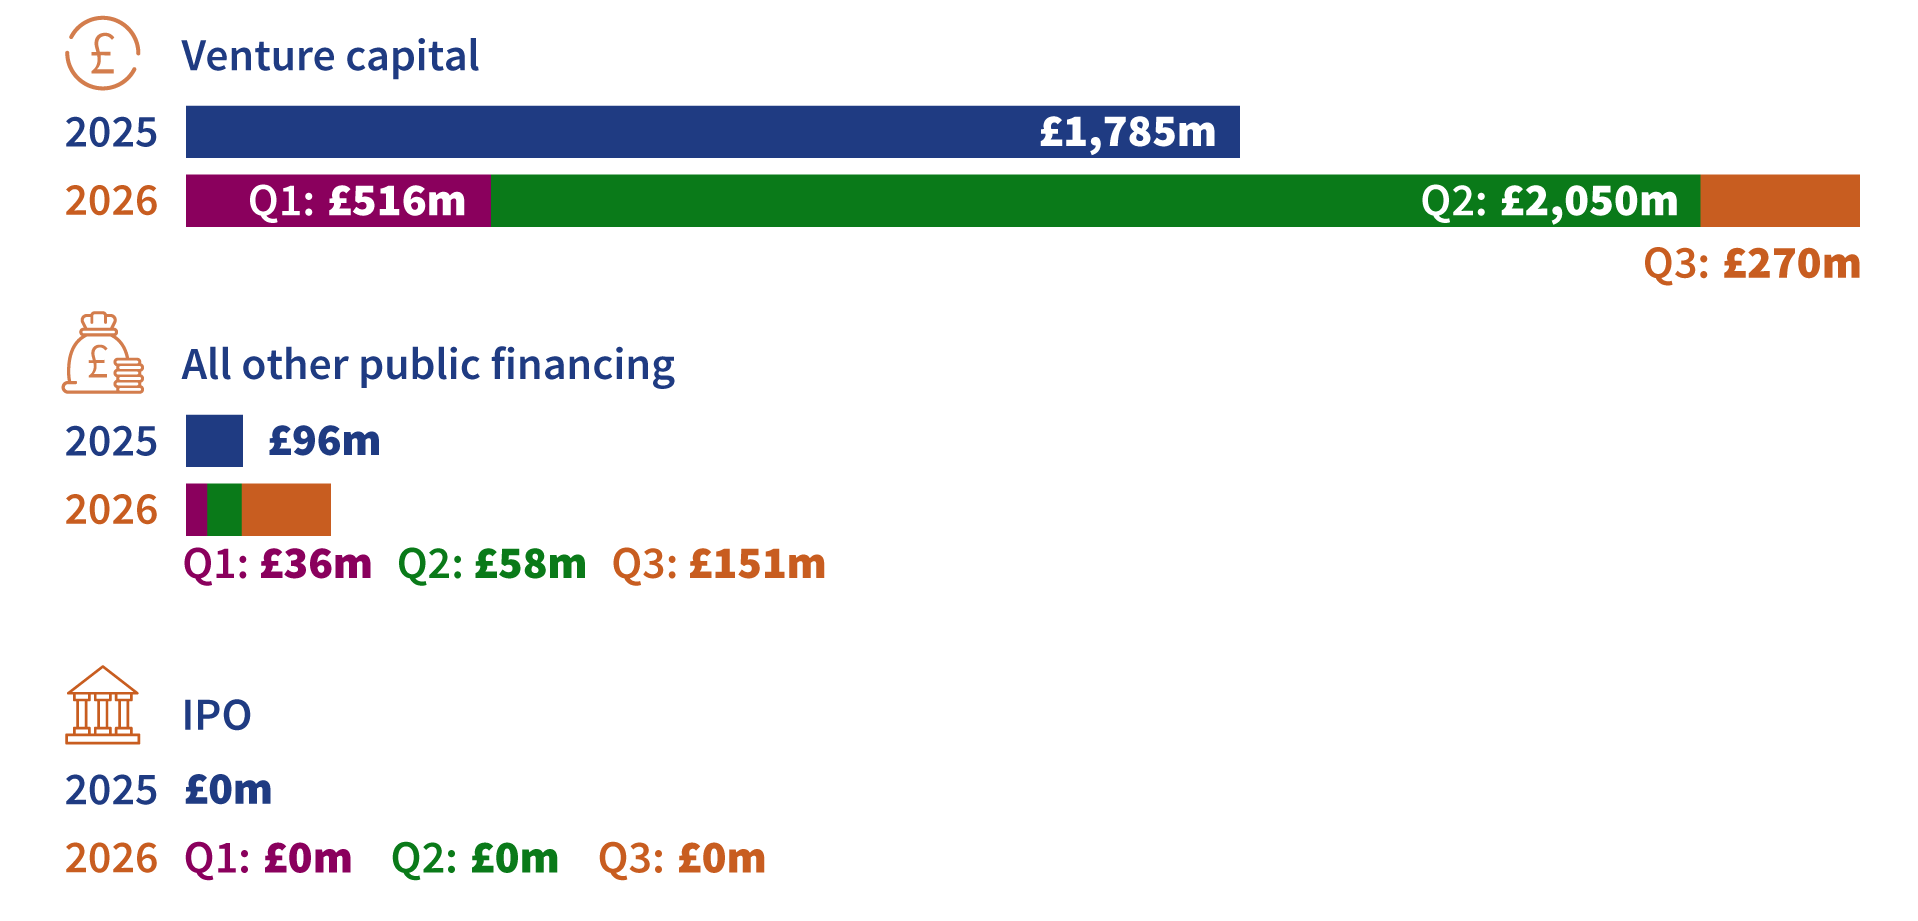
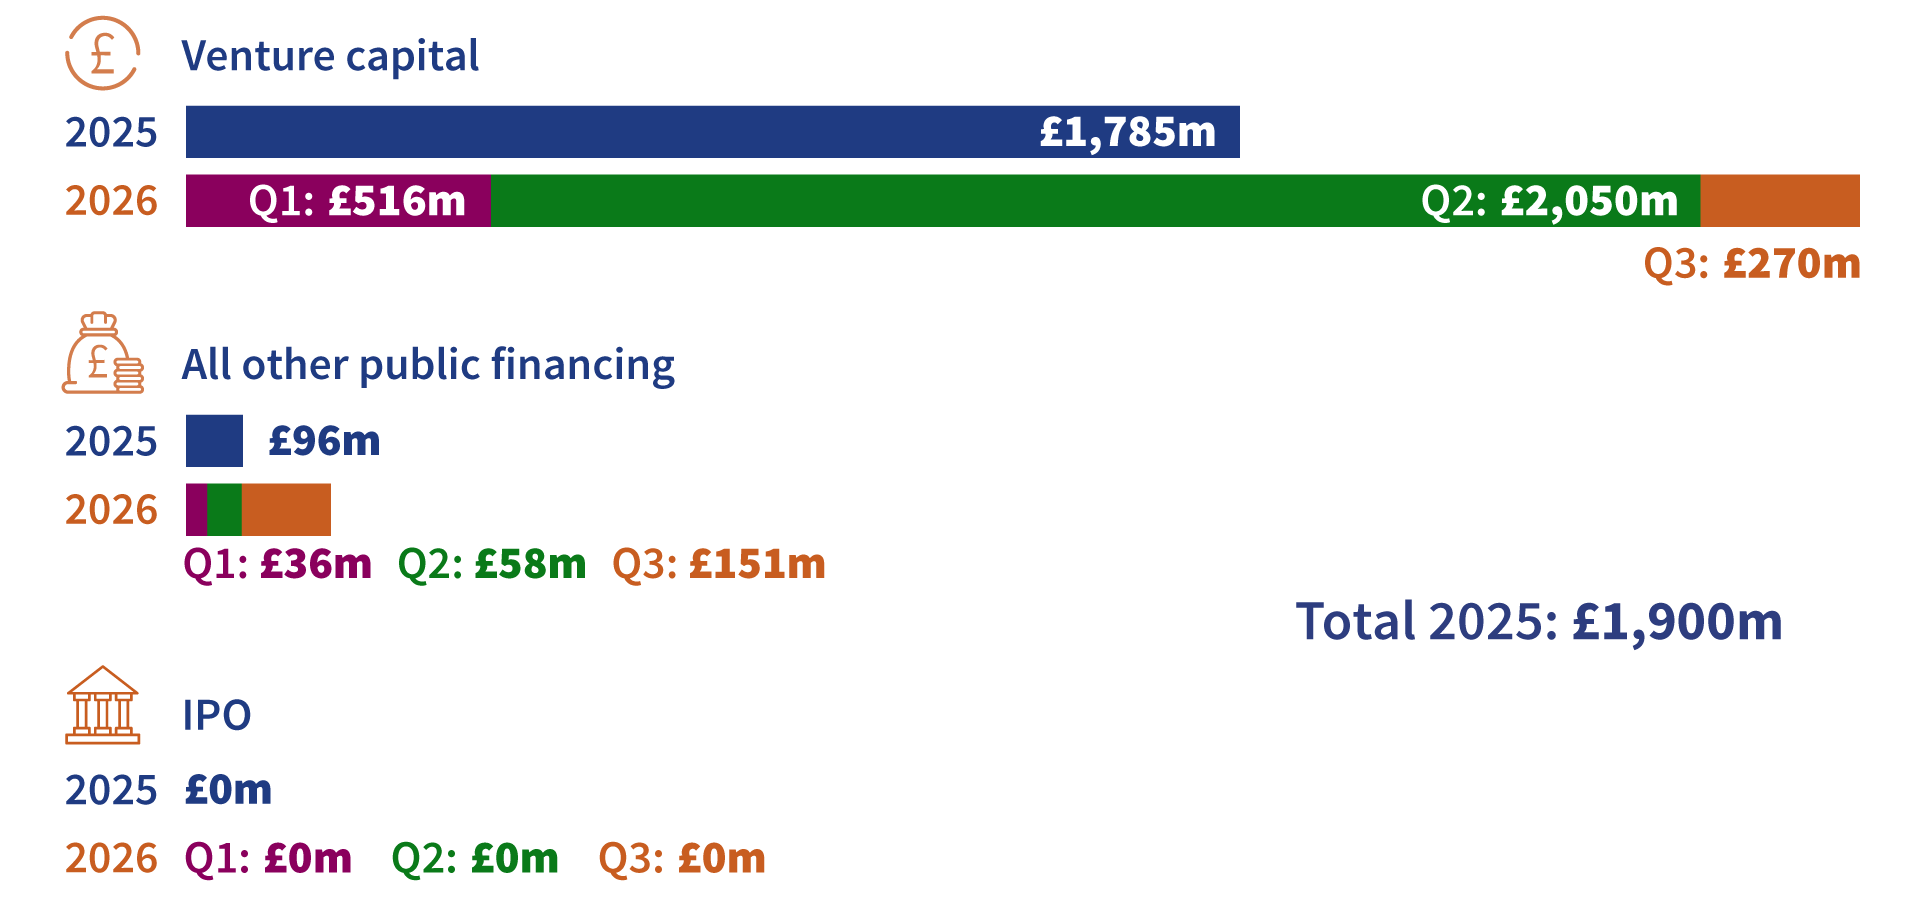
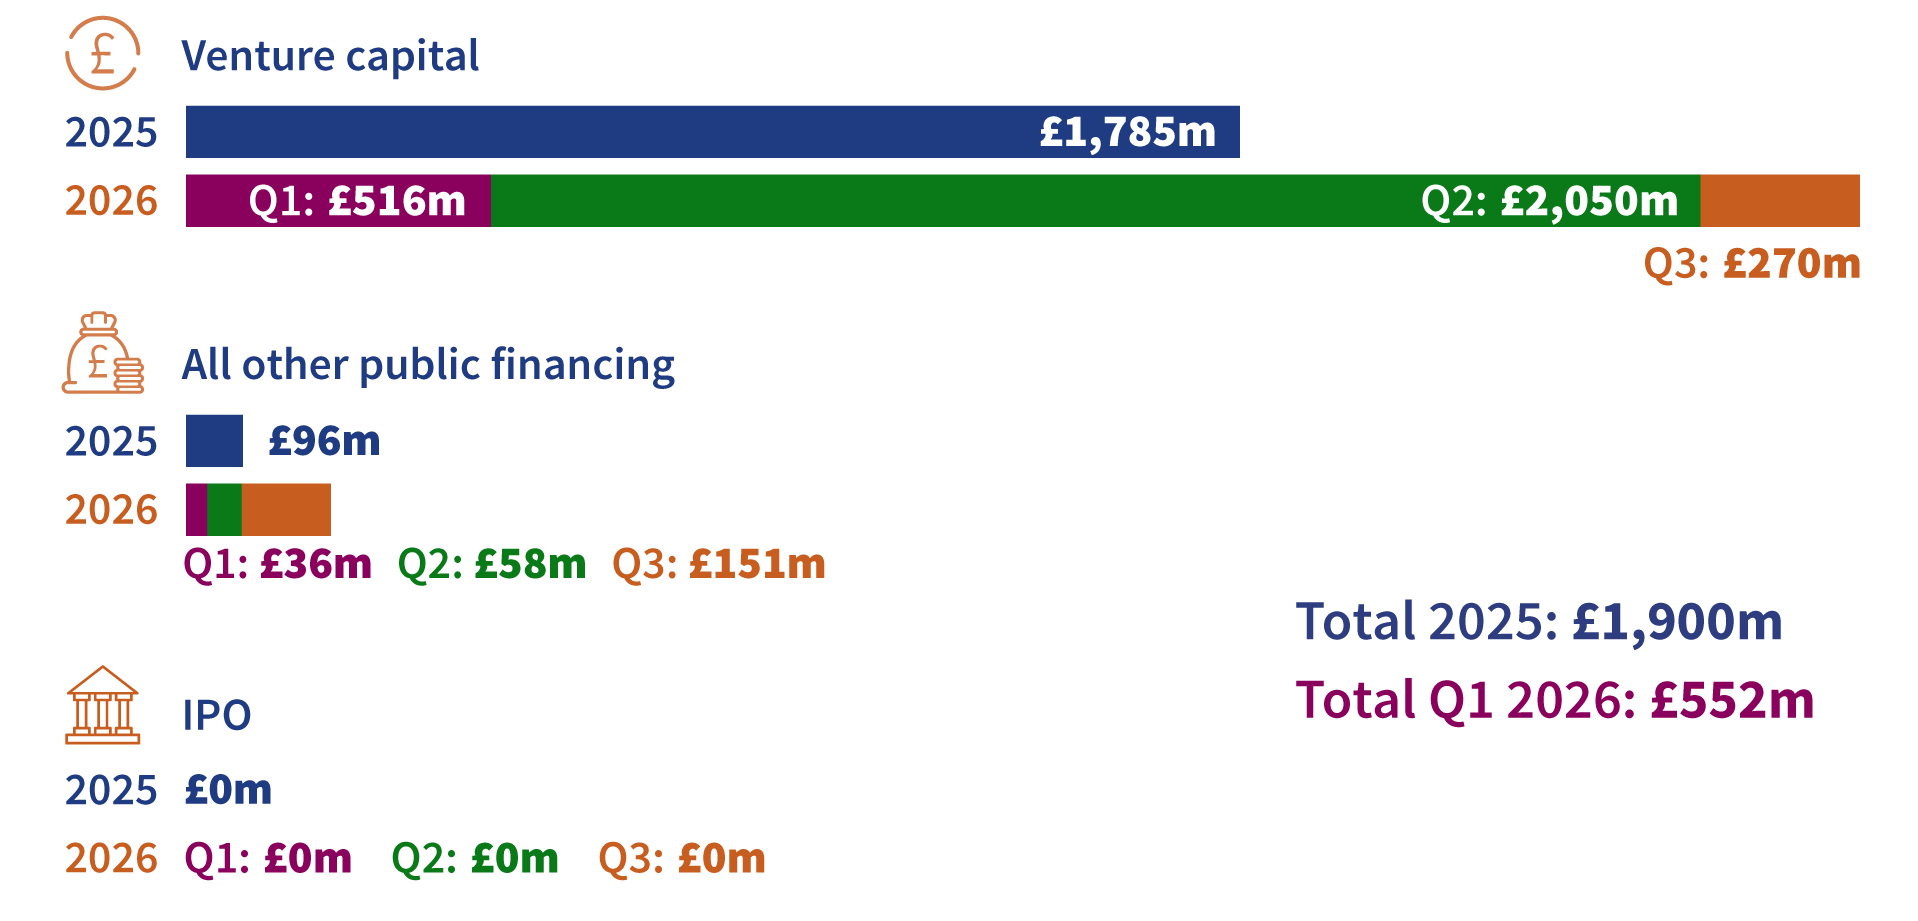
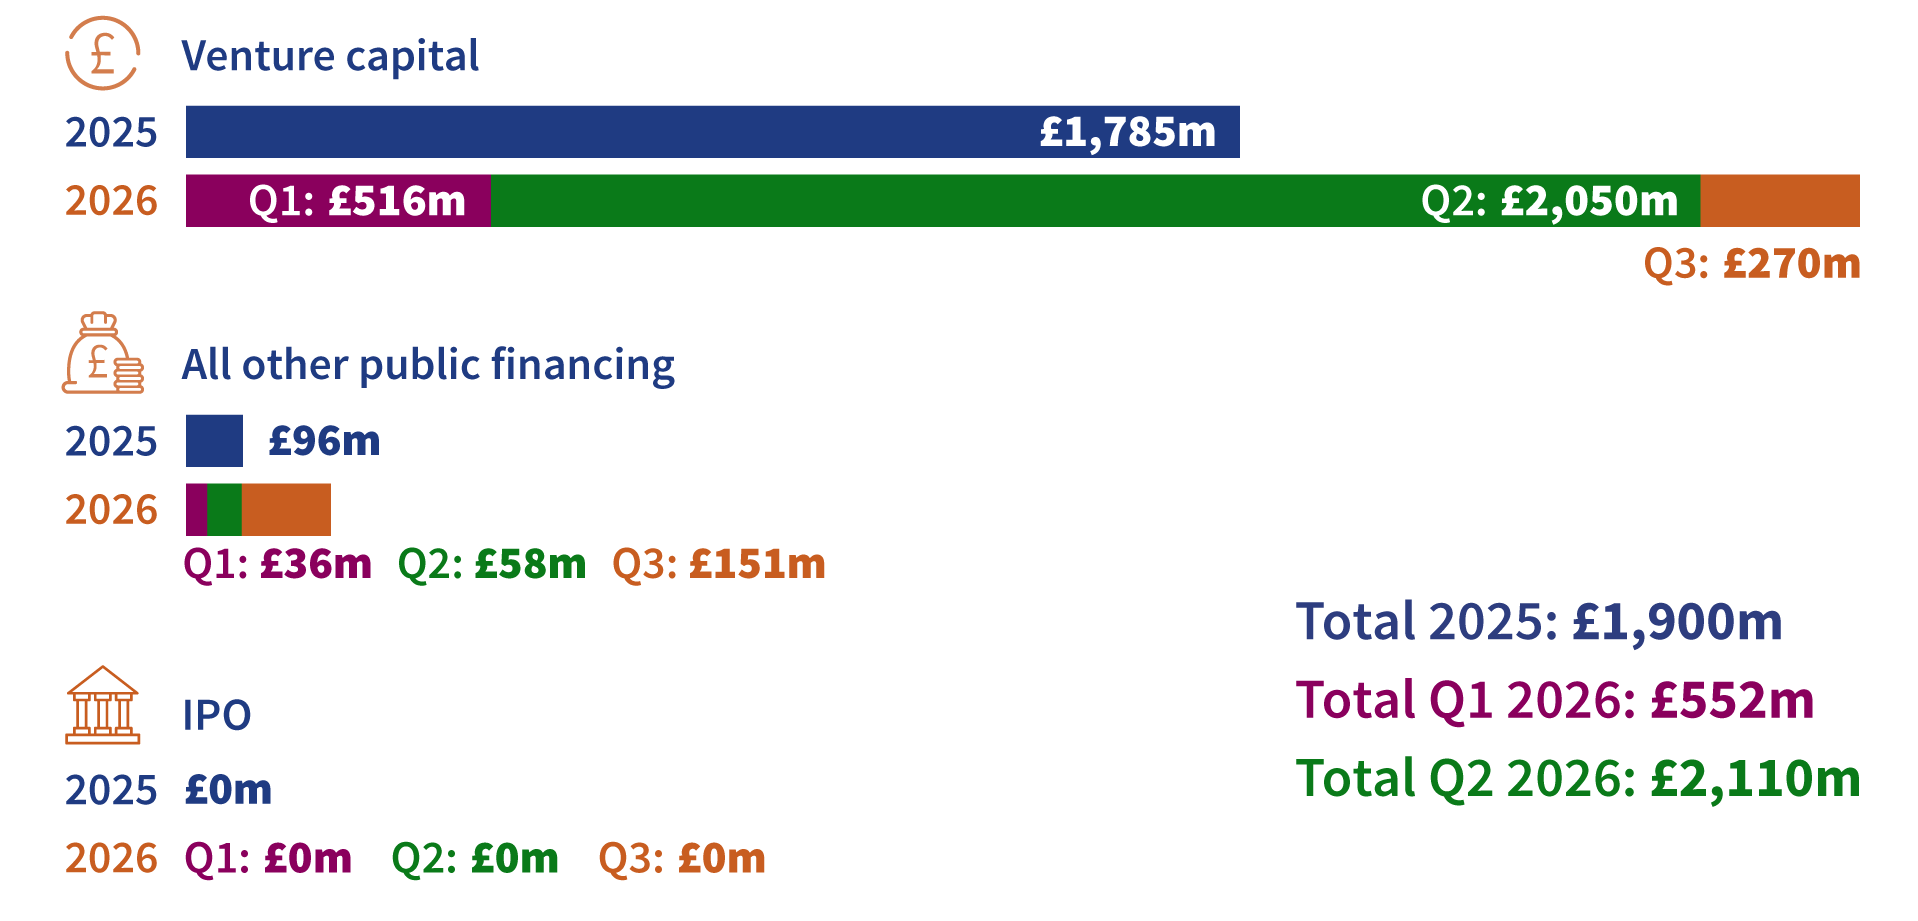
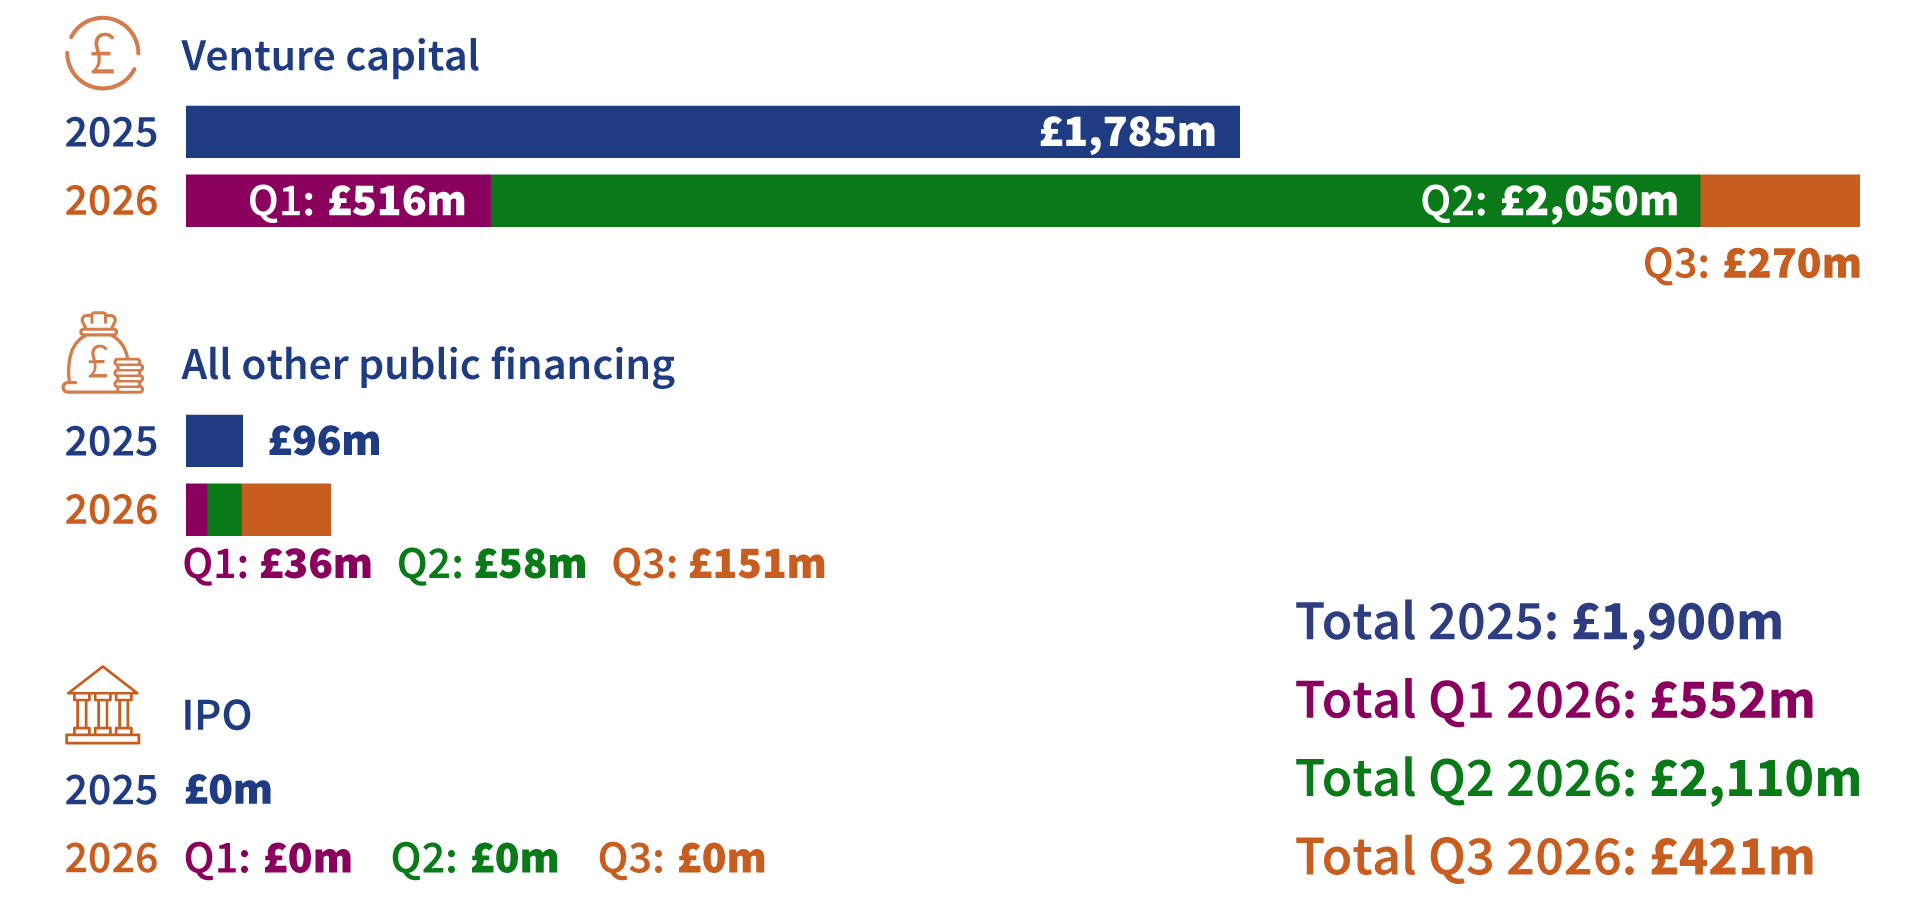
UK biotech companies raised £421 million in total equity financing in Q3 2026, representing a 113% increase from the £198 million in Q3 2025.
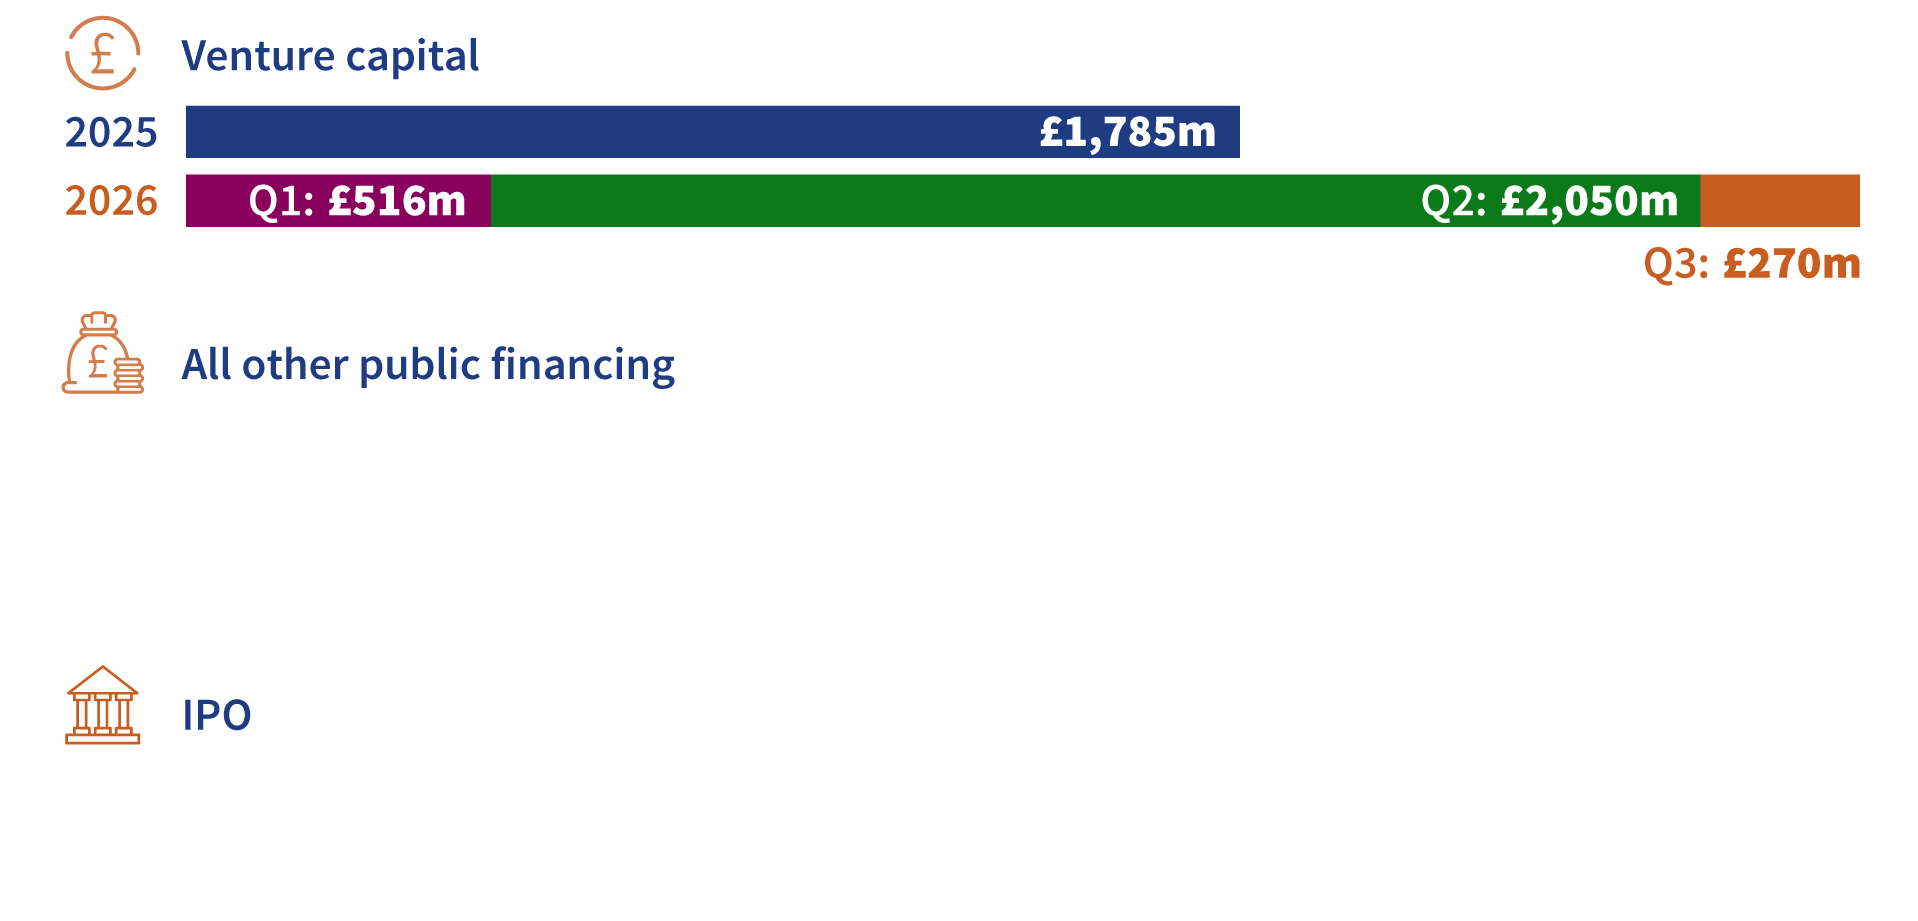
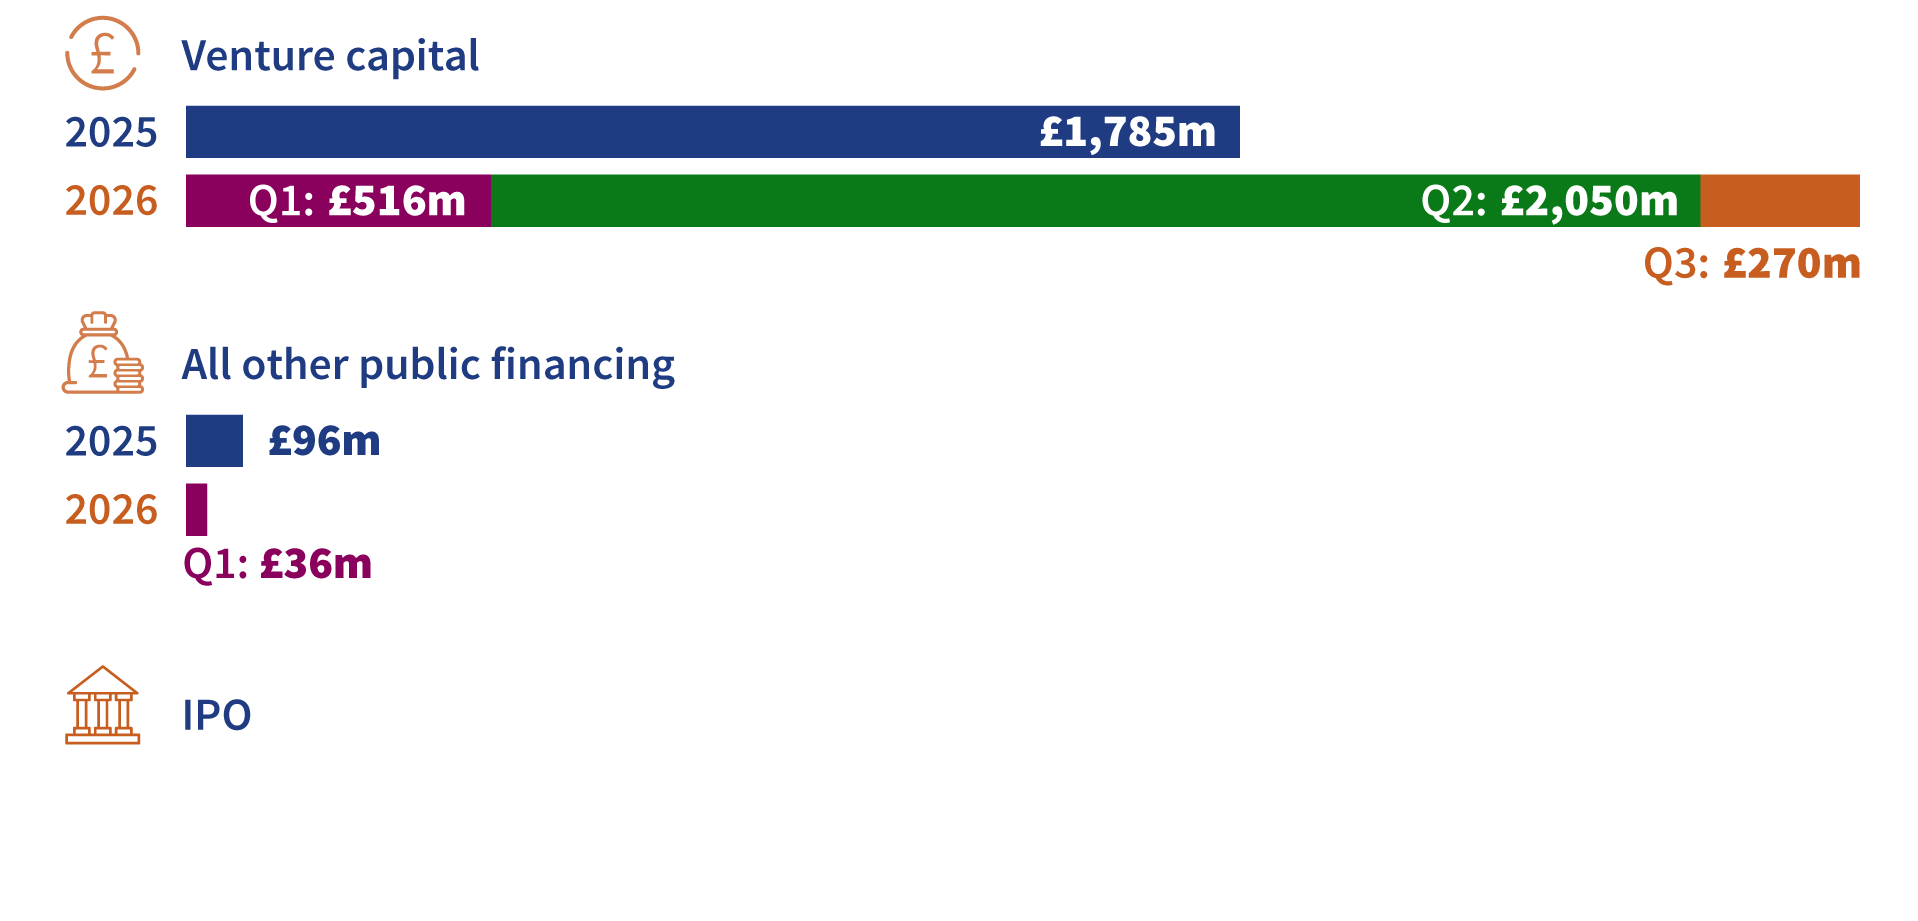
Venture capital investment reached £270 million, up 44% from £187 million in Q3 2025. While this was below Q2 2026, which was dominated by Isomorphic Labs’ £1.6 billion Series B, Q3 performance demonstrates continued UK biotech funding momentum.
Later-stage investment remained the largest contributor, with Series B+ rounds raising £187 million across three deals, accounting for approximately 69% of quarterly VC investment. Basecamp Research led the quarter with a £104 million Series C, followed by Draig Therapeutics (£49 million) and Mironid (£34 million), both at Series B. Early-stage funding remains challenged, with only £12 million in four visible seed rounds in the quarter.
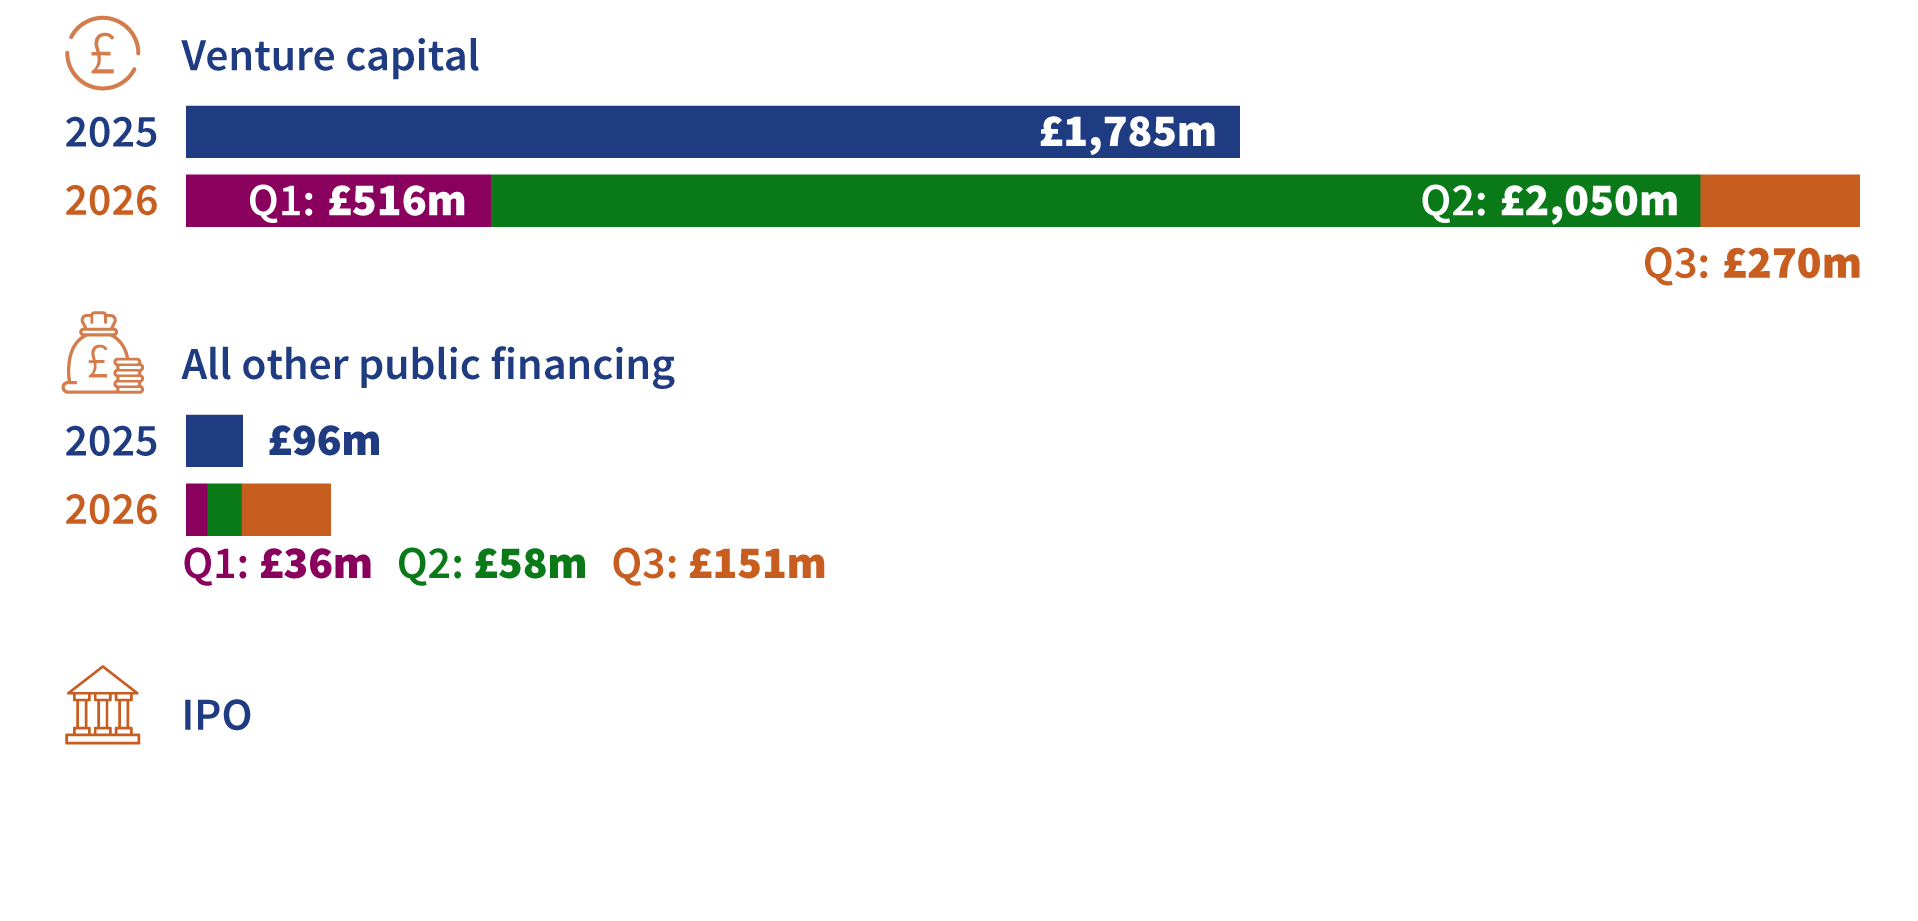
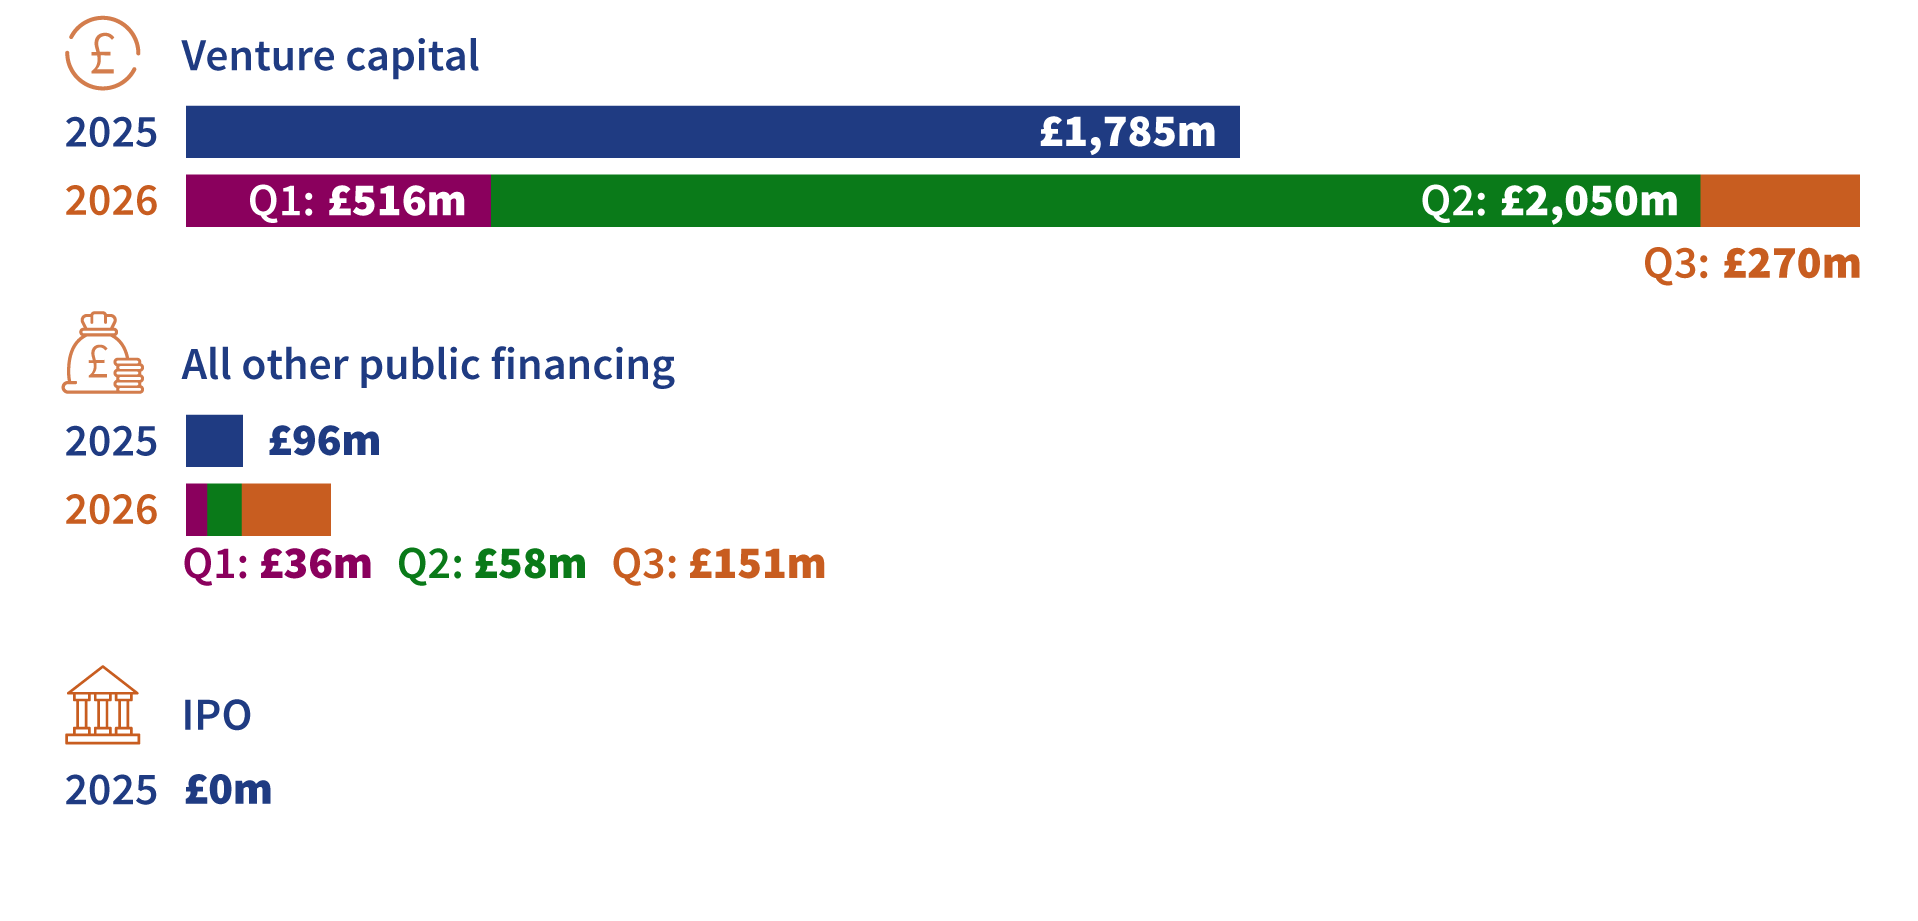
Public market fundraising also improved, with follow-on financing increasing from £11 million in Q3 2025 to £151 million in Q3 2026, driven primarily by Silence Therapeutics’ £130.3 million NASDAQ raise.
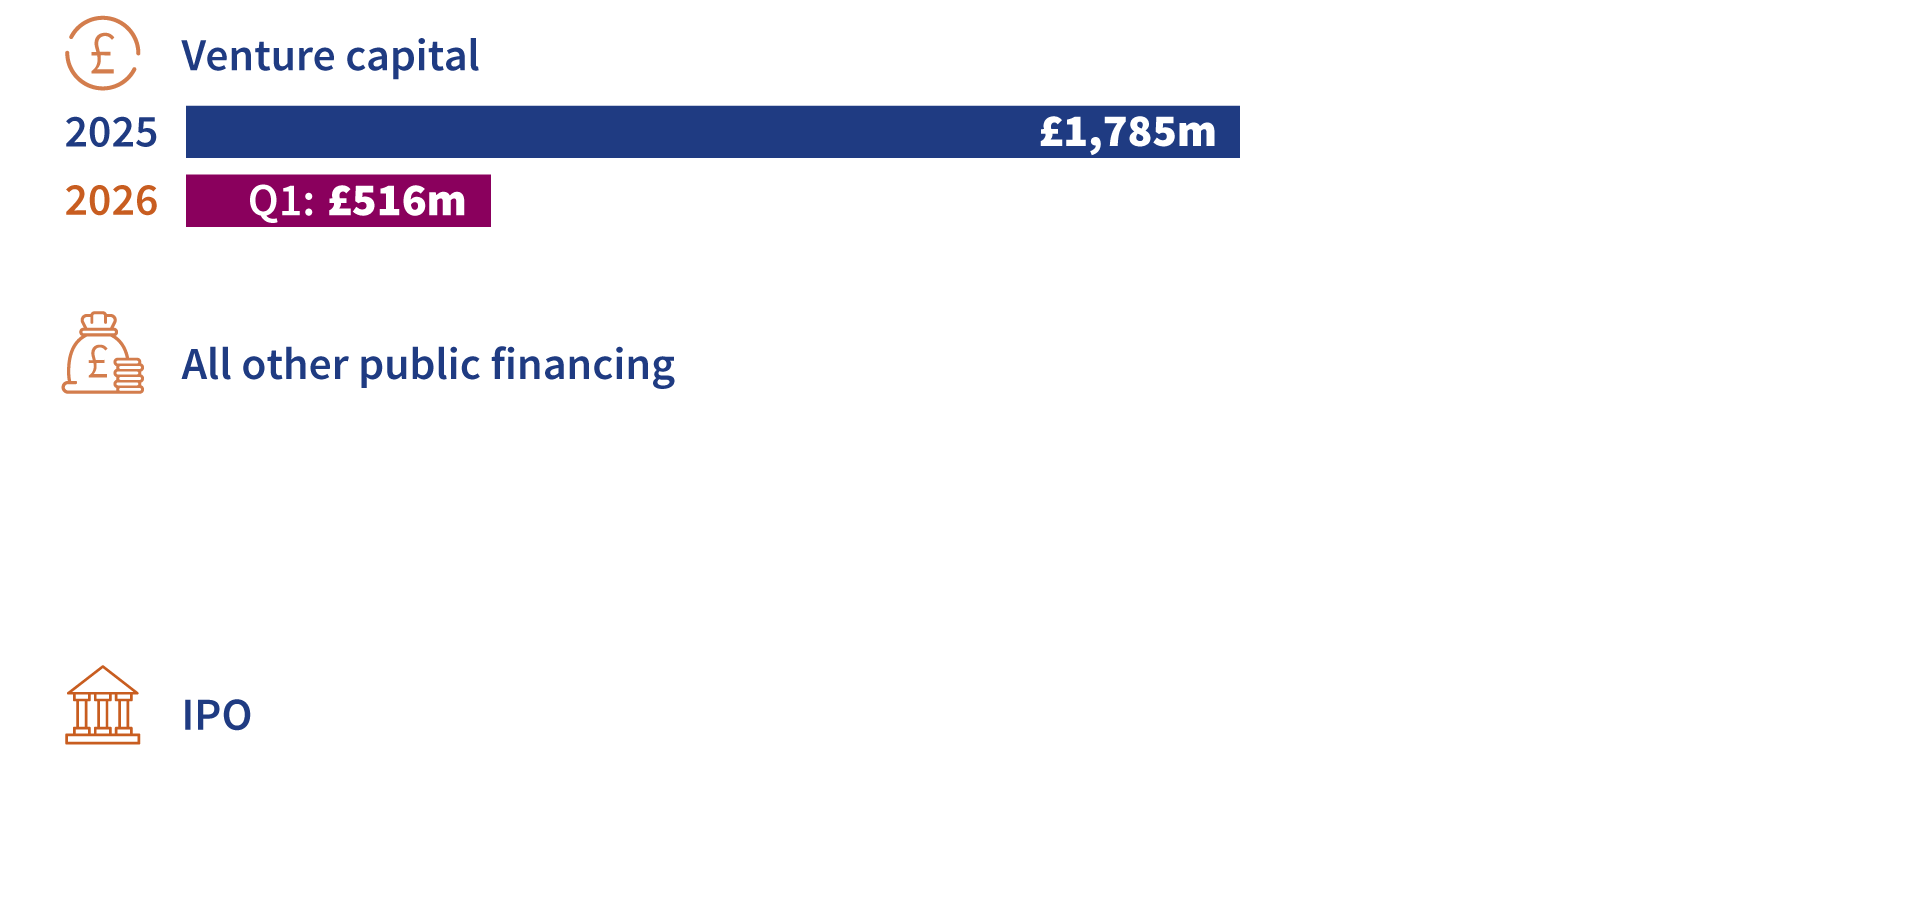
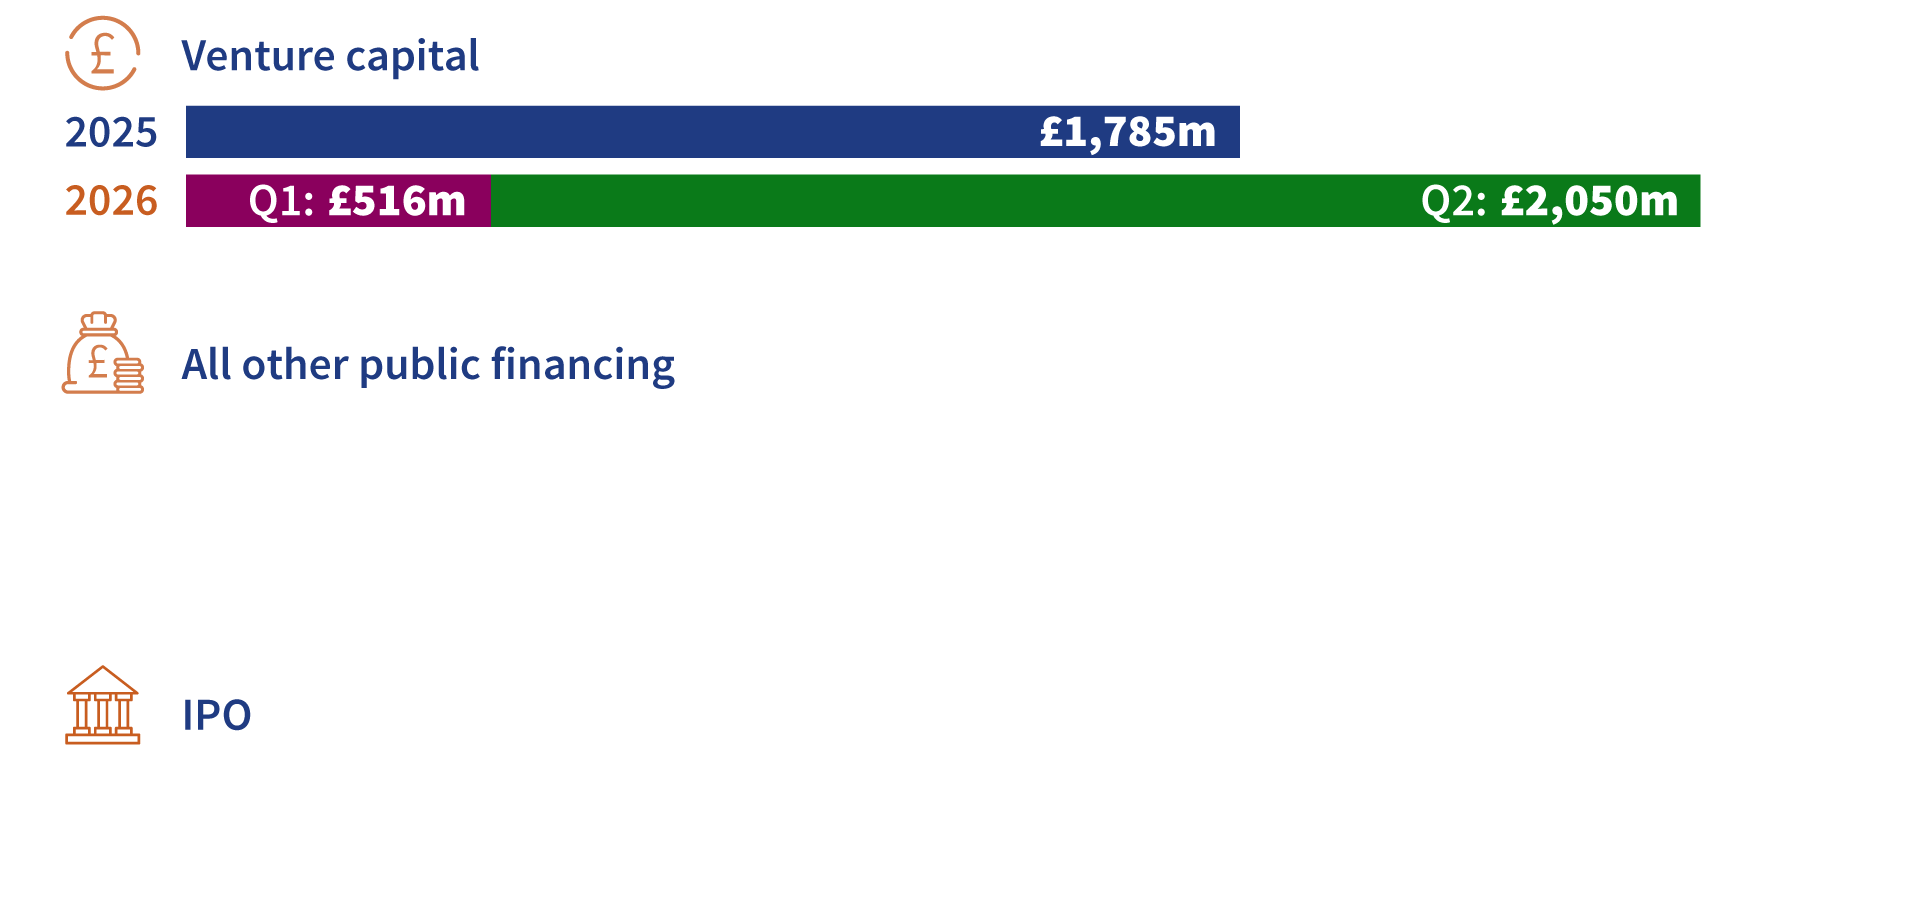
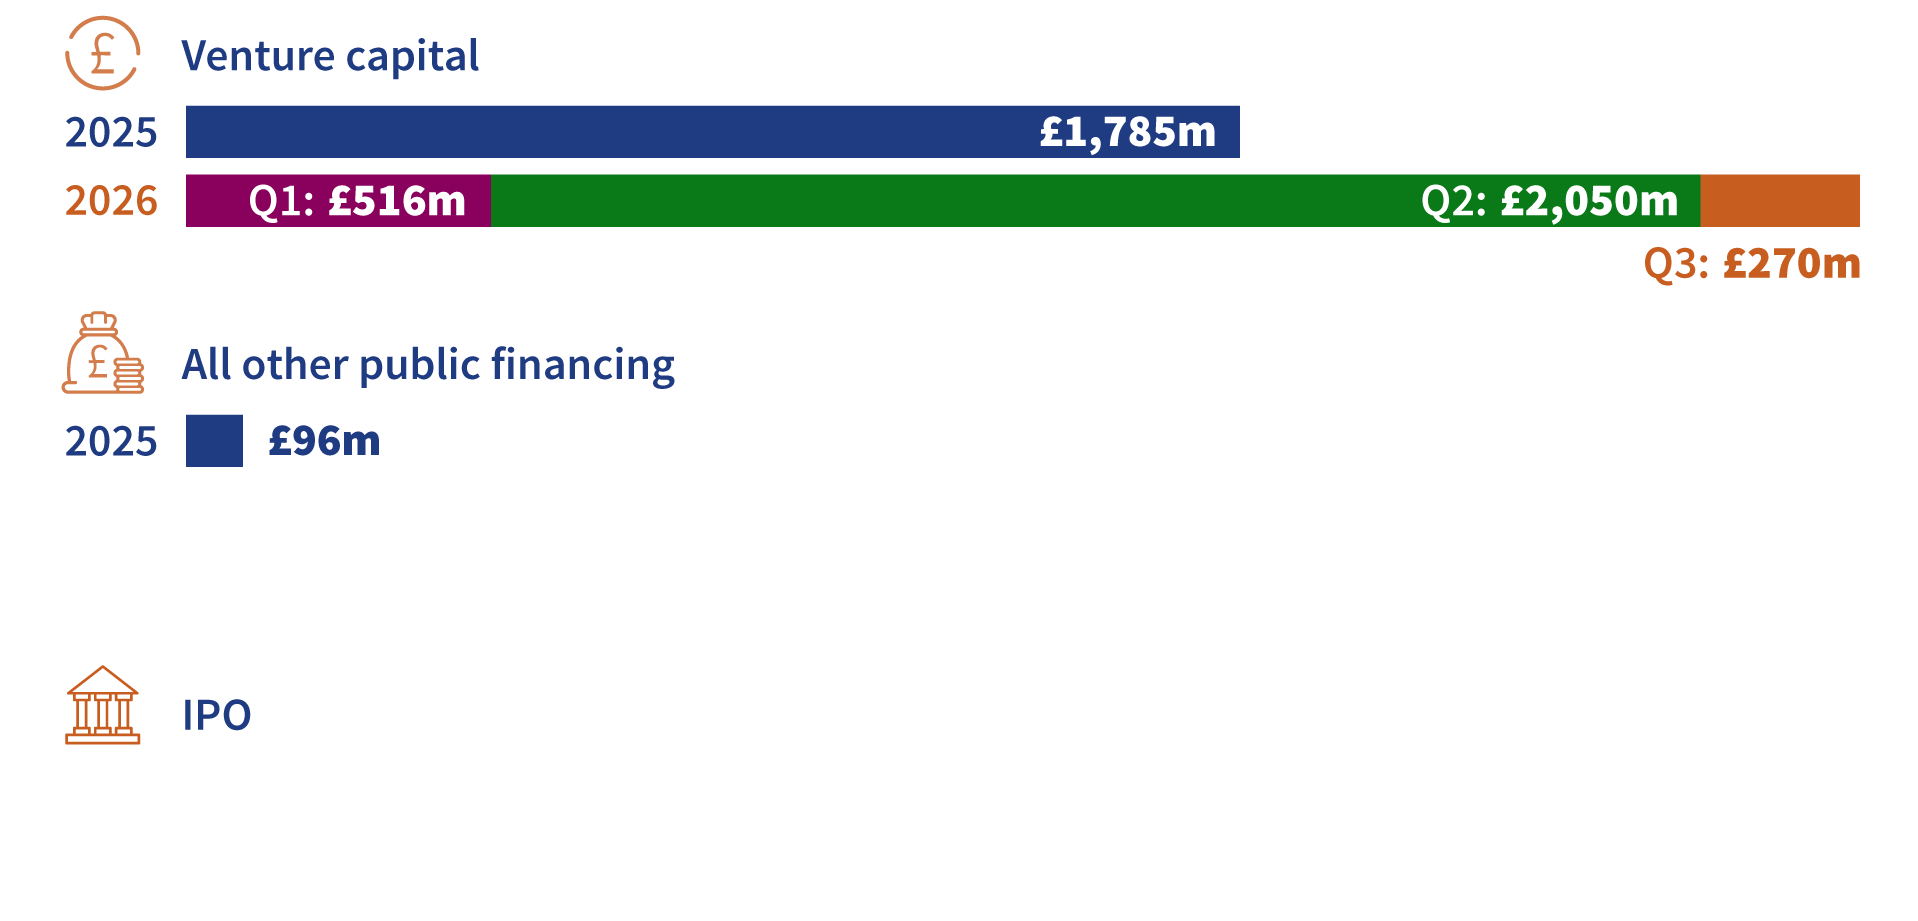
2025 and 2026 figures at a glance
Chris Molloy
CEO, BIA
UK biotech has now raised more venture capital in nine months than in any full year from 2022 to 2025. At the end of September, the total stood at £2.8 billion, with a quarter still to go. The third quarter added £270 million, which was less than Q2 but 44% more than over the summer period last year. That increase is ahead of the US, which was up by 13%, while the rest of Europe dipped slightly.
Basecamp Research led the quarter with a £104 million Series C, which it will use to train its next generation of AI models and drive AI-designed medicines towards the clinic. NVIDIA, which counts Basecamp among the UK start-ups it backs, announced new planned investments in two more London AI biology companies this month. That’s what sets the UK apart: it’s where life sciences and AI come together, and big pharma, big tech and US investors are all backing companies here.
There are weak spots. Mid-sized rounds were thinner on the ground this quarter and seed funding fell to just £12 million across four deals. Silence Therapeutics’ £130 million raise on NASDAQ accounts for almost all the quarter’s follow-on money, and the UK has now gone 17 quarters without a biotech IPO.
But Q4 has started strongly. In the first half of October, OMass Therapeutics closed a $310 million (£230 million) Series C and Microbiotica announced a £36 million Series C led by the British Business Bank (BBB). Together those two rounds nearly match the whole of Q3.
The pattern this year is clear: UK science attracts expert global capital, but we are missing an opportunity to see returns recycled in our own ecosystem, because too few British investors are taking part. This is true in both private and public markets. It is not a challenge unique to the UK: across Europe, companies looking to list are turning to NASDAQ, where the deepest pool of biotech capital sits. Redx shows what a good outcome can look like, with the British Business Bank backing its Series A to keep its headquarters and research in Cheshire as it accesses US public markets to raise the capital it needs to grow.
Our focus is on making sure companies at all stages of development can access the finance they need to grow, and that the UK benefits from the upside. The Government has a vital role to play in getting the environment right for that, and in incentivising wealth creators to recycle their gains. Our message to policymakers is clear: deploy public R&D grants at pace, in collaboration with expert investors, to make the most of precious taxpayers’ money; back the British Business Bank with the resources it needs; and incentivise pension funds to invest, so the public purse doesn’t have to.
UK biotech companies can then make the most of that increased investment and drive economic activity in the UK, if they have preferential access to UK R&D infrastructure and are supported by a conducive tax system, with enhanced R&D tax credits at its core.
 Venture capital
UK biotech venture capital investment reached £270 million in Q3 2026, exceeding the £187 million recorded in the same quarter in 2025 by 44%. Investment was also higher than Q3 2022 (£240 million), although below the corresponding quarters in 2023 (£486 million) and 2024 (£659 million).
While Q3 lacked a deal of the scale of Isomorphic’s in the previous quarter, investment remained concentrated, with the five largest transactions accounting for approximately 89% of total venture capital raised.
Later-stage financing accounted for the largest share of UK biotech venture capital in Q3, with three Series B+ deals raising £187 million, representing approximately 69% of total investment. The average deal size was £62.4 million, compared with approximately £75 million in Q2 when excluding Isomorphic Labs’ exceptional financing.
Series A financing totalled £59 million across four deals in Q3, compared with £190 million across four deals in Q2 and £154 million across five deals in Q1. While deal activity remained relatively stable, the average round size fell to £14.7 million, suggesting that the decline in investment was primarily driven by smaller transactions rather than fewer deals.
Seed-stage investment declined to £12 million across four deals, compared with £51 million across eight deals in Q2 and £42 million across ten deals in Q1. Unlike Series A, seed financing saw a reduction in both deal volume and average round size, which fell to £2.9 million.
Meanwhile, undisclosed rounds accounted for eight of the quarter’s 19 deals, compared with seven in Q2, although their combined value was relatively modest at £12 million. Overall, Q3 saw fewer early-stage transactions and smaller average rounds than earlier in 2026, while later-stage financing continued to attract most of the investment.
Top five UK biotech venture capital deals
| Company | Date | Round | Value (£m) |
|---|---|---|---|
| Basecamp Research | 23/09/2026 | Series C | 104 |
| Draig Therapeutics | 14/07/2026 | Series B | 49 |
| Mironid | 05/08/2026 | Series B | 34 |
| Redx Pharma | 29/08/2026 | Series A | 27* |
| Alchemab Therapeutics | 09/07/2026 | Series A | 25 |
The five largest venture capital deals in Q3 2026 raised a combined £239 million, accounting for approximately 89% of total quarterly investment. Basecamp Research led the quarter with a £104 million Series C financing, representing 39% of total VC investment. The funding will be used to train a new generation of EDEN models and advance a pipeline of AI-designed therapeutics towards clinical development. Draig Therapeutics followed with a £49 million Series B raise, aimed at accelerating the development of its targeted AMPA and GABAA receptor modulators for neuropsychiatric disorders.
Redx Pharma raised £27 million ($36 million) in a Series A led by Abingworth, with participation from the British Business Bank and existing investor Redmile. The Series A is part of approximately £94 million ($125 million) in financing announced alongside a transaction with US-listed Skye Bioscience. The transaction is expected to complete in Q4, after which the combined company will trade on NASDAQ as Fibrx Therapeutics, led by Redx’s management team and headquartered at Alderley Park in Cheshire. The funding will take its lead fibrosis treatment, RXC008, into a Phase 2 trial for fibrostenotic Crohn’s disease. Only the £27 million Series A is included in this quarter’s figures.
Capital distribution and concentration
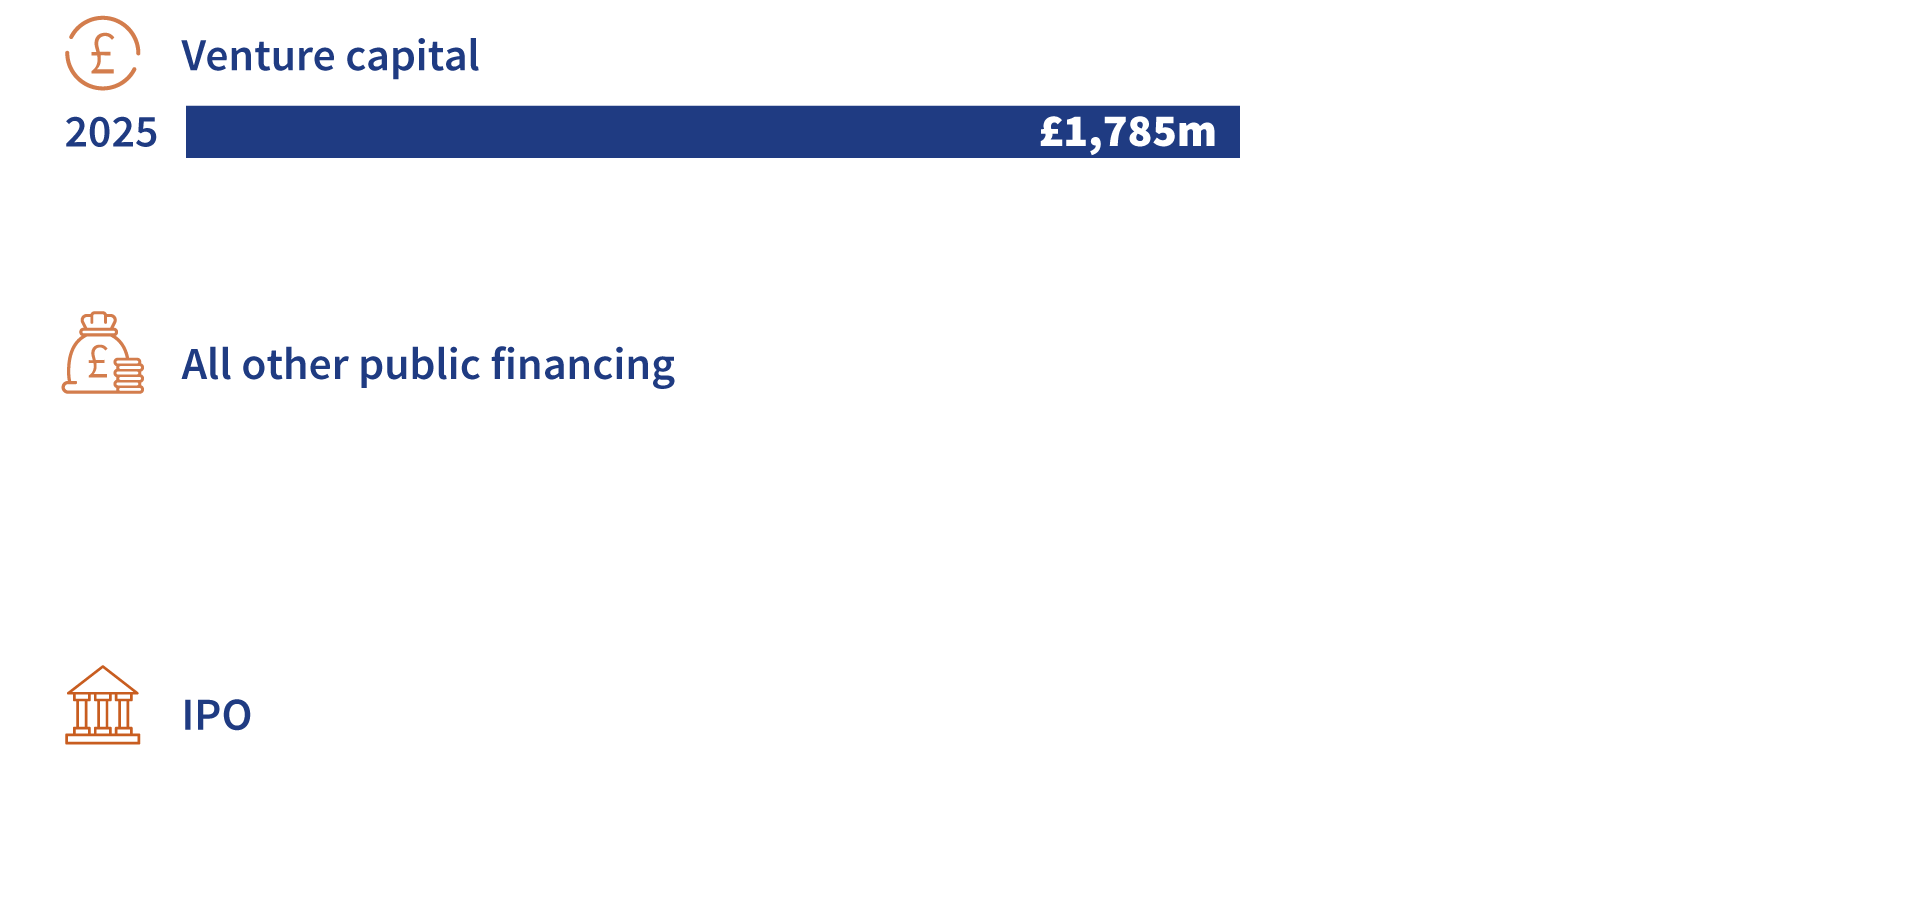
UK biotech venture capital investment totalled £2.84 billion in the first nine months of 2026, exceeding the full-year total of £1.79 billion recorded in 2025. However, investment remained heavily concentrated in larger financings, with rounds exceeding £100 million accounting for approximately 70% of capital raised. Isomorphic Labs’ £1.6 billion Series B financing alone accounted for approximately 55% of total investment.
Even excluding Isomorphic Labs’ £1.6 billion raise, underlying cumulative venture capital investment reached £1.28 billion in the first nine months of 2026. Notably, investment in both the £10 million–£25 million and £25 million–£50 million brackets has already surpassed the full-year totals recorded in 2025, indicating increased financing activity within these categories.
Deal activity also points to a broader funding base. The number of rounds between £10 million and £25 million has more than doubled compared with the whole of 2025, while smaller financings of £5 million or less continue to account for the largest share of transactions.
VC financing in Europe and the US
US biotech companies raised £5.2 billion in venture capital during Q3 2026, compared with £6.8 billion in Q2, a decrease of 23%. California remained the leading investment hub, raising £1.9 billion, followed by Massachusetts at £1.7 billion. Notably, Massachusetts recorded a 20% increase from Q2 (£1.45 billion), despite the overall decline in US investment. Massachusetts-based Sail Biomedicines secured approximately £452 million in venture capital financing from Johnson & Johnson’s corporate venture capital arm, JJDC.
European biotech venture capital totalled £1.1 billion, compared with £3.3 billion in Q2. Excluding the UK, European investment declined by 40.3%, from £1.3 billion in Q2 to £781 million in Q3. The UK retained its position as Europe’s largest individual market, attracting £270 million, approximately 26% of the European total. Switzerland followed with £190 million, while the Netherlands raised £186 million, overtaking Germany and France among the leading European markets. Notably, Switzerland-based Vaderis Therapeutics secured Europe’s largest biotech venture capital round of the quarter, raising approximately £113 million in a Series B financing. The funding will support the advancement of engasertib, a potential first-in-class treatment for hereditary haemorrhagic telangiectasia (HHT), through its global Phase III HEROIC trial.
The UK’s share is in line with the wider tech market: Dealroom and HSBC Innovation Banking found UK start-ups across all sectors took 25% of European venture capital in Q3.
 Public markets
IPOs
Although venture capital investment and headline follow-on financing were higher than in Q3 2025, UK biotech companies continued to raise no new capital through IPOs, extending the period without a new listing to 17 consecutive quarters.
International IPOs
US biotech companies raised £2.07 billion through IPOs in Q3 2026, compared with £2.21 billion in Q2, a decrease of approximately 6%. California dominated activity, accounting for £1.72 billion. California-based ADARx Pharmaceuticals completed the quarter’s largest US biotech IPO, raising approximately £333 million through an upsized NASDAQ offering. The company is developing next-generation siRNA therapeutics targeting a range of diseases, including cardiovascular, neurological and metabolic conditions.
In contrast, no biotech IPO proceeds were recorded in Europe during Q3, following £258 million raised in the previous quarter. This highlights the continued disparity between US and European IPO activity, with public listings remaining a more significant source of financing for US biotech companies.
Follow-on financings
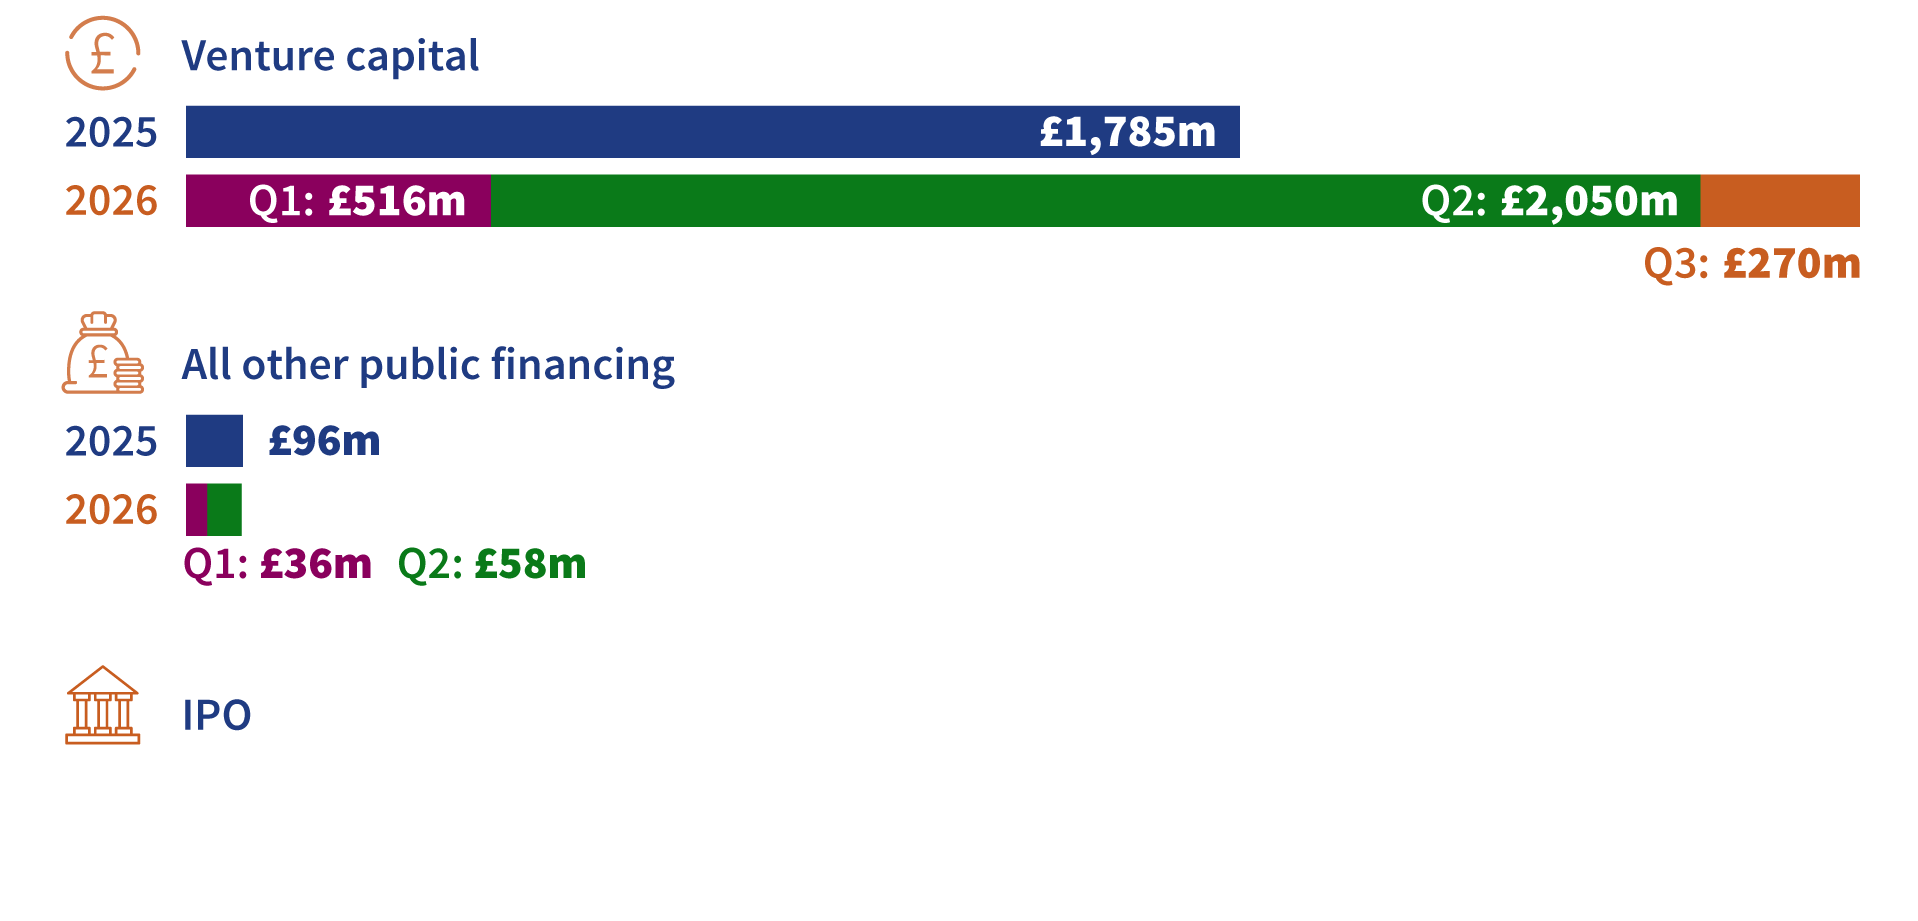
UK biotech follow-on financing reached £151 million in Q3 2026, compared with £11 million in Q3 2025 and £58 million in the previous quarter.
However, the headline increase was almost entirely driven by a single transaction, with Silence Therapeutics’ £130.3 million NASDAQ financing accounting for approximately 86% of the quarterly total.
Excluding Silence Therapeutics, follow-on financing amounted to just £20.7 million, highlighting the continued weakness in public market fundraising. Scancell completed the largest AIM financing of the quarter, raising £15.7 million.
Although year-to-date follow-on financing reached £245 million, exceeding the £96 million raised throughout 2025, activity remained concentrated in a limited number of transactions. The relatively modest sums raised outside Silence Therapeutics suggest that access to public equity capital remains challenging for UK biotech companies, particularly those listed on AIM.
International follow-ons
US biotech companies raised £5.98 billion through follow-on financing in Q3 2026, compared with £9.5 billion in Q2, a decrease of 37.2%. California (£2.9 billion) and Massachusetts (£2.2 billion) continued to dominate activity, together accounting for approximately 84.9% of US follow-on investment. Among the largest US transactions was BridgeBio Pharma’s approximately £747 million PIPE financing, led by Sixth Street with participation from HealthCare Royalty. The convertible preferred equity investment will support the company’s existing commercial operations and preparations for upcoming product launches targeting genetic diseases.
European follow-on financing totalled £1.4 billion, down 27.8% from £1.9 billion in Q2. France led European activity with £875 million, accounting for 62.5% of the regional total, followed by Switzerland (£225 million) and the UK (£151 million). Germany raised £100 million. France-based Abivax completed an approximately £687 million NASDAQ follow-on offering, following positive Phase III results for obefazimod, its investigational treatment for ulcerative colitis. The financing is expected to support preparations for potential commercialisation and continued clinical development.

Charts, maps and tables are based on BIA analysis of data from Beauhurst, h2Radnor, LSE and Pitchbook, 2026.